


- Tootsie Roll Industries reported third quarter 2026 revenue of US$229.05 million and net income of US$23.22 million, with basic earnings per share from continuing operations of US$0.31.
- Over the first nine months of 2026, Tootsie Roll Industries generated US$534.81 million in revenue and US$54.22 million in net income, pointing to earnings pressure that may focus attention on costs and product mix. An analyst report has also brought extra scrutiny to the business.
- Now the focus shifts to how Tootsie Roll Industries' softer earnings profile could influence the broader investment narrative around this confectioner.
What Is Tootsie Roll Industries' Investment Narrative?
To own Tootsie Roll Industries, you need to be comfortable with a fairly steady confectionery operation where brand strength matters more than rapid expansion. The third quarter report showed revenue and earnings under pressure compared with last year, which puts the spotlight on execution. For a shareholder, the belief has to be that management can protect volumes and pricing on core candies while keeping input and labor costs in check, rather than relying on big capital projects or transformative bets.
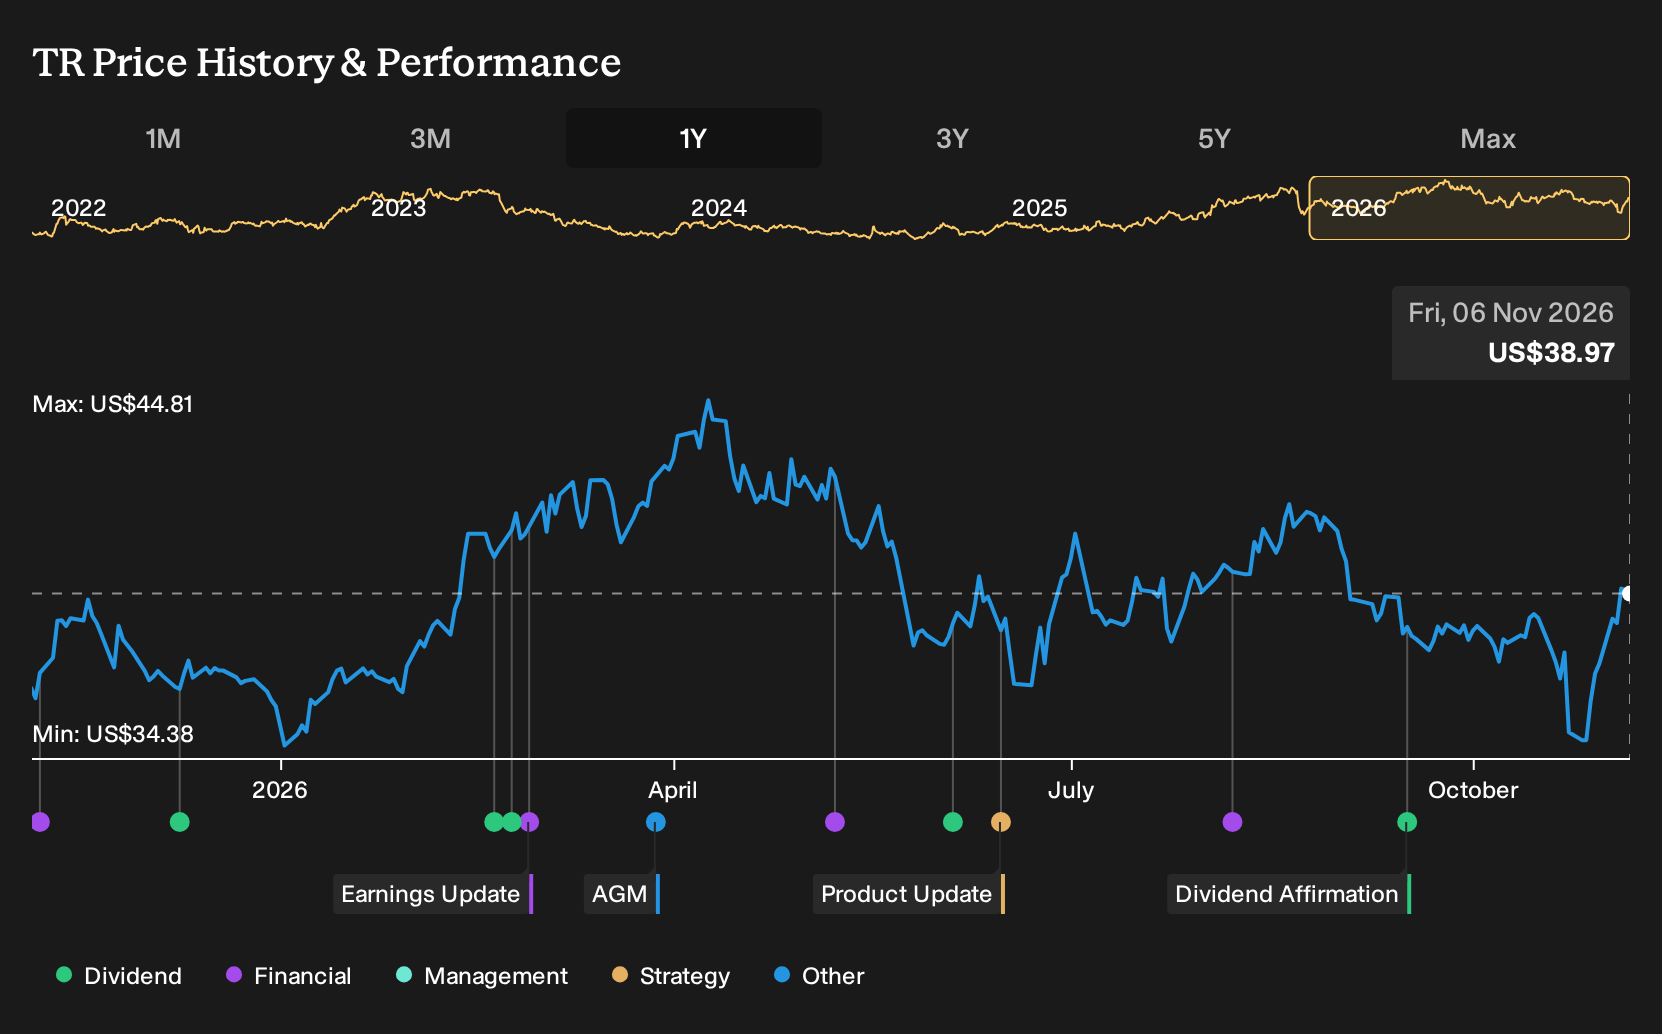
The latest earnings release, with softer net income over both the quarter and nine months, suggests the near term story is less about growth and more about margin resilience. That can weigh on sentiment when the stock already trades on a higher P/E than many food peers, even as at least one analyst lifts a price target. The risk is that any further slip in profitability or demand could challenge that premium.
Yet there is a less visible concern that sits underneath this premium story, and it starts with how Tootsie Roll Industries chooses to fund...
There's only one way to know the right time to buy, sell or hold Tootsie Roll Industries. Head to Simply Wall St's company report for the latest analysis of Tootsie Roll Industries's Fair Value.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Tootsie Roll Industries research is our analysis highlighting 1 key reward that could impact your investment decision.
- See our latest analysis for Tootsie Roll Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Tootsie Roll Industries' overall financial health at a glance.
Looking For More Investment Ideas Beyond Tootsie Roll Industries?
If Tootsie Roll Industries has sharpened your focus on quality, income, and balance sheet strength, it can help to broaden your watchlist with stocks that share some of those traits while offering different business profiles.
- If you care most about resilient financial footing, start with a list of solid balance sheet and fundamentals (24 results) that can help you zero in on businesses with stronger cushions against shocks.
- If income is a priority for your portfolio, scan through a curated set of 8 dividend fortresses that may offer more dependable cash flows than a single consumer stock can provide.
- If you are hunting for mispriced opportunities, sort through a focused group of 39 high quality undervalued stocks that pair fundamental strength with potentially more attractive entry points.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com