


- Stock Yards Bancorp reported third quarter 2026 results with higher net interest income of US$92.6 million and net income of US$43.51 million, alongside a sharp rise in net charge offs to US$3.95 million compared with US$112,000 a year earlier.
- The combination of stronger earnings and much higher credit losses puts attention on how Stock Yards Bancorp is managing loan quality and the premium valuation implied by its 15.7x P/E.
- The next area of focus is how Stock Yards Bancorp's investment narrative holds up when stronger earnings coincide with a jump in net charge offs.
What Is Stock Yards Bancorp's Investment Narrative?
To own Stock Yards Bancorp, you need to be comfortable with a fairly traditional regional bank story that leans on disciplined lending, a meaningful wealth management and trust arm, and a premium P/E of 15.7x that already prices in solid execution. Earnings support that narrative right now, with higher net interest income and profit, but the jump in net charge offs to US$3.95 million pulls attention straight back to underwriting, portfolio mix, and how management balances growth with credit discipline.
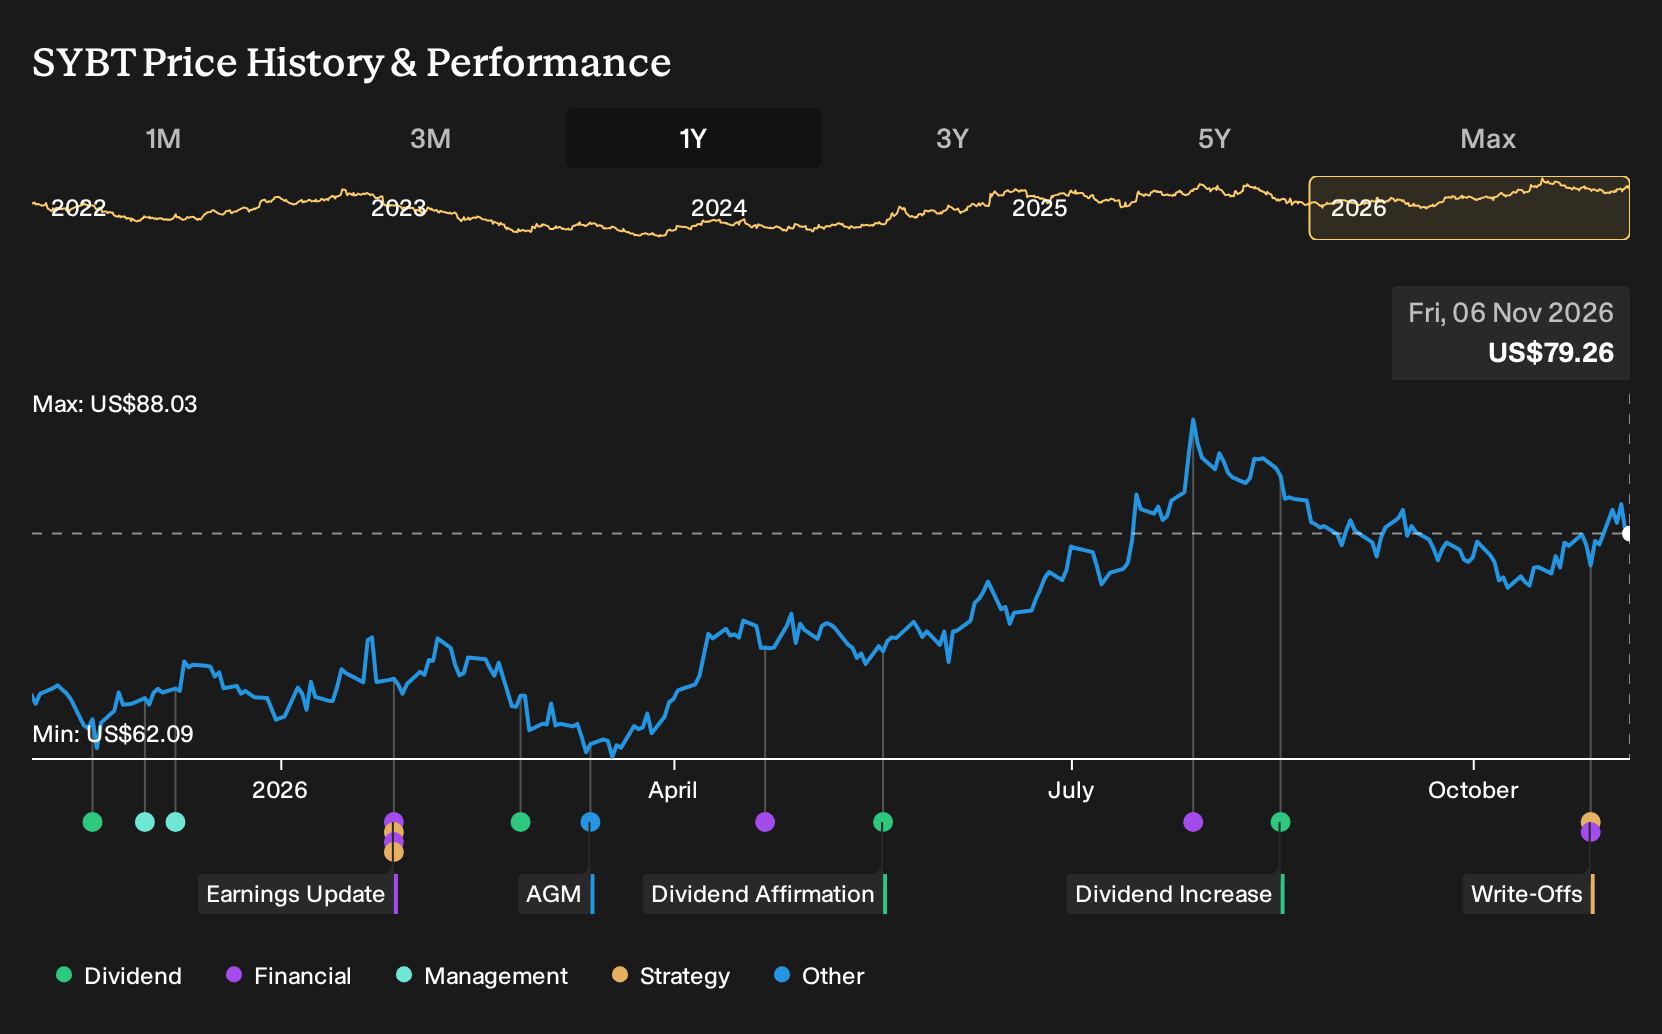
The Orlando Hovde conference appearance in early November gives Stock Yards Bancorp a chance to frame that trade off directly for institutional investors, especially with the share price up over the past year and beating both the wider US market and the banks sector. In the short term, the key swing factors look operational rather than macro, including how quickly charge offs stabilize, how much capital the bank needs to hold against problem loans, and whether that still justifies paying above industry multiples for what is otherwise a steady 1.67% dividend story.
Yet one quietly building pressure point inside that premium narrative is ...
There's only one way to know the right time to buy, sell or hold Stock Yards Bancorp. Head to Simply Wall St's company report for the latest analysis of Stock Yards Bancorp's Fair Value.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Stock Yards Bancorp research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Stock Yards Bancorp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Stock Yards Bancorp's overall financial health at a glance.
Looking For More Stock Yards Bancorp Scale Ideas?
If you want to stress test your view on Stock Yards Bancorp, compare it with a few other banks and financial names that share similar balance sheet or income traits. The Simply Wall St Screener is a quick way to surface candidates that match the kind of quality, value, or income profile you are looking for.
- For investors who care most about resilient balance sheets and funding strength, start with a curated list of solid balance sheet and fundamentals (24 results) that measure up on financial stability.
- If you want potential mispricing to be the main focus, filter for companies trading below fundamental estimates with our hand picked 39 high quality undervalued stocks that fit strict quality and valuation criteria.
- For readers who want income to do more of the work, scan a targeted 8 dividend fortresses that combine higher yields with robust underlying fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com