


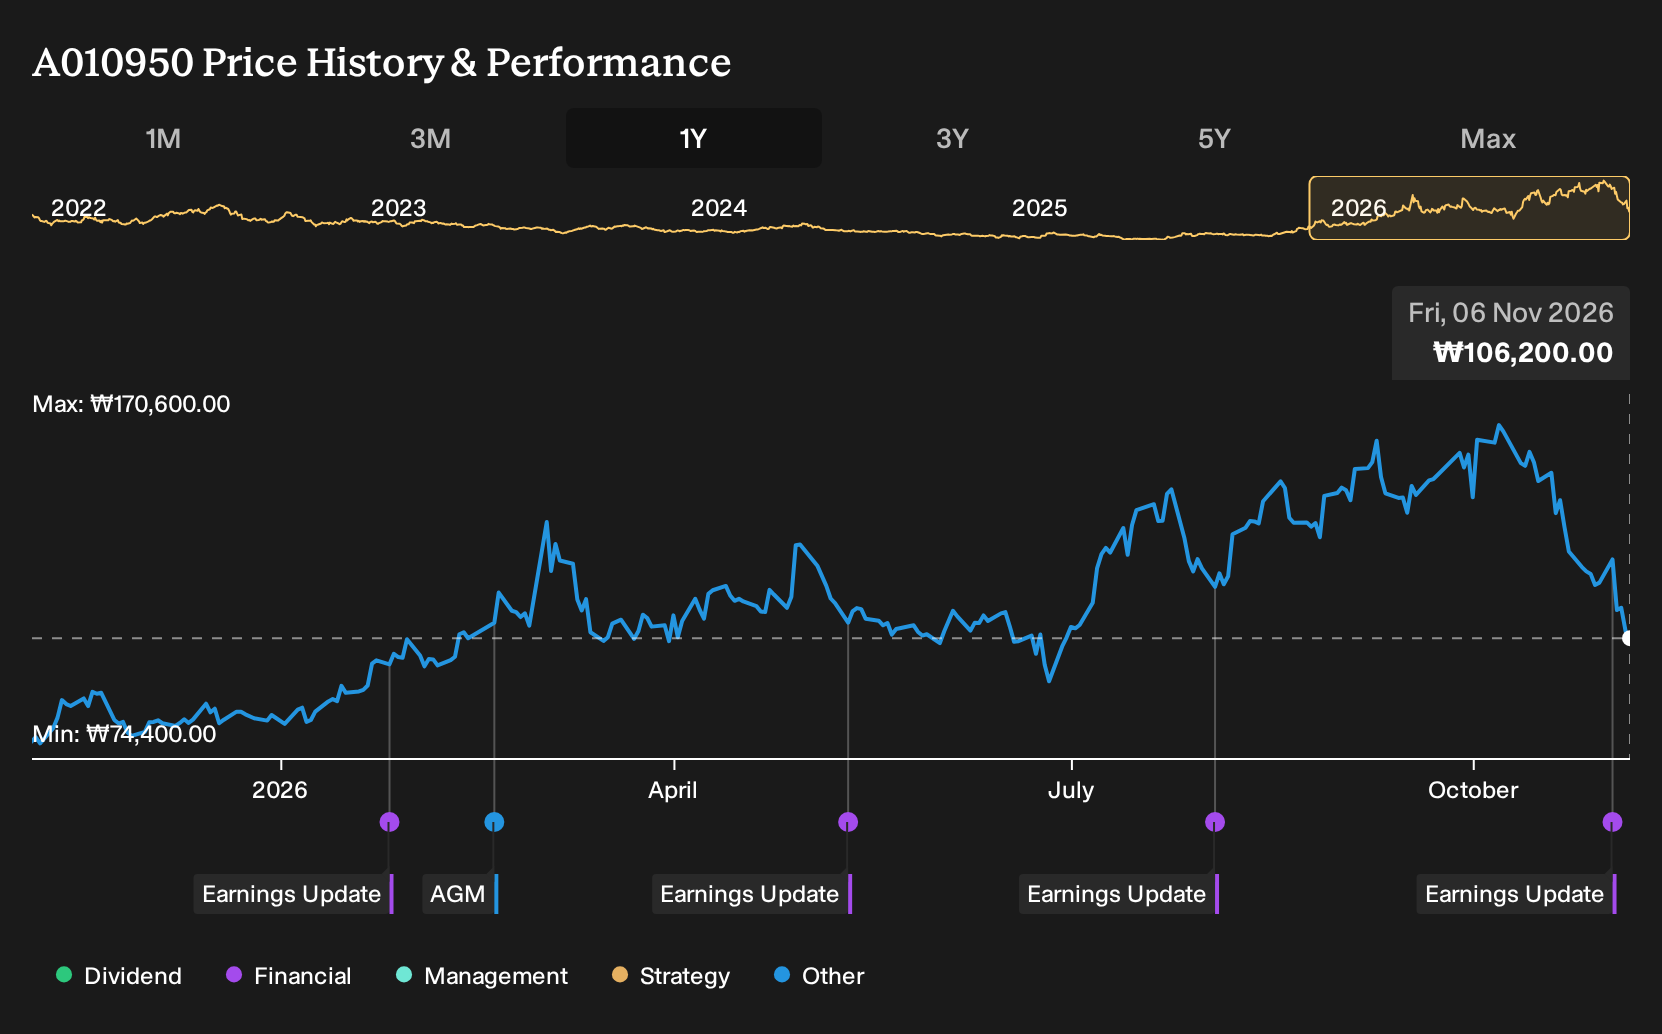
Investors who held S-Oil over the past year are up 44.0%, including dividends. If you had been weighing a purchase in November 2025, you were looking at a refinery-centered group with major plans around the Shaheen Project, along with sharply divided analyst targets: 17% above the start price on the bullish side and 32% below on the bearish side. Faced with that split, which part of S-Oil’s story would you have trusted most?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
S-Oil has already moved. See which of 224 high quality undervalued stocks still trade below our estimates.
The Two S-Oil Stories Investors Had To Weigh
The shares cost ₩76,600 at the start of the period, and anyone looking at S-Oil then had to decide which future seemed more reasonable.
On the upbeat side, the bullish Narrative put Fair Value at ₩90,000 and leaned on the Shaheen Project. That view rested on S-Oil using over 80% internal feedstock and higher self-power generation to support margin improvement.
The bearish Narrative pointed to a Fair Value of ₩52,000 and focused on the energy transition. Rising carbon pricing and tougher climate rules were treated as key threats to refinery profitability.
What The Results Changed For The S-Oil Debate
The clearest new data point came from S-Oil’s Q3 2026 report. Revenue moved from ₩8,415,367m in Q3 2025 to ₩11,968,700m, while net income rose from ₩63,206m to ₩1,435,600m and net margin shifted from 0.8% to 12.0%. This profitability jump supported the bullish focus on margins but did not remove longer term transition risks.
The lesson is simple. When a thesis hangs on better economics, watch net income and margin together, quarter by quarter, and test whether they move in the direction the story needs.
What S-Oil’s Price Seems To Assume Now
S-Oil trades at ₩106,200 today after a 44.0% gain over the past year. The selected Narrative’s Fair Value sits above the current price and leans on tight refining and lube markets, as well as the Shaheen project feeding into stronger through-cycle cash generation.
On that view, a buyer now would be testing whether today’s price still underestimates the durability of refining tightness and future Shaheen-driven cash flow.
"The Shaheen project is moving toward mechanical completion around mid 2026 and commercial operation in early 2027, with external estimates of a double digit internal rate of return once petrochemical spreads normalize. This could add a new earnings stream and lift overall net margins once the complex ramps up."
The price and this Narrative do not agree. → Uncover what this Narrative says S-Oil is actually worth
Another Piece Of The S-Oil Puzzle
S-Oil keeps your attention on refining margins and petrochemicals. You could also look sideways at how other energy producers handle long projects.
Some focus heavily on large upstream oil and gas fields and related LNG facilities. They work to keep lifting costs contained while bringing new capacity online.
The same groups are also building out carbon capture and storage services. That offers industrial customers a practical way to manage emissions alongside energy use.
If those fee based activities grow, the mix of cash flow can change. Watching that shift might sharpen how you read S-Oil’s transition plans.
That argument has a Narrative and a number behind it. → See the company one Narrative values 24% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com