


Viatris has delivered a powerful rebound, and after a 145.5% return over the past 3 years investors are increasingly asking whether the current share price still lines up with the company’s sales base. With fresh deal activity and product approvals in the mix, the question is how much of that story is already embedded in the valuation.
- Over 3 years, a 145.5% share price gain has reshaped the risk and reward around Viatris. This puts more weight on whether current revenue levels can support today’s market value.
- The planned US$1.65b acquisition of Pacira BioSciences and recent product wins may support higher expectations for future sales, while also committing Viatris to meaningful upfront cash outlay.
- There is a second opinion on Viatris worth weighing. See what analysts think Viatris's shares could be worth.
The stock’s next move may depend on whether Viatris’s current sales justify the price investors are now being asked to pay.
If you are weighing Viatris after its Pacira bid and recent product wins, it can help to compare this setup with other companies screened for 39 high quality undervalued stocks
Is Viatris a Bargain on Sales?
P/S suits Viatris because investors are weighing the share price against a sizable and relatively steady revenue base rather than current earnings swings.
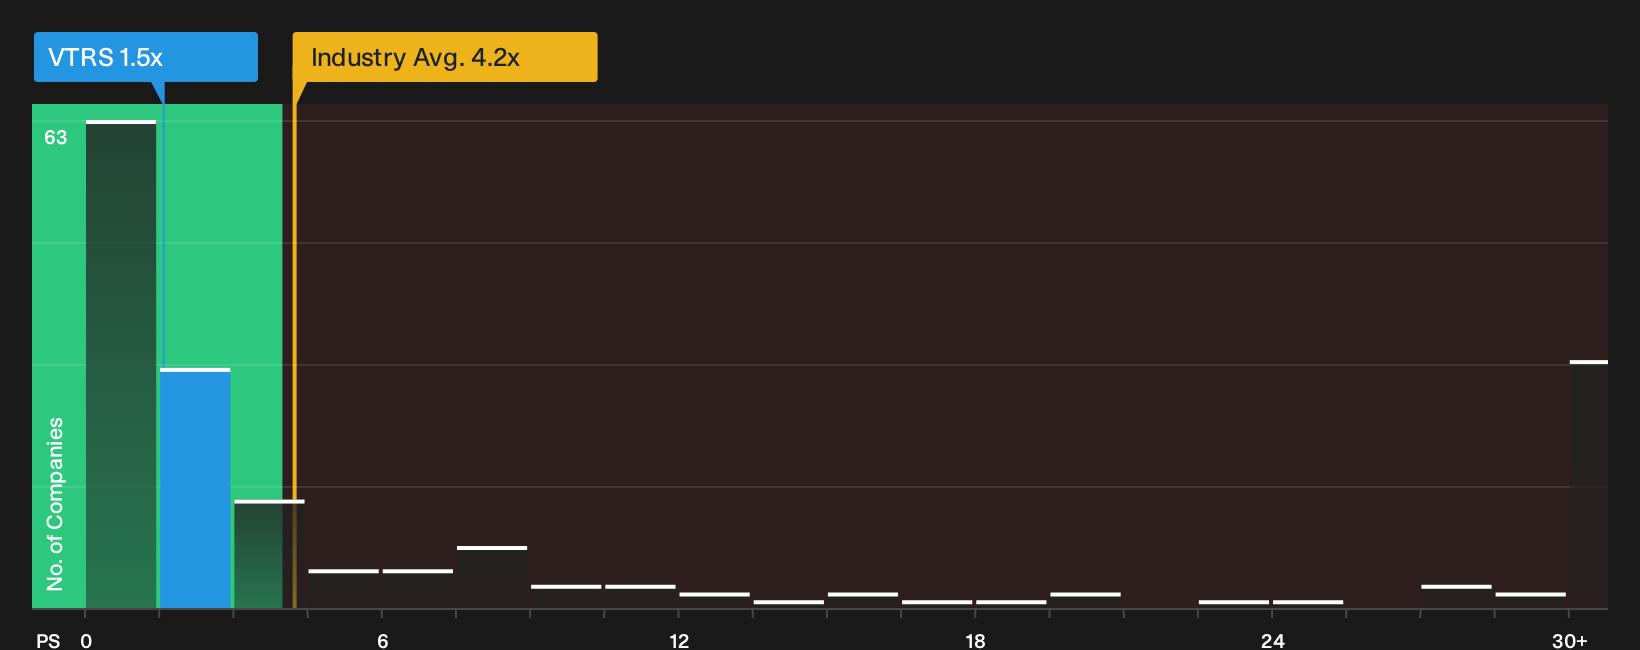
On this lens, Viatris trades on a P/S ratio of about 1.5x, which sits well below the Pharmaceuticals sector average of roughly 4.2x and the peer group near 5.1x. The modelled fair P/S multiple for the business, which blends its growth profile, margins, size and risk, sits higher than where the shares currently trade, so the stock screens undervalued on this measure. Because the framework points to a discount rather than a premium, the current tag implies investors are not paying industry-style prices for each dollar of Viatris revenue.
Because Viatris has just launched a US$1.65b Pacira offer and raised its 2026 guidance, the fact that the P/S ratio still comes in below both the sector and peer benchmarks suggests the recent news has not fully closed that gap. For a holder, the key question is whether the Pacira integration and new product approvals can keep supporting the sales base that underpins this revenue multiple. Explore the numbers behind Viatris's P/S valuation.
The Viatris Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Viatris pick up where the P/S puzzle leaves off and explain what would need to happen to Viatris' growth, profitability and earnings profile for the shares to be worth materially more or less than today’s quote, based on the scenarios you care about.
Rather than relying on a single multiple or model line, each Narrative lays out the key moving parts behind its view of fair value so you can compare those assumptions with the actual numbers as quarterly results and deal updates arrive.
Viatris draws two distinct camps, with one group seeing more upside in the current setup than the other.
Bull case: roughly fairly valued
"Expansion of higher-value branded and complex products such as the Gwyn Lo contraceptive patch and the planned Creon dose escalation label update in Europe is expected to shift Viatris' mix away from lower-margin oral generics and support revenue growth and gross margin resilience..."
Discover why this Narrative puts Viatris at roughly fairly valued.
Bear case: 42% overvalued
"The numbers currently reflected in the share price imply that Viatris shares already discount a successful transition toward value-added medicines, continued growth in regions such as Greater China and sustained capital returns, which leaves limited room for disappointment if execution slips..."
Explore why this Narrative puts Viatris at 42% overvalued.
One more piece of the Viatris story worth checking before you move on
Valuation only tells part of the Viatris story, and the research toolkit has also highlighted specific risk checks that could change how you view the whole setup once you see them. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com