


- CACI International announced in late October and early November 2026 that it secured several multi year U.S. defense contracts, including a five year, US$108 million award from the U.S. Air Force to sustain and modernize the Defense Enterprise Accounting and Management System and support financial transparency and mission readiness.
- The Air Force DEAMS mandate positions CACI International deeper inside a core financial operations platform where execution on Agile delivery, cybersecurity, and cloud enabled services can influence contract longevity, follow on work, and the mix of higher value technology oriented revenue.
- The next area of focus is how CACI International's investment narrative is shaped by this DEAMS modernization contract and its operating implications.
CACI International Investment Narrative Recap
For you to own CACI International, you need to be comfortable with a story built on long duration defense and federal contracts, a growing tilt toward higher value tech work, and the conversion of a US$32b backlog into stronger margins and cash generation. The current news flow around DEAMS and other recent awards supports that operating thesis but does not, on its own, change it.
The near term swing factor is still execution on large, complex programs that are expected to support higher EBITDA margins and better free cash flow. The biggest risk remains that heavier capex and integration costs fail to translate into improved cash conversion while debt is not yet well covered by operating cash flow.
The five year, US$108 million DEAMS award matters most because it reinforces CACI International’s push into software heavy, enterprise modernization work, where a higher fixed price and commercial like mix has been growing. This type of contract can support the narrative that more of the nearly US$10b in revenue comes from higher margin defense tech style activity.
What you should watch now is how effectively CACI International executes on DEAMS alongside the large Navy and Army task orders announced in late October. Strong delivery across these awards would support catalysts around margin resilience and backlog quality, while any schedule issues or cost overruns could feed existing concerns about free cash flow, returns on capital, and the premium P/E multiple.
CACI International's narrative projects US$12.2b revenue and US$727.8m earnings by 2029. This implies 8.3% yearly revenue growth and an earnings increase of about US$192m from US$535.8m today.
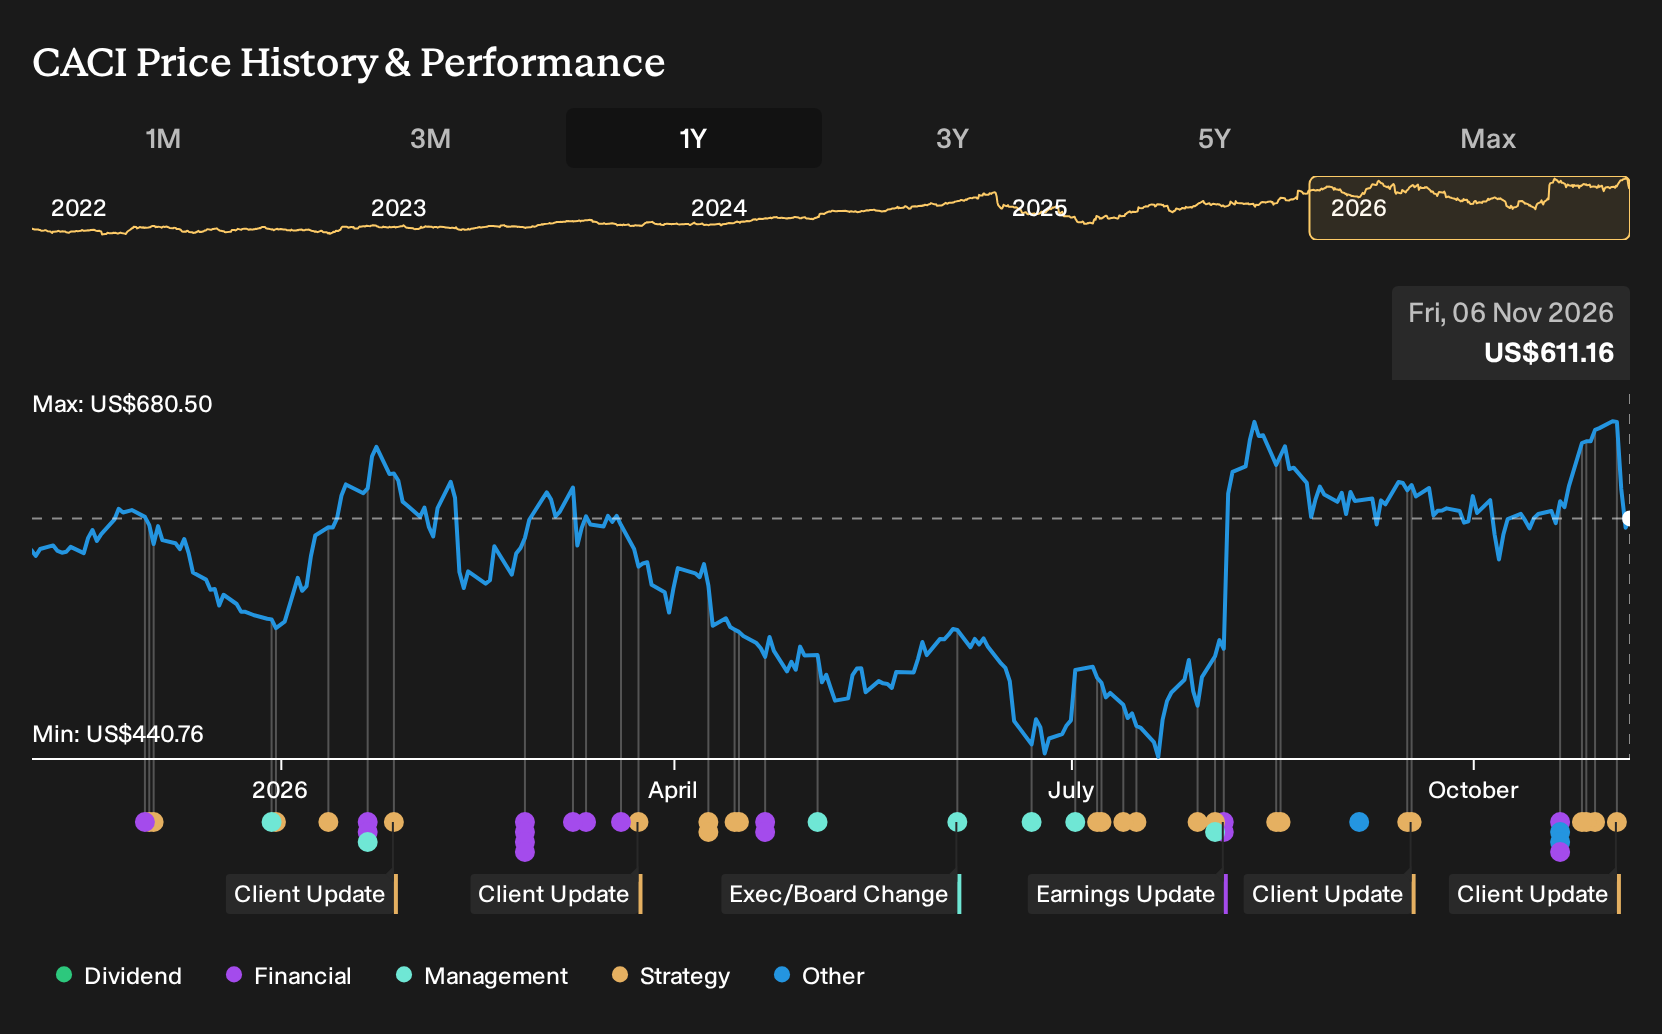
Discover why CACI International's fair value suggests a potential 20% upside from its current price before the discount begins to narrow.
Exploring Other Perspectives
Some of the lowest CACI International forecasts lean into execution risk on complex fixed price work. Before the DEAMS award, these analysts were modeling 7.5% annual revenue growth and about US$628.1m in 2029 earnings, well below the consensus US$727.8m. That gap shows how sharply opinions can diverge. Use it as a prompt to explore several different narratives.
Explore 3 other CACI International fair value estimates, including one that suggests it could be worth just $735.21!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your CACI International research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for CACI International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CACI International's overall financial health at a glance.
Looking For More Investment Ideas Beyond CACI International?
If the CACI International story has you thinking about where else long contract visibility, balance sheet strength, or income potential might show up, the Simply Wall St Screener is a useful way to filter for stocks that fit those themes.
- If capital preservation sits high on your list, focus on companies with steadier risk profiles by checking out our 29 resilient stocks with low risk scores.
- If you want income on top of potential price appreciation, scan for reliable payers through our 8 dividend fortresses.
- If you are hunting for quality that has not yet attracted broad attention, search through our 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com