


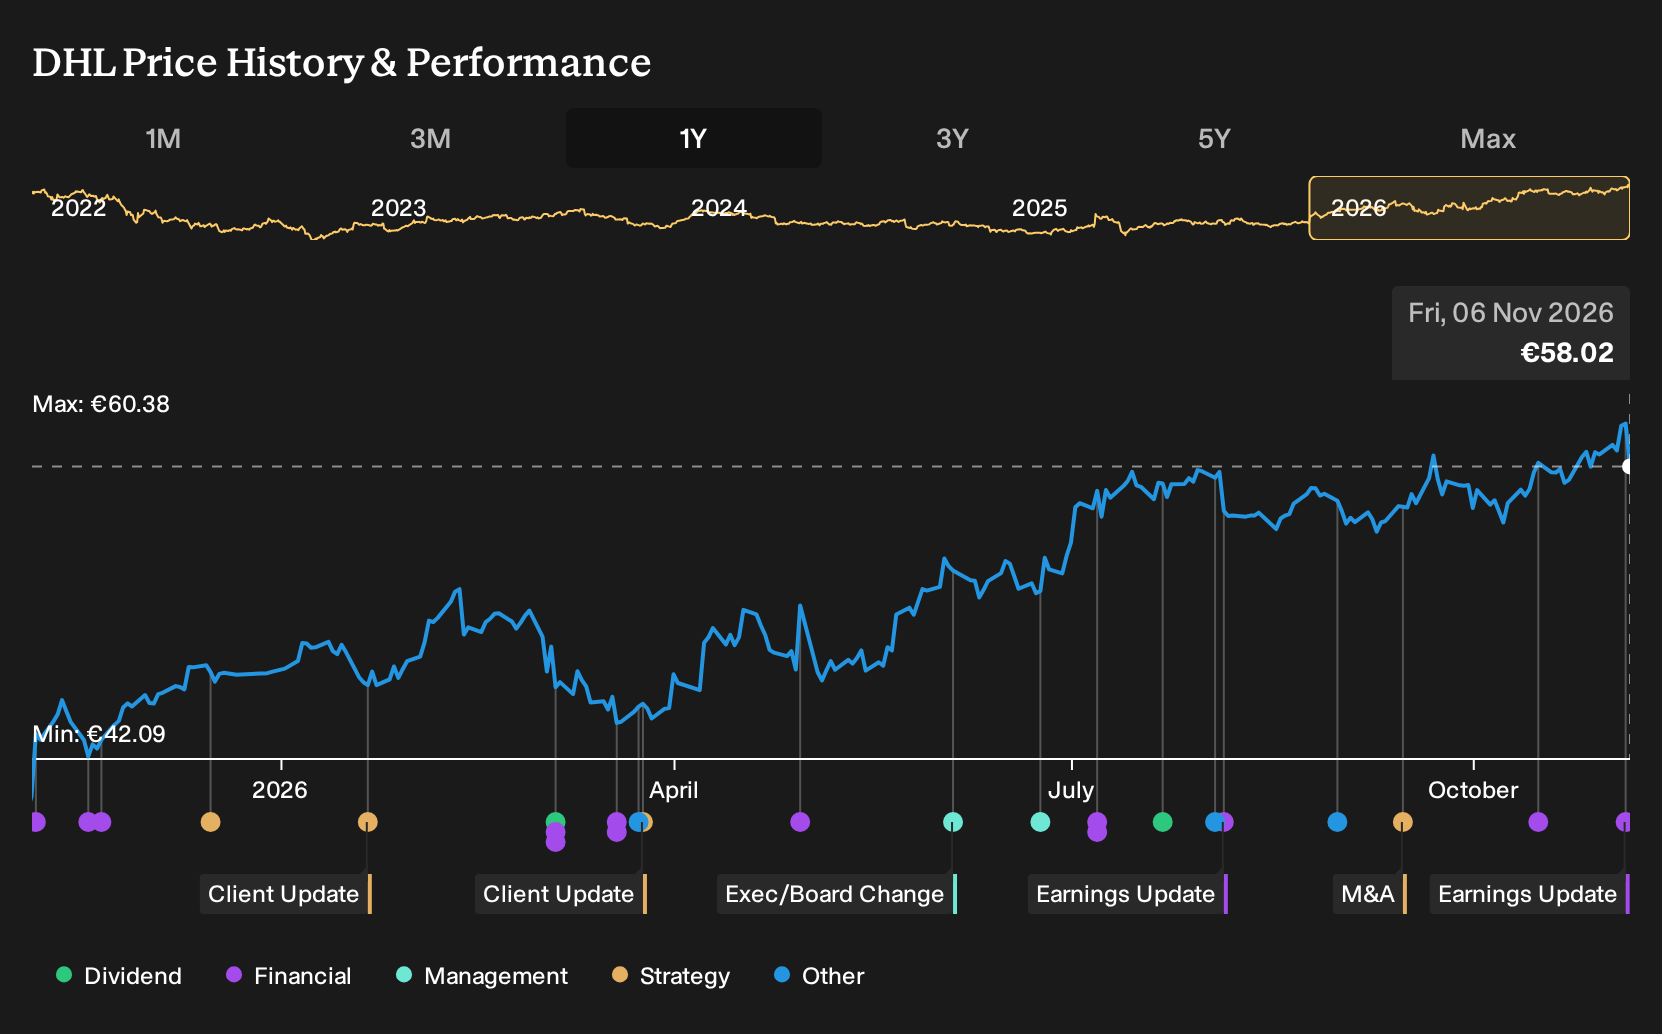
- DHL AG reported third quarter 2026 sales of €22,658 million and net income of €907 million, and raised its full year 2026 guidance for operating profit and free cash flow after stronger performance in Express and Global Forwarding.
- The logistics group beat earnings and revenue estimates, saw a 50% EBIT jump in Express and increased capital expenditure plans to about €3.6 billion, signaling heavier investment to support freight demand and longer term capacity.
- Next, the focus shifts to how DHL's higher 2026 earnings and cash flow guidance might reshape the existing investment narrative around execution.
DHL Investment Narrative Recap
To own DHL, you need to believe the logistics group can keep converting healthy shipment demand in Express and Global Forwarding into steady earnings and cash generation, even as regulations and trade flows shift. The upgraded 2026 EBIT and free cash flow guidance supports that case in the near term. The main short term catalyst is continued execution in Express heavyweight and industrial volumes, where recent EBIT strength gives management more room to push mix and pricing.
The biggest risk still sits with trade and regulatory friction. Customs changes on low value shipments and any cooling in global goods trade could hit volumes and net margins just as DHL leans into higher capital expenditure. Given the raised capex plan to about €3.6b, investors also have to watch that heavier investment does not dilute returns if freight demand normalises or de minimis rules tighten further.
The key fresh data point is DHL reporting third quarter 2026 sales of €22,658 million and net income of €907 million, along with higher full year guidance for operating profit to more than €7b and free cash flow to more than €3.2b. That update directly feeds into the execution story behind Express and Global Forwarding. It shows the business currently supporting heavier B2B and freight flows while holding earnings quality.
At the same time, third quarter free cash flow came in about 30% below analyst expectations, mainly because of U.S. tariff related outflows and higher investment. For you, that mix of stronger profit outlook with softer near term cash conversion sharpens the focus on capital discipline. If DHL keeps expanding its air network and automation while trade stays supportive, the raised guidance becomes an important test of how well Fit for Growth and Geo Tailwinds translate into durable returns versus simply higher complexity and debt load.
DHL's outlook projects €96.6 billion in revenue and €4.7 billion in earnings by 2029. This is based on an assumed 4.1% yearly revenue increase and an earnings rise of about €1.0 billion from €3.7 billion today.
Uncover why DHL's fair value indicates that DHL is roughly in line with its current price.
Exploring Other Perspectives
One brighter angle on DHL comes from analysts who treated the Fit for Growth cost cuts as the real story. Before this earnings release, the most optimistic forecasts already pencilled in revenue climbing toward about €101.4b and earnings around €4.9b by 2029. Those estimates were set without seeing this quarter, so you can decide whether this guidance shift nudges your own view closer to that bullish camp or not.
Explore 6 other DHL fair value estimates, including one that suggests the potential for as much as 48% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd. Trust your own analysis and judgment.
- A great starting point for your DHL research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for DHL. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate DHL's overall financial health at a glance.
Looking for more DHL investment ideas?
If the latest DHL update has sharpened your view on execution and cash generation, it can be useful to compare that thesis against other companies that share some of the traits you care about most. The Simply Wall St Screener lets you filter for those patterns directly so you can stress test your DHL conviction against a broader watchlist.
- If you want sturdier balance sheets to sit alongside DHL, start with a list of solid balance sheet and fundamentals (191 results) that can help you filter for resilience and funding flexibility.
- If value is your anchor, weigh DHL against a curated 219 high quality undervalued stocks that blends stronger fundamentals with more modest pricing.
- If you prefer lower volatility and fewer surprises, compare DHL with a 213 resilient stocks with low risk scores that tilts toward steadier risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com