


Lightspeed Commerce has seen its share price under pressure in recent years, which puts fresh attention on what investors are really paying for each dollar of the company’s sales. With the stock now reflecting a long stretch of weak returns, the question is whether today’s valuation lines up with the underlying revenue base.
- Over the past 5 years the stock has fallen 83.4%, which puts the spotlight squarely on whether the current price still makes sense relative to its sales.
- The business model relies on converting payment and software volumes into recurring revenue, which can influence how much investors are prepared to pay for each unit of turnover if growth or profitability expectations shift.
- The analysts covering Lightspeed Commerce have run their own numbers. See what analysts think Lightspeed Commerce's shares could be worth.
For investors, the debate is whether Lightspeed Commerce’s current share price is properly supported by the scale and quality of its sales.
If you want to compare how fairly priced Lightspeed Commerce looks on its sales against a broader group, you can line it up next to 6 high quality undervalued stocks
Is Lightspeed Commerce Still Cheap on Sales?
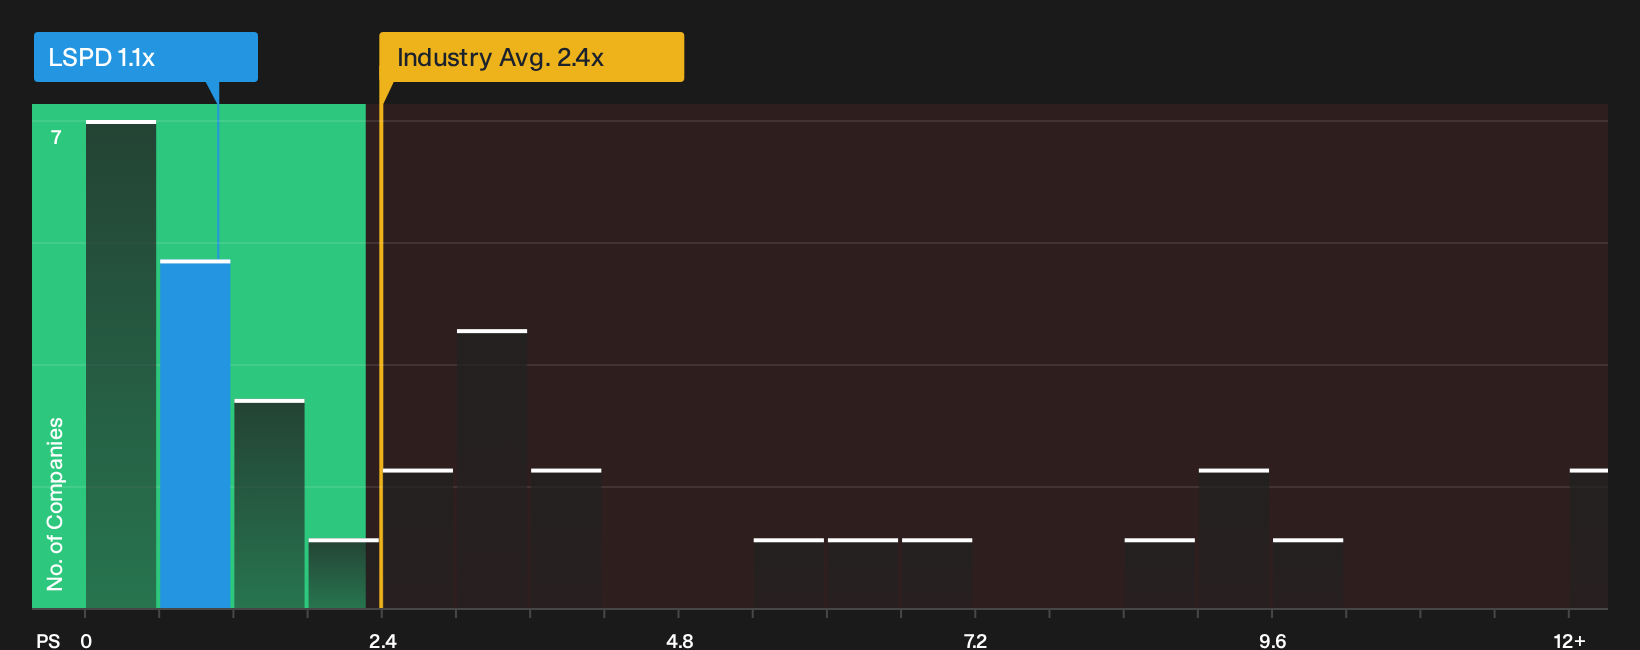
P/S is a useful lens for Lightspeed Commerce because the business is still being judged heavily on its revenue base rather than on mature earnings. On that score, the stock trades on a P/S ratio of about 1.1x, which is well below the diversified financials industry average of roughly 2.8x and also under the peer group average near 4.1x.
The gap is even wider when lined up against a tailored fair multiple that adjusts for the company’s sector, scale and risk profile, because the current P/S sits meaningfully below that modelled level and screens as undervalued on this framework. For anyone assessing whether the share price already reflects a long stretch of weak returns, the key question is whether Lightspeed Commerce’s future margins and growth potential justify the discount that this low sales multiple implies. Explore the numbers behind Lightspeed Commerce's P/S valuation.
The Lightspeed Commerce Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/S puzzle leaves off for Lightspeed Commerce by spelling out what kind of revenue, margin and earnings path would need to unfold for the stock to be worth meaningfully more or less than it is today. Each narrative links its number to a clear view on how growth, profitability and risk could evolve, which gives you something concrete to revisit as new information comes through.
Community views on Lightspeed Commerce split between those who see underappreciated progress in payments and capital and those who focus on margin strain and cash generation.
Bull case: 18% undervalued
"Embedding AI across customer facing products and internal operations, including AI agents, AI menu imports, AI-driven recommendations and AI resolution of about 80% of support tickets…"
Discover why this Narrative puts Lightspeed Commerce at 18% undervalued.
Bear case: 31% overvalued
"The current numbers, including ongoing operating losses alongside share buybacks, imply the market is already pricing Lightspeed Commerce for strong execution on revenue growth, margin targets and capital returns…"
Explore why this Narrative puts Lightspeed Commerce at 31% overvalued.
The share price is only one clue in the Lightspeed Commerce story
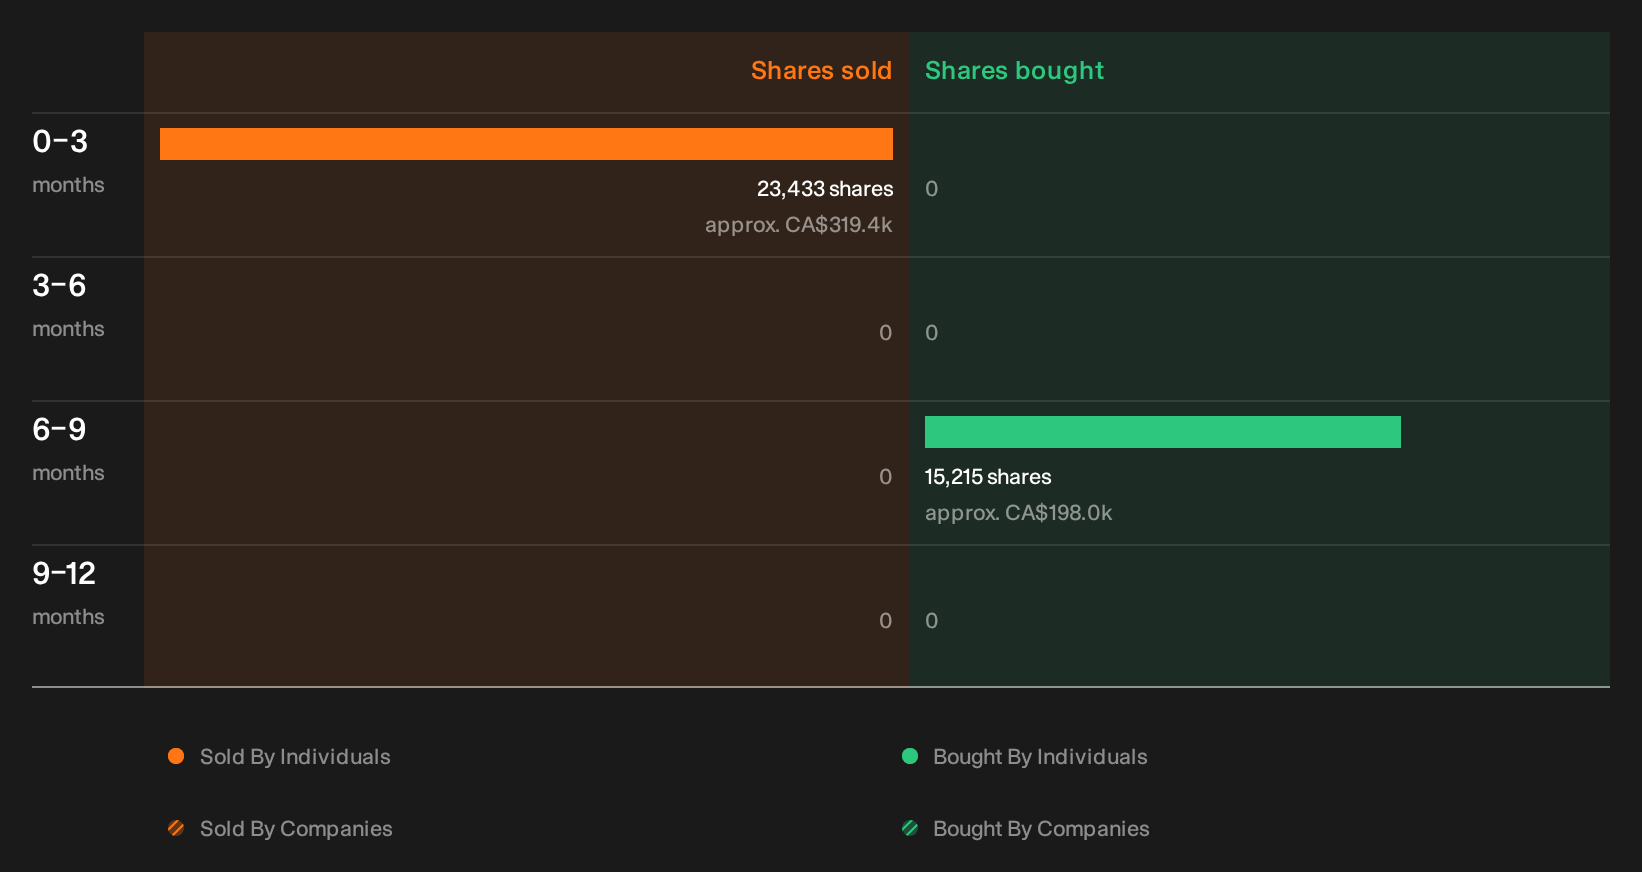
Before you decide what Lightspeed Commerce is worth to you, it is worth checking what company insiders have been doing with their own holdings, including who has been selling and in what size. See the recent insider selling flagged for Lightspeed Commerce.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com