


Sempra (SRE) reset the conversation around its stock after raising full-year 2026 GAAP EPS guidance to a range of US$7.41 to US$8.41, alongside strong third quarter earnings.
Despite the upbeat guidance, Sempra’s share price has slipped. The 7 day share price return is down 9.2% and the year to date share price return is down 12.9%, even as the 5 year total shareholder return of 49.8% points to stronger longer term momentum that recent earnings and capital plans have not yet fully reflected in the current US$78.17 trading level.
Compare Sempra’s reset guidance and weak recent returns with a hand-picked 39 high quality undervalued stocks that also pairs regulated cash flows with pressure on their current share prices.
Strong earnings, higher guidance and a falling Sempra share price point to a simple fork in the road: Are investors reacting to fundamentals, or has sentiment moved further than the business reality justifies as valuation now gets tested next?
Most Popular Narrative: 21% Undervalued
Sempra closed at $78.17 while the most followed narrative framework points to a fair value of $99.03. The recent share price slide sits against a valuation anchor that implies a meaningful gap.
The US$47.5b five year base capital plan at Oncor, along with US$10b of incremental identified projects tied to ERCOT endorsed upgrades, reliability work and future resiliency filings, keeps the earlier thesis about sustained capital deployment into transmission and distribution assets in place as a driver of long term earnings growth.
See why 28 investors see Sempra as 21% undervalued.
Result: Fair Value of $99.03 (UNDERVALUED)
Still, Sempra’s story can break if regulators reduce allowed returns in California or Texas, or if LNG construction delays defer expected cash generation.
Find out about the key risks to this Sempra narrative.
Another View: Sempra And The Cash Flow Debate
While analysts frame Sempra as undervalued at a fair value of $99.03, the SWS DCF model lands in a very different place. On that measure, the current $78.17 share price sits above an estimated future cash flow value of $45.56, which implies less room for error if growth or margins underperform.
For readers who want to unpack why a cash flow model can disagree so sharply with an analyst framework, Look into how the SWS DCF model arrives at its fair value.
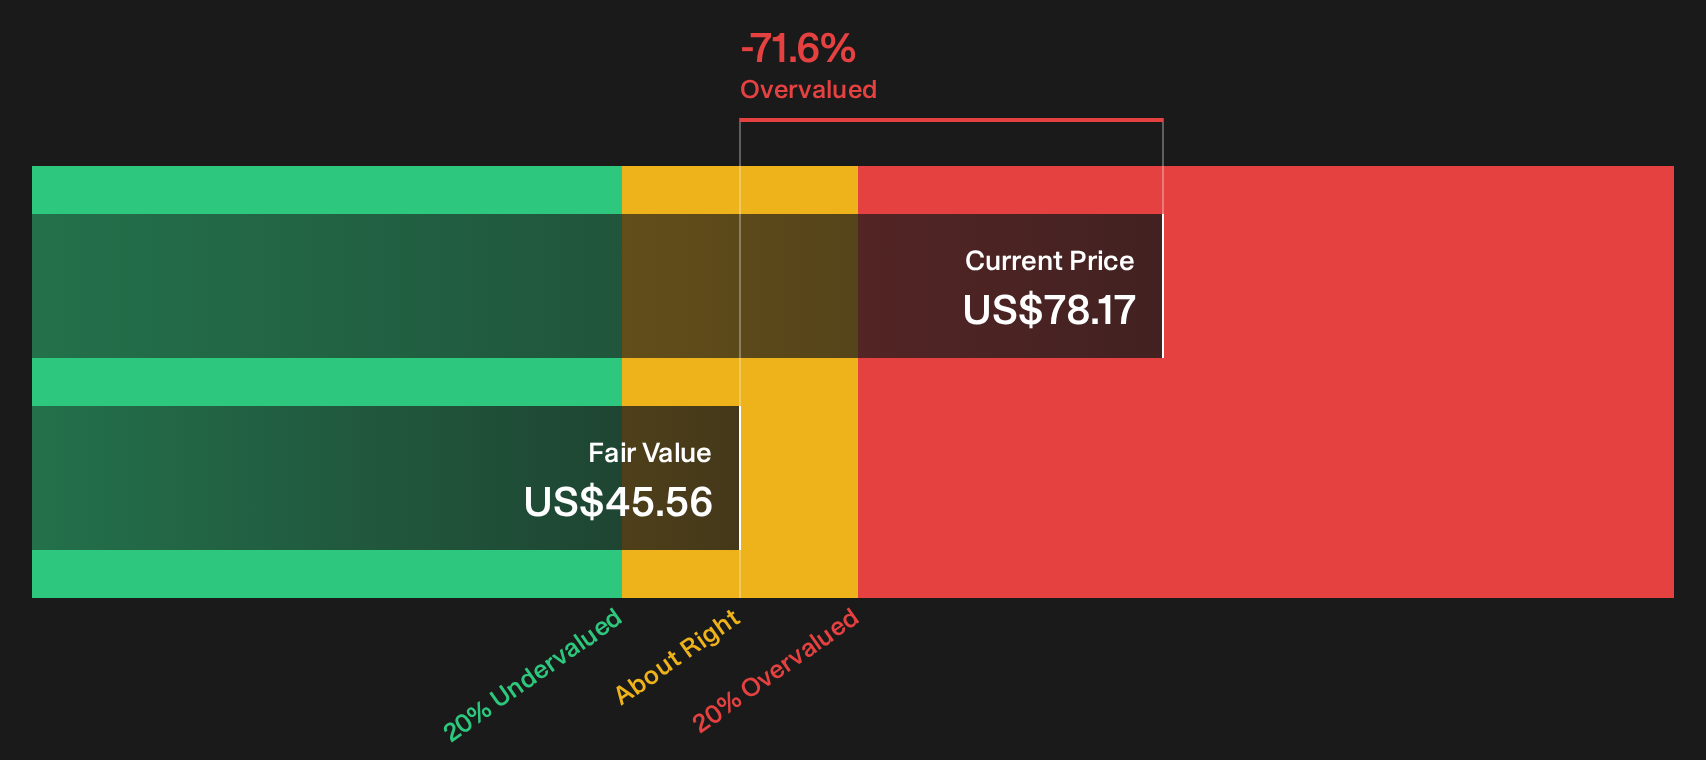
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Sempra for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 39 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Sempra can be useful if you treat them as a prompt rather than an answer. Move quickly, review the data yourself, then weigh up the 5 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Sempra?
If Sempra has sharpened your thinking on valuation and risk, do not stop there. Use focused screeners to spot other opportunities that could fit your playbook.
- Target resilient balance sheets and cleaner fundamentals by scanning a list of solid balance sheet and fundamentals (24 results) that filters for financial strength first.
- Hunt for mispriced quality by reviewing a 39 high quality undervalued stocks that highlights companies where fundamentals and current pricing look out of sync.
- Get ahead of the crowd by checking a 19 high quality undiscovered gems that surfaces underfollowed businesses with stronger underlying metrics than the attention they receive.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com