


Woolworths Group (ASX:WOW) has drawn fresh attention after first quarter sales reached A$19,353 million for the period to 4 October 2026, compared with A$18,483 million a year earlier.
That sales update landed alongside strong price momentum, with a 1-day share price return of 1.75% on Friday and a 7-day share price gain of 5.54% helping lift Woolworths Group to A$42.45. The recent Q1 sales news and sector strength in consumer staples have fed into a 30-day share price return of 9.27% and a 44.24% year to date share price gain. The 1-year total shareholder return of 53.84% and 3-year total shareholder return of 31.61% point to momentum that has been building rather than fading.
Scan how Woolworths Group compares to other defensive consumer stocks by reviewing our curated list of 6 resilient stocks with low risk scores.
For Woolworths Group, the surge in Q1 sales and a 53.84% 1-year total shareholder return could signal a business driven by its own performance rather than just riding sentiment. Do the current market terms reflect that reality?
Most Popular Narrative: 8% Overvalued
Against a quoted fair value of A$39.32 from the most followed Woolworths Group narrative, the last close at A$42.45 points to a premium that hinges on confidence in execution around automation, e commerce and adjacent earnings streams.
Growing contribution from complementary businesses such as Petstock, PFD, Cartology, Everyday Rewards and Primary Connect Plus, which together delivered about one third of FY26 group EBIT growth, provides Woolworths Group with additional earnings streams that can influence overall EBIT mix and cash generation.
See why 89 investors see Woolworths Group as 8% overvalued.
Result: Fair Value of A$39.32 (OVERVALUED)
Still, Woolworths Group relies on cost savings and automation to stay ahead of tighter pricing rules and any prolonged weakness in New Zealand Food earnings.
Find out about the key risks to this Woolworths Group narrative.
Another View: Cash Flows Point Higher For Woolworths Group
The analyst narrative frames Woolworths Group as about 8% overvalued against a fair value of A$39.32 that leans on earnings forecasts and P/E assumptions. The SWS DCF model tells a different story, with a future cash flow value of A$62.36 that sits well above the A$42.45 share price. Which lens do you trust more when profits and cash tell different stories?
Look into how the SWS DCF model arrives at its fair value.
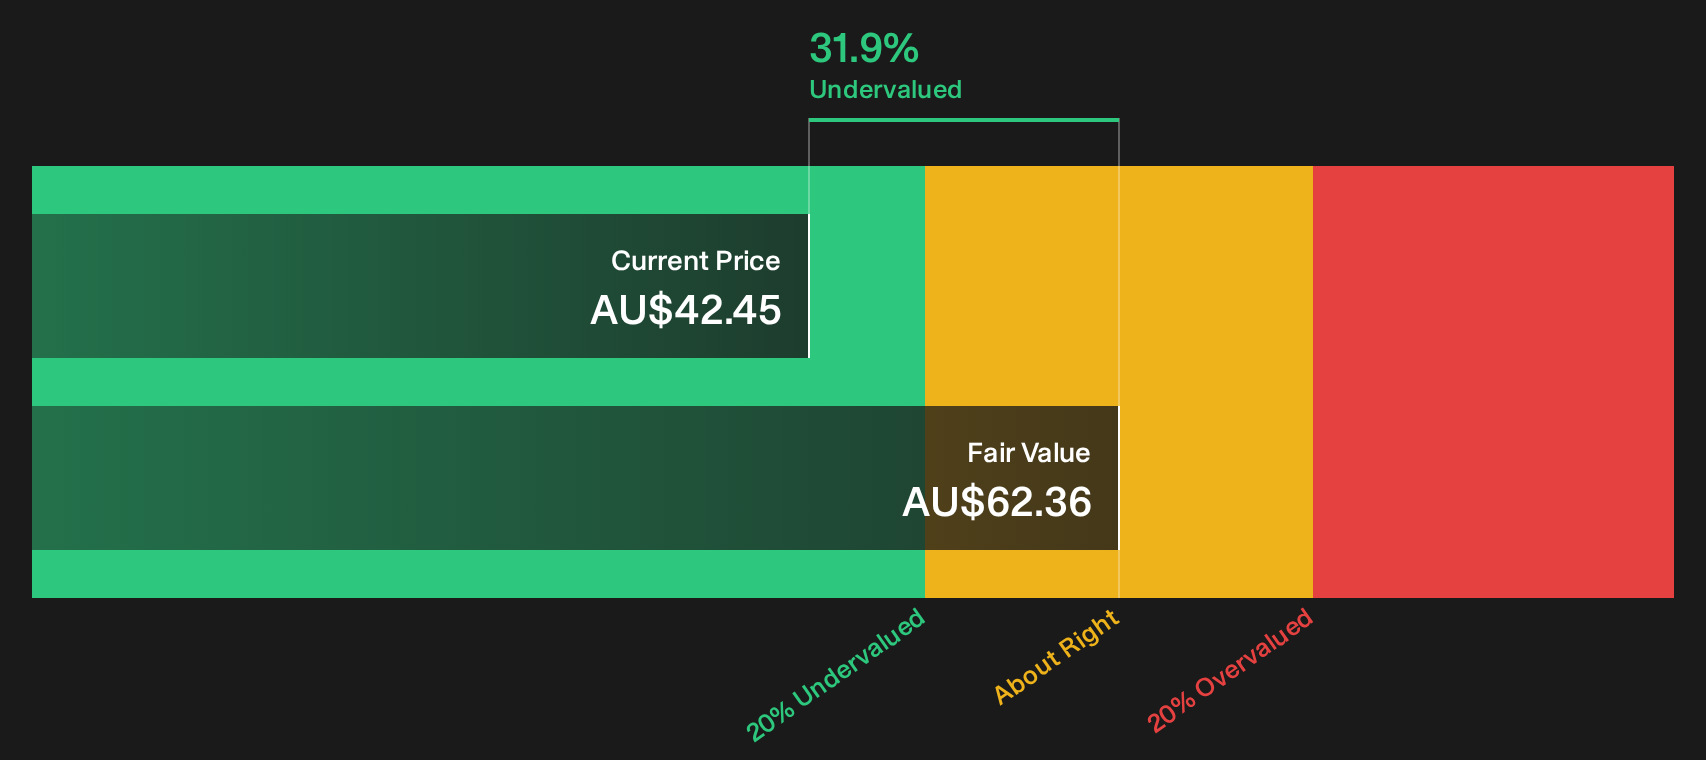
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Woolworths Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 3 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Woolworths Group is split, with clear risks on one side and meaningful upside drivers on the other. Investors may wish to act quickly and pressure test the numbers for themselves. To weigh both angles in one place, start with our breakdown of 3 key rewards and 1 important warning sign
Looking for more Woolworths Group sized ideas?
If you only focus on Woolworths Group, you could miss other opportunities that fit your risk, income or value goals. Put a few minutes into screening and stack the odds in your favour.
- Target resilient balance sheets and dependable fundamentals by scanning our list of solid balance sheet and fundamentals (12 results).
- Hunt for value that lines up with quality by reviewing the 3 high quality undervalued stocks.
- Build a portfolio with income at its core by checking out the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com