


Rayonier (RYN) just reported third quarter results that showed net income of US$123.3 million and earnings of US$0.41 per share, alongside an expanded US$600 million share repurchase program.
Rayonier’s recent quarterly numbers and the expanded buyback plan arrived alongside a sharp short-term rebound, with a 7 day share price return of 11.2% and a 30 day share price return of 19.79%. However, the 1 year total shareholder return remains slightly negative at 1.57% and the 5 year total shareholder return is down 22.57%. This combination points to improving momentum in the near term, while the longer track record is still recovering in the eyes of investors.
Compare Rayonier’s rebound and buyback story with other asset backed plays by scanning our curated list of solid balance sheet and fundamentals (24 results) that may be drawing fresh attention after recent earnings updates.
Rayonier has just jumped on stronger earnings and a larger buyback, which puts you at an awkward crossroads. Is it smarter to lean into this move now, or wait for a cooler entry before running the numbers?
Most Popular Narrative: 9% Undervalued
Rayonier last closed at $21.55, while the most followed narrative pegs fair value nearer to $23.67, which nudges the story toward undervalued territory and frames the recent rebound as only part of the gap.
Continued conversion of Southern timberland into rural HBU sales and larger development projects such as Wildlight, Heartwood and Chenal, where management points to 50 to 100% premiums on recent rural tracts and the potential for 10 to 15 times higher values on development acres, has scope to lift real estate revenue and segment margins as more acres are brought to market.
See why 23 investors see Rayonier as 9% undervalued.
Result: Fair Value of $23.67 (UNDERVALUED)
Still, the Rayonier narrative can be knocked off course if timber pricing pressure lingers, or if real estate and solar land deal pipelines take longer to close.
Find out about the key risks to this Rayonier narrative.
Another View: Rayonier Looks Expensive On Earnings
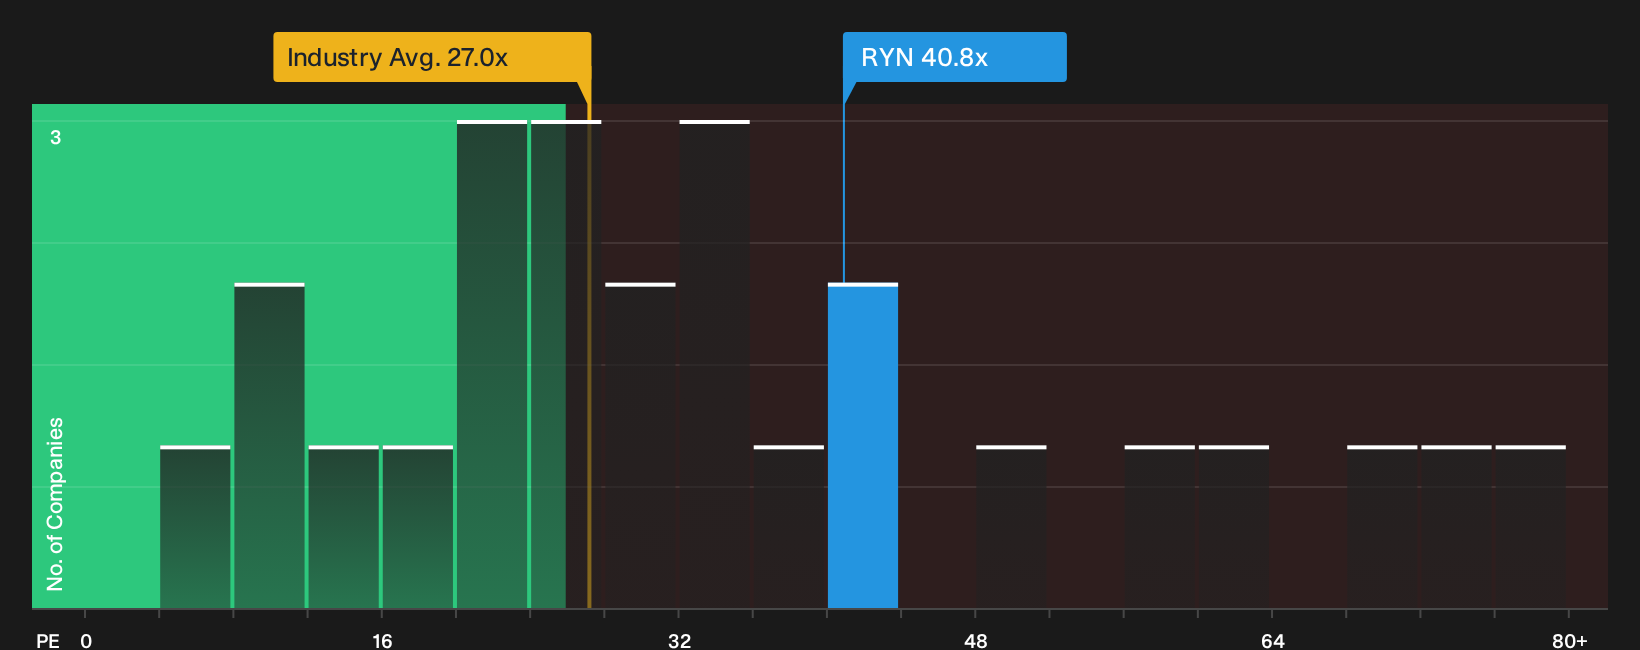
Rayonier may screen as undervalued against a fair value of $23.67, yet its P/E of 40.8x sits well above both the North American Specialized REITs average of 27.9x and a peer average of 25.1x. The fair ratio of 48.6x suggests room either way. Is this a margin of safety or valuation risk that could close quickly?
Investors who prefer to anchor on earnings multiples rather than narrative fair values may want to stress test their own expectations against this gap before acting, then review how the detailed valuation breakdown frames that spread in practical terms through the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Complex mix of risks and rewards around Rayonier so far. Act quickly, review the full data set, and weigh both sides through the 2 key rewards and 3 important warning signs
Looking for more investment ideas beyond Rayonier?
If Rayonier has your attention, do not stop there. Broaden your watchlist now so you are not chasing ideas after the opportunity has moved.
- Target potential mispricing opportunities by scanning a curated pool of quality companies that may trade below estimated value with the 39 high quality undervalued stocks.
- Lock onto income focused opportunities by reviewing companies with higher yields and resilient payouts using the 8 dividend fortresses.
- Prioritise resilience and capital protection by filtering for companies that carry lower risk scores through the 29 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com