


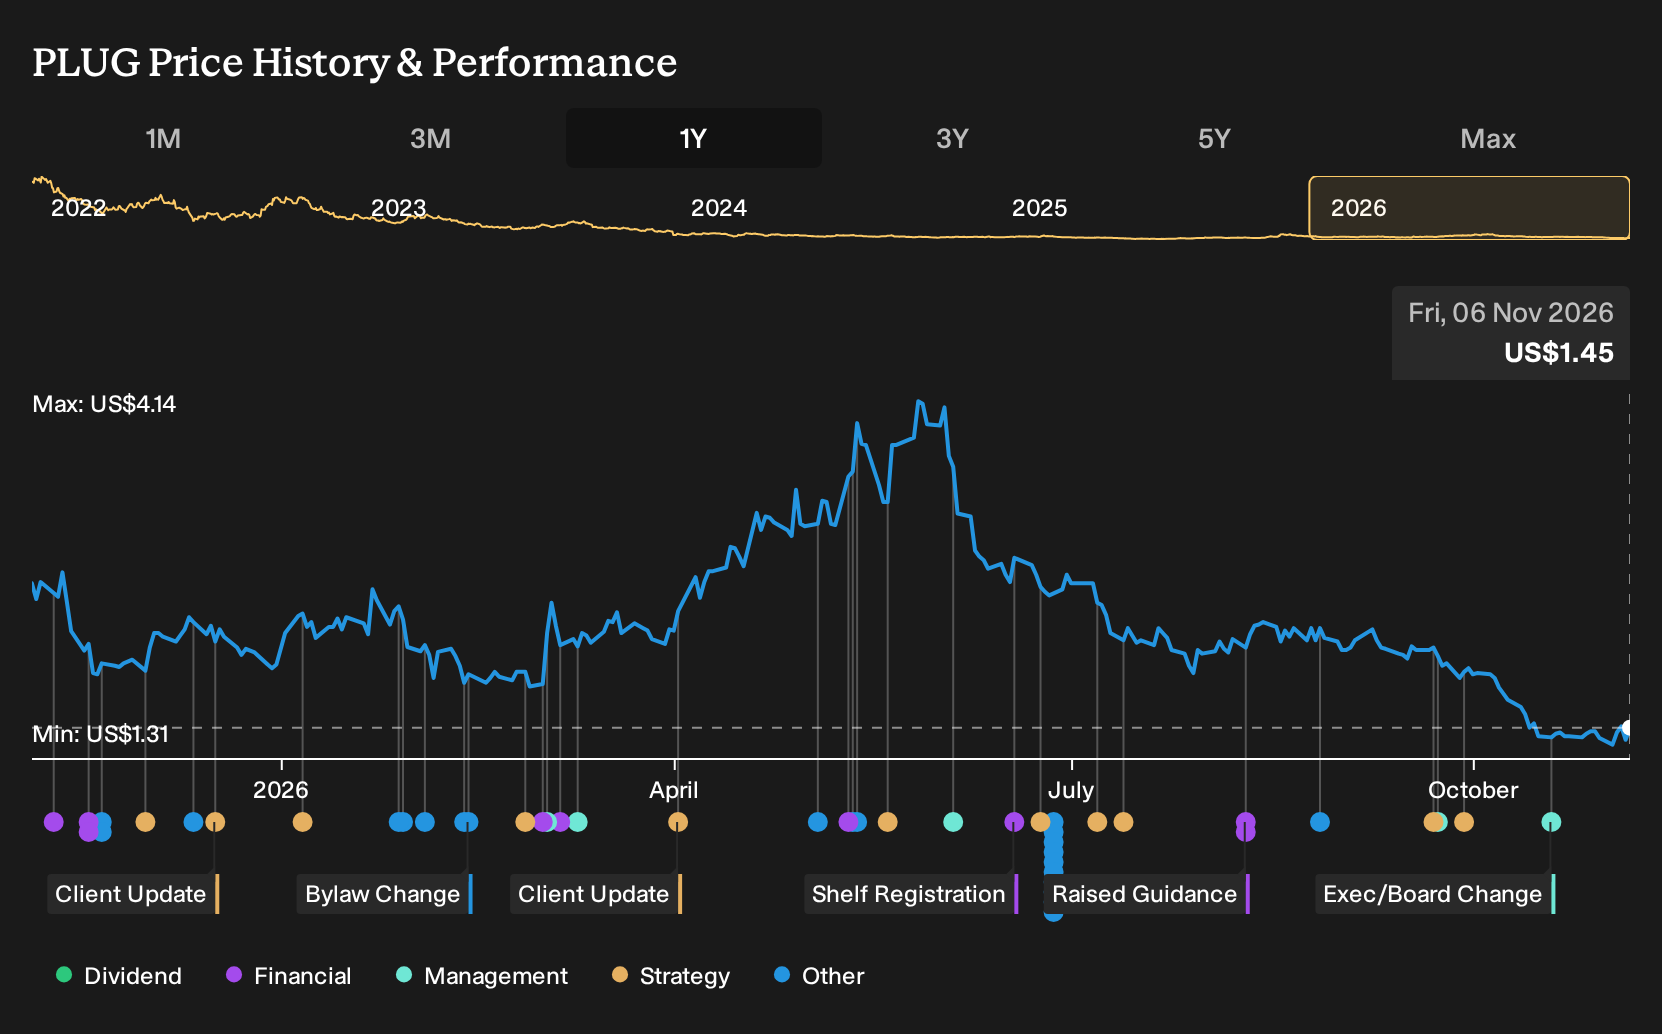
Plug Power reported improving quarterly revenue and a less severe net margin loss, yet shareholders saw a very different outcome on their statements. Investors who held Plug Power over the past year are down 45.3%, including dividends. If you had been weighing a position in early November 2025, you would have seen both bullish and cautious analyst cases on record. The real question is which parts of the story at that time indicated that business progress might not translate into a positive return.
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
Plug Power is not the only name tied to this theme. Zero in on 42 power grid technology and infrastructure stocks and compare how each one is priced.
The Two Plug Power Stories Investors Had To Weigh
The shares cost US$2.51 at the start of the period, and Plug Power sat between two very different but plausible Narratives.
On the optimistic side, the bullish case put Fair Value at US$4.23. That view leaned on an assumed 29.2% annual revenue growth rate and a future profit margin moving to 10.2% within a 3 year window.
The cautious Narrative saw Fair Value at US$2.08. That thesis still used a 10.2% future margin but paired it with liquidity worries and reliance on large projects that might never reach final investment decision.
What The Plug Power Evidence Actually Tested
Plug Power’s Q2 2026 update gave the bullish side fresh support on revenue and efficiency. Total revenue moved to US$178.3 million from US$173.97 million, while the net loss narrowed from US$227.1 million to US$188.2 million and net margin improved from 130.5% negative to 105.6% negative. Profitability was still not reached, so the evidence cut both ways.
The hinge assumption here was not demand; it was the path to sustainable earnings. For any similar stock, check whether improving sales and margin trends are actually bringing losses closer to breakeven on a net basis, rather than just lifting guidance headlines.
What Plug Power's Price Now Demands You Believe
Plug Power trades at US$1.45 today, and the selected bullish Narrative argues that Fair Value sits above that level. The view leans on policy support, cost resets and project pipelines rather than simply assuming sentiment will repair a share price that fell 45.3% over the past year.
On this reading, a buyer is effectively assuming that Plug Power can keep Project Quantum Leap on track so that cost cuts, service reliability and an asset light model turn into steadier gross margins and lower cash burn.
"Key Takeaways: Analysts expect Plug Power to keep converting its material handling base, electrolyzer funnel and cost actions into a more durable, margin-supportive revenue mix over time. The main things that have to go right are continued execution on Project Quantum Leap, improved service reliability and progress on the asset-light shift so that gross margins and cash burn can improve as the business scales."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
How Could You Get There Earlier?
The next headline does not have to be where your research begins. Go straight to the companies and see whether a contrarian opportunity could be taking shape.
- Company 1 - 41% below our estimate - serves contractors racing to expand hyperscale data center capacity and related infrastructure.
- Company 2 - 15% below our estimate - connects power and data equipment that supports new utility and data center projects.
- Company 3 - 16% below our estimate - scales franchised teahouses while growing fee based supply chain and technology support services.
That is three of the list. See all 39 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com