


Rising interest rates from the Bank of England are squeezing mortgages and loans, so a lot of investors are rethinking how much they are willing to pay for growth stories. That pressure can push solid British tech stocks into bargain territory. This article looks at three attractively priced technology picks from a specialist screener, explaining why each could appeal if you are hunting for quality at a discount.
The three stocks highlighted below are just a sample from the idea. The full screen surfaced 16 more tech companies with equally compelling stories that are not covered here. To go beyond this short list, identify and analyze your own high-conviction opportunities directly with the Undervalued Tech screener.
Computacenter (LSE:CCC)
Overview: Computacenter helps large corporate and public sector clients source hardware, migrate to multi cloud setups, and run managed data and AI platforms.
Operations: The business reports £12.1b from Computer Services, serving customers across the UK, Germany, Western Europe, the United States and wider international markets.
Market Cap: £4.8b
Computacenter gives you exposure to enterprise cloud migration and managed data and AI platforms while trading in an Undervalued Tech screener at around 23.6x P/E and at a discount to estimated future cash flows. Earnings growth forecasts and high returns on equity both depend on how far recurring, higher margin services can shift the mix away from lower margin hardware, and on how one unseen pressure plays out.
That mix shift question sits at the centre of the Computacenter story, so go straight to the DCF valuation analysis for Computacenter to see how the hardware to services balance could be mispriced.
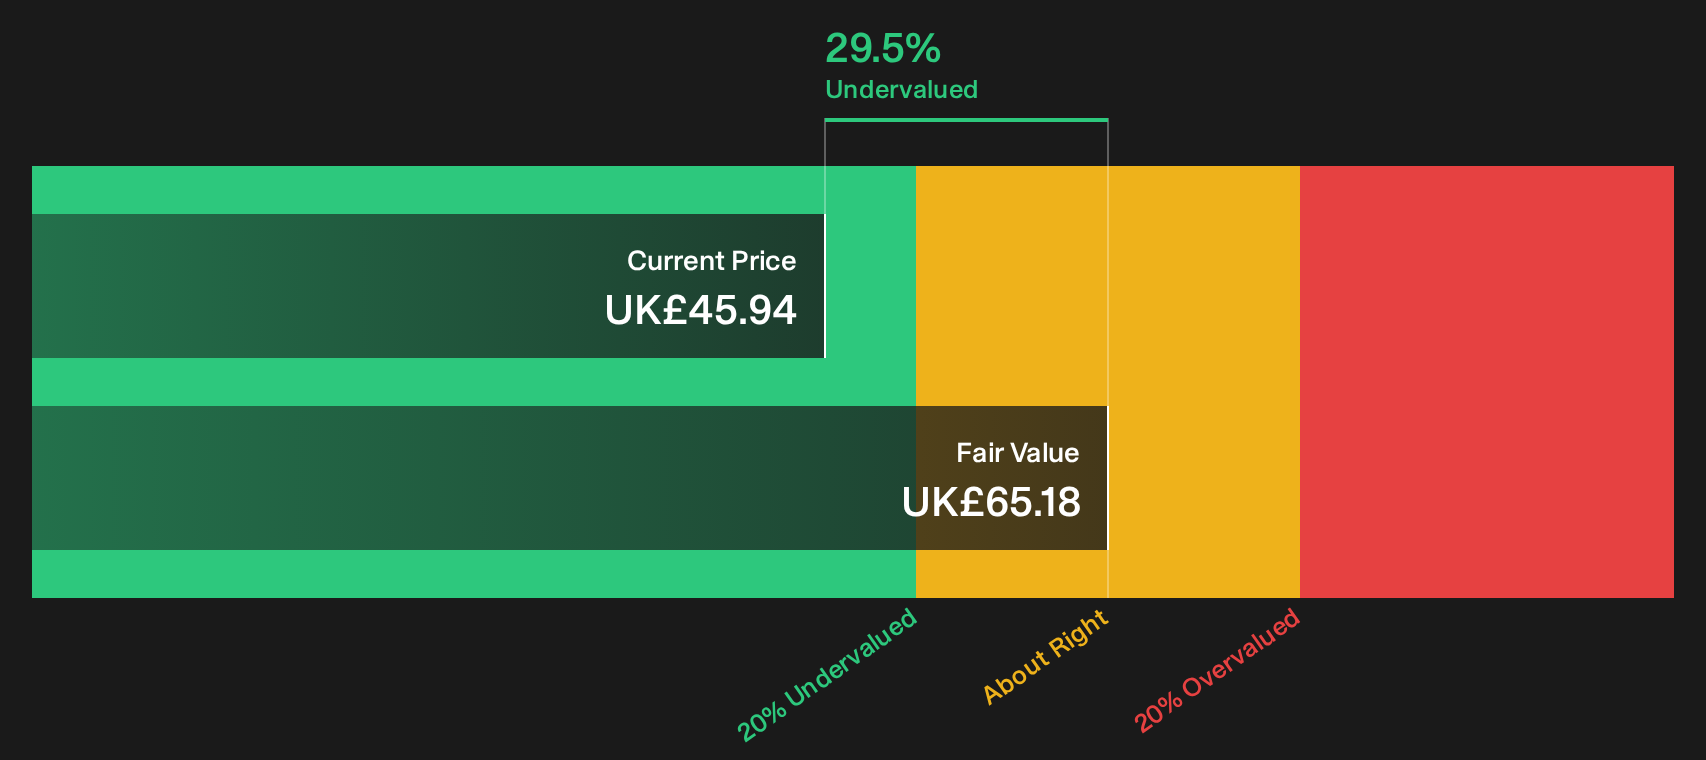
Bytes Technology Group (LSE:BYIT)
Overview: Bytes Technology Group sells software, cloud licenses, security and AI services that generate recurring revenue alongside a broader hardware and consulting business.
Operations: The group reports £240.8 million from its IT Solutions Provider arm, with most revenue coming from the United Kingdom and smaller contributions from Europe and the Rest of World.
Market Cap: £1.0b
Bytes Technology Group matters for this Undervalued Tech screen because its cloud and SaaS licensing engine turns AI, security and digital workspace demand into recurring cash flow rather than one off projects.
"Although services gross profit rose 38% with around two thirds of that now coming from recurring managed work, the much slower 2.5% gross profit growth compared with 11.5% gross invoiced income and a 5.6% fall in operating profit suggest that higher margin services may not be scaling fast enough to counter weaker reseller economics."
What happens if that quiet shift in where profits are earned accelerates faster than the reseller margin squeeze investors currently focus on?
If that shift is already starting, read the full narrative for Bytes Technology Group to see how reseller pressure, accelerating services and valuation could be decoupling in your favour.

Softcat (LSE:SCT)
Overview: Softcat is a UK IT reseller and infrastructure partner that designs and manages hybrid cloud, data centre and AI enabled systems for organisations.
Operations: Softcat generates £2.0b of revenue from value added IT reselling and infrastructure solutions, almost entirely from customers in the United Kingdom.
Market Cap: £3.4b
Softcat matters for an Undervalued Tech screen because its hybrid infrastructure, cloud and AI enablement work turns broad digital transformation demand into concrete projects and recurring services.
"Expansion into the US through the planned GDT acquisition, with GDT forecast to contribute about US$240m gross profit and US$80m adjusted EBITDA in calendar 2026, could broaden Softcat’s revenue base and support earnings growth as the combined group gains more exposure to multinational customers."
What really moves the needle is how one quiet shift in where the profit pool comes from reshapes the quality of that growth.
If that quiet profit shift is what really counts, read the full narrative for Softcat to see how Softcat’s US move could accelerate or mask the next phase.

Seeking Fresh Alternatives Before They Fly
Markets move fast and the strongest ideas rarely stay under the radar for long. Track fresh momentum, spot quiet breakouts and identify quality while it matters, then act based on your own research and judgment.
- Identify companies with resilient cash generation potential by scanning the curated 15 high quality undervalued stocks while pricing dislocations may still be present.
- Explore companies connected to electricity, data and electrification by working through a hand picked set of 42 power grid technology and infrastructure stocks before sentiment changes.
- Review businesses involved in automation by examining the carefully filtered 90 robotics and automation stocks while adoption stories may still be underappreciated.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com