


- Premium Brands Holdings reported Q3 2026 sales of C$2,378.9m and net income of C$38.3m, compared with a loss a year earlier, alongside record nine-month results.
- The group secured nearly C$170m of new programs with large U.S. retail and foodservice customers, indicating heavier use of its expanded production capacity.
- We will examine how Premium Brands Holdings' investment narrative is influenced by stronger profitability and new U.S. customer wins.
Scan beyond Premium Brands Holdings and compare this earnings momentum with our hand picked list of 6 high quality undervalued stocks, which also pair rising profitability with disciplined balance sheets.
Premium Brands Holdings Investment Narrative Recap
To own Premium Brands Holdings, you need to be comfortable with a story built around filling sizeable new production capacity with profitable volume, mainly in the U.S., while converting more earnings into cash to chip away at debt. The latest quarter helps that case, with higher sales, a move back to positive net income, and record nine month results.
The near term swing factor is still execution on new program ramp ups and facility utilization, which has been lumpy in the past. That same lumpiness remains the biggest risk, together with interest costs on a leveraged balance sheet. Q3 results look supportive, but do not remove those pressure points.
The most relevant update here is the Q3 2026 earnings release on November 5, which put concrete numbers behind Premium Brands Holdings' operating progress. Sales for the quarter were C$2,378.9m, up from C$1,949.8m a year earlier, and the group reported net income of C$38.3m versus a small loss in the prior year period.
Over the first nine months, sales reached C$6,805.6m with net income of C$112.1m. Those figures sit alongside management comments that Premium Brands Holdings is on track toward its multi year sales and EBITDA ambitions. For you, the key question is whether this pace, plus roughly C$170m of new U.S. business wins, is enough to offset the ongoing risks around demand shifts, program timing, and leverage.
Premium Brands Holdings' narrative assumes revenues of CA$10.9b and earnings of CA$696.3m by 2029, built on analysts’ projected 9.1% yearly revenue growth and an earnings increase of about CA$665m from CA$30.9m today.
Uncover why Premium Brands Holdings' fair value points to a 46% potential upside to its current price that could narrow quickly if sentiment shifts.
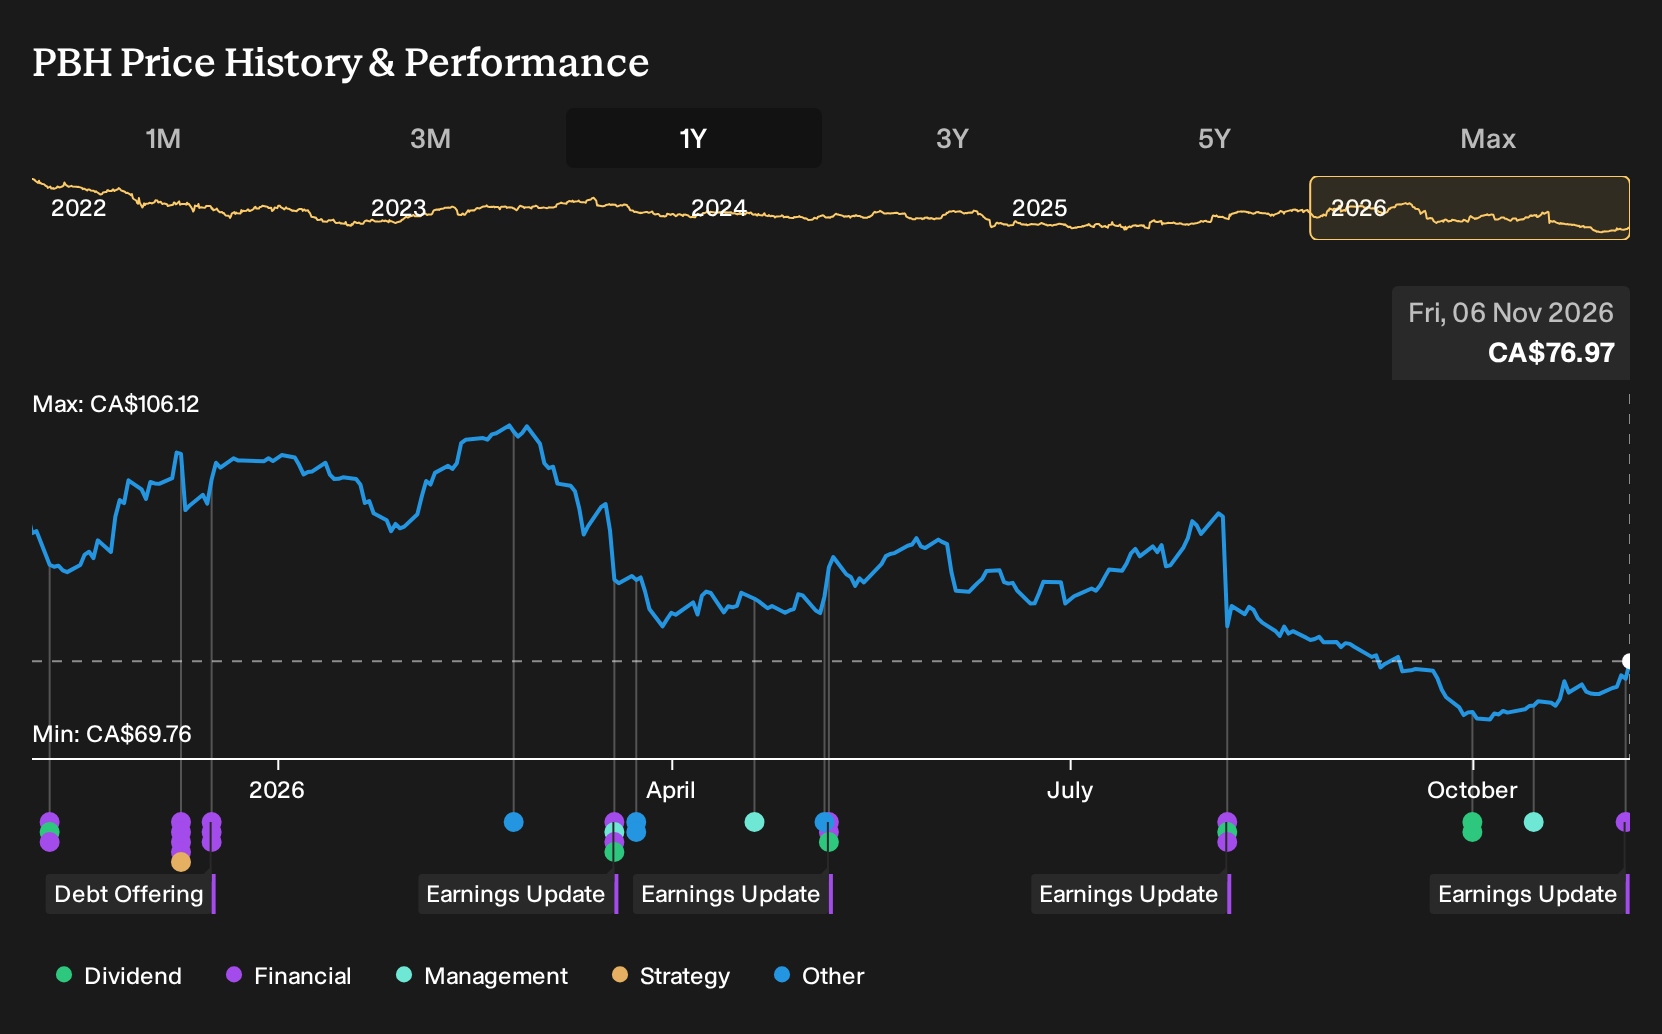
Exploring Other Perspectives
One alternate view on Premium Brands Holdings focuses on underused capacity as the key risk. Before this Q3 report, the most cautious analysts were only baking in about 5.2% yearly revenue growth to around C$9.8b by 2029 and earnings of roughly C$729.2m. That is a far more guarded story. Use this new earnings beat as a prompt to compare those pessimistic assumptions with your own, and to explore how different the future might look if execution or demand surprises either way.
Explore 4 other Premium Brands Holdings fair value estimates, including one that suggests it could be worth just CA$94.00.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your Premium Brands Holdings research is our analysis highlighting 4 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Premium Brands Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Premium Brands Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Premium Brands Holdings?
Once you have formed a view on Premium Brands Holdings, it can help to line it up against other opportunities that match your risk tolerance, income needs, and balance sheet comfort level. The Simply Wall St Screener gives you a quick way to surface stocks that fit different profiles without getting lost in noise.
- If you want potential mispricing combined with quality traits, focus on companies that appear underappreciated on fundamentals and start with our set of 6 high quality undervalued stocks.
- If capital preservation and steadier profiles matter more to you than chasing every rally, filter for sturdier balance sheets and head to this 9 resilient stocks with low risk scores.
- If you care most about strong finances before anything else, zero in on businesses with robust leverage and liquidity metrics using this list of solid balance sheet and fundamentals (5 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com