


- Banca Monte dei Paschi di Siena reported net income of €542.9 million for Q3 2026 and €1,656.7 million for the first nine months, both higher than the same periods in 2025.
- The shareholder meeting in October 2026 expanded the board by confirming previously co opted directors, adding governance continuity alongside stronger earnings.
- We will now look at how Banca Monte dei Paschi di Siena’s higher quarterly net income could influence the existing investment narrative.
Compare Banca Monte dei Paschi di Siena’s latest earnings momentum with a hand picked 220 high quality undervalued stocks that also pairs stronger results with balance sheet support.
Banca Monte dei Paschi di Siena Investment Narrative Recap
Banca Monte dei Paschi di Siena appeals to shareholders who buy into a simple idea. The bank needs to keep translating earlier restructuring work into solid earnings while using its strong capital position to support future consolidation and fee growth. The latest quarterly net income of €542.9 million and €1,656.7 million for nine months support that thesis but do not radically change it.
The short term swing factor is still execution on integrations and potential exchange offers around Banco BPM and Banca Generali, where hoped for synergies are large. The main operational risk remains pressure from high bad loans, a low allowance for those exposures and a dividend that consensus already flags as not well covered.
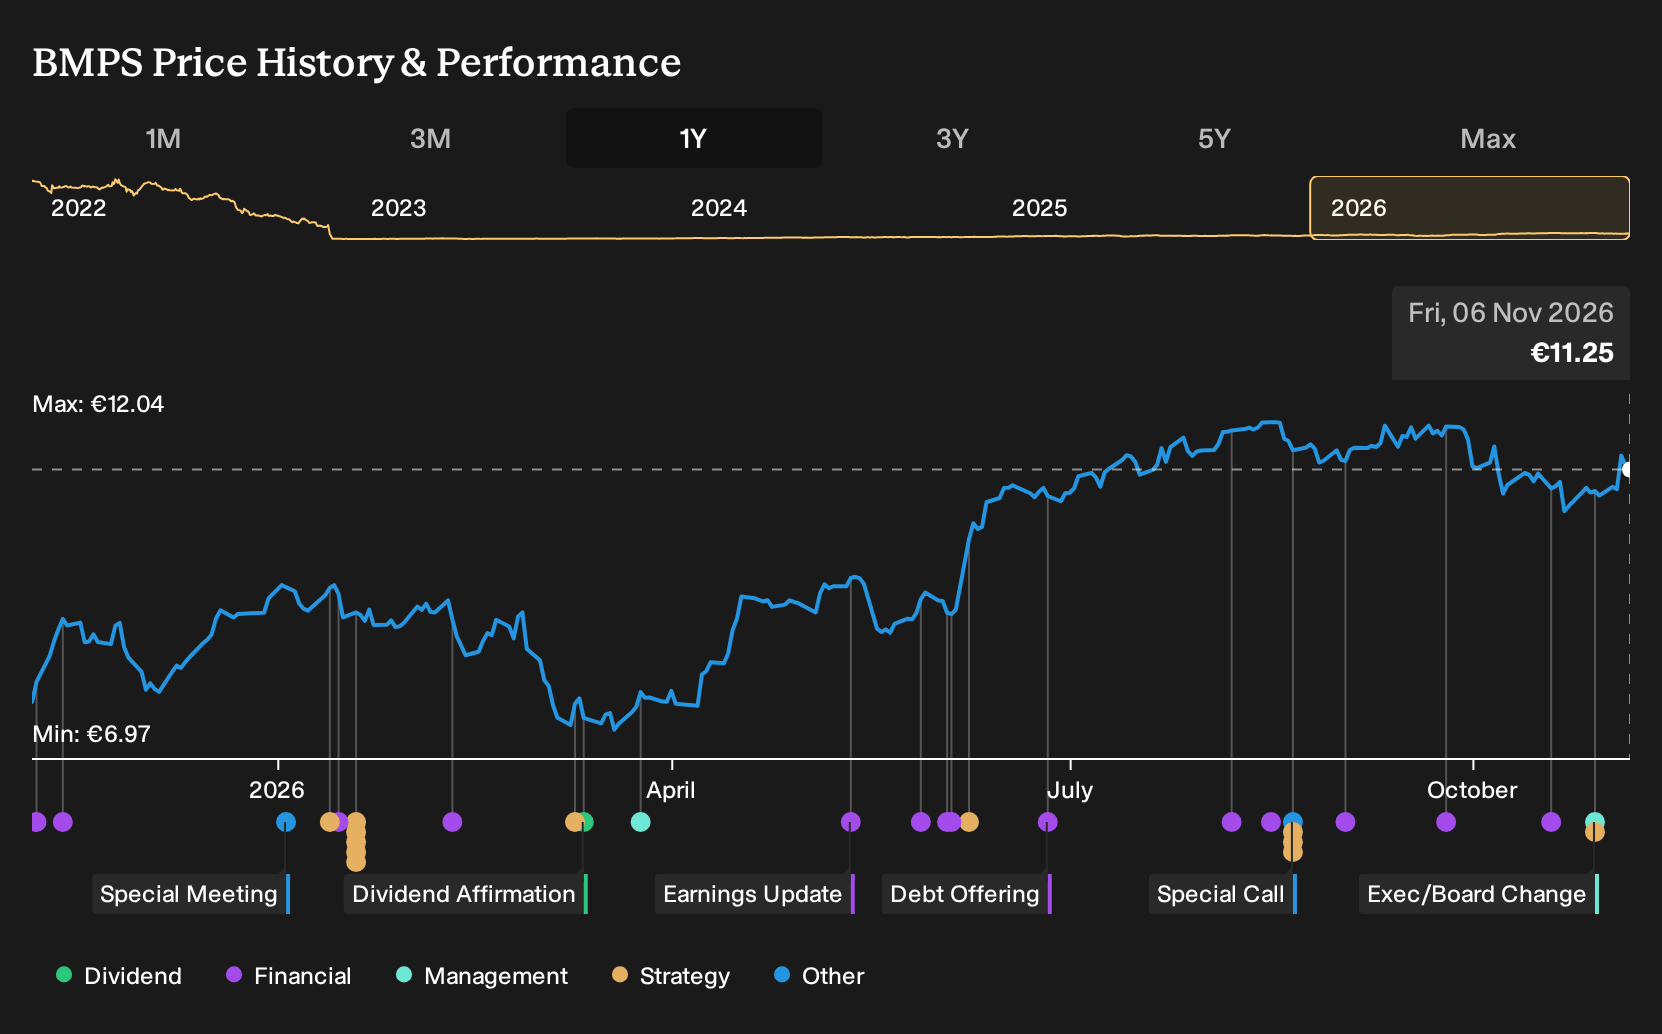
The earnings announcement for the third quarter of 2026 is the clearest update for you to focus on. It shows net income of €542.9 million for the period and €1,656.7 million for the first nine months, above the same stages in 2025. That keeps attention on how well Banca Monte dei Paschi di Siena can fund its wider consolidation plan from internal profit generation.
These results sit alongside existing catalysts around Mediobanca integration and the proposed deals for Banco BPM and Banca Generali, where analysts have pencilled in €700 million of expected synergies from Mediobanca and €1.8 billion from the exchange offers. Stronger profit today gives more headroom to absorb execution costs and any delay, although it does not remove the risk that shareholder opposition limits those transactions or keeps returns closer to current levels.
Banca Monte dei Paschi di Siena's current analyst narrative points to €9.9 billion in revenue and €3.2 billion in earnings by 2029, built on 20.7% yearly revenue growth and an earnings increase of about €0.3 billion from €2.9 billion today.
Discover how Banca Monte dei Paschi di Siena's fair value indicates a 5% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternative view puts much more weight on integration strain. Those bearish analysts were only baking in about €9.4b of 2029 revenue and €3.1b of earnings for Banca Monte dei Paschi di Siena before this Q3 beat. That is a more cautious story. Use today’s numbers as a trigger to compare these conflicting forecasts yourself.
Explore 4 other Banca Monte dei Paschi di Siena fair value estimates, including one that suggests as much as 17% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your Banca Monte dei Paschi di Siena research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Banca Monte dei Paschi di Siena. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Banca Monte dei Paschi di Siena's overall financial health at a glance.
Looking for more investment ideas beyond Banca Monte dei Paschi di Siena?
If Banca Monte dei Paschi di Siena has sharpened your thinking but you want a broader watchlist, use the Simply Wall St Screener to find other opportunities that match your preferred mix of quality, value and risk.
- For investors who want current income backed by stronger balance sheets, consider screened high yielders through 230 dividend fortresses that already clear a 5% threshold.
- If capital preservation and steadier financial profiles appeal to you, focus on companies filtered by our 210 resilient stocks with low risk scores that score better on resilience and downside protection.
- When you want to widen your search beyond well covered blue chips, scan for underfollowed ideas using a 583 high quality undiscovered gems that still pair solid fundamentals with cleaner accounts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com