


- BorgWarner reported third quarter 2026 sales of US$3,487 million and net income of US$221 million, updated 2026 sales guidance to a range of US$14.0 billion to US$14.2 billion, and announced multiple new awards across aluminum-wire eMotors, high-voltage traction inverters and long term engine control module supply.
- The aluminum-wire eMotor contract with a major Chinese OEM, which targets over 60% weight reduction and over 80% cost savings versus comparable copper motors, highlights how BorgWarner is working to reshape its hybrid and electric product economics.
- We will explore how BorgWarner's investment narrative is influenced by these new electrification awards, particularly the aluminum-wire eMotor win.
BorgWarner Investment Narrative Recap
For BorgWarner, the big belief is that the mix shift from combustion toward hybrid, electric and industrial power can offset pressure on legacy turbo and engine products. The slightly lower top end of 2026 sales guidance, now set at US$14.0b to US$14.2b, does not radically change that story, but it keeps execution under the microscope.
The most immediate swing factor is whether new contract wins move into production smoothly while the battery unit continues to shrink without fresh shocks to revenue. The key risk is still that internal combustion exposure and a volatile battery wind down drag on reported growth and blunt margin progress.
The aluminum wire eMotor award with the long standing Chinese customer looks most relevant here. It puts new technology into the hybrid portfolio, with over 60% weight reduction and more than 80% cost savings versus comparable copper motors while maintaining peak torque and power. That matters if BorgWarner is trying to protect content per vehicle as powertrains evolve.
This contract, scheduled to start production in the fourth quarter of 2026, lines up with the broader catalyst of booked program wins across eMotors and inverters feeding into future revenue. Execution risk remains around ramp timing and profitability, especially as battery sales decline and combustion programs face regulatory pressure, but this kind of award directly supports the electrification thesis.
BorgWarner's current analyst blueprint points to revenues of US$16.8b and earnings of US$1.1b by 2029, based on a projected 5.7% yearly revenue growth profile and an earnings increase of about US$622m from US$478.0m today.
Uncover how BorgWarner's fair value indicates a 62% potential upside to its current price, a gap that could narrow quickly if sentiment shifts.
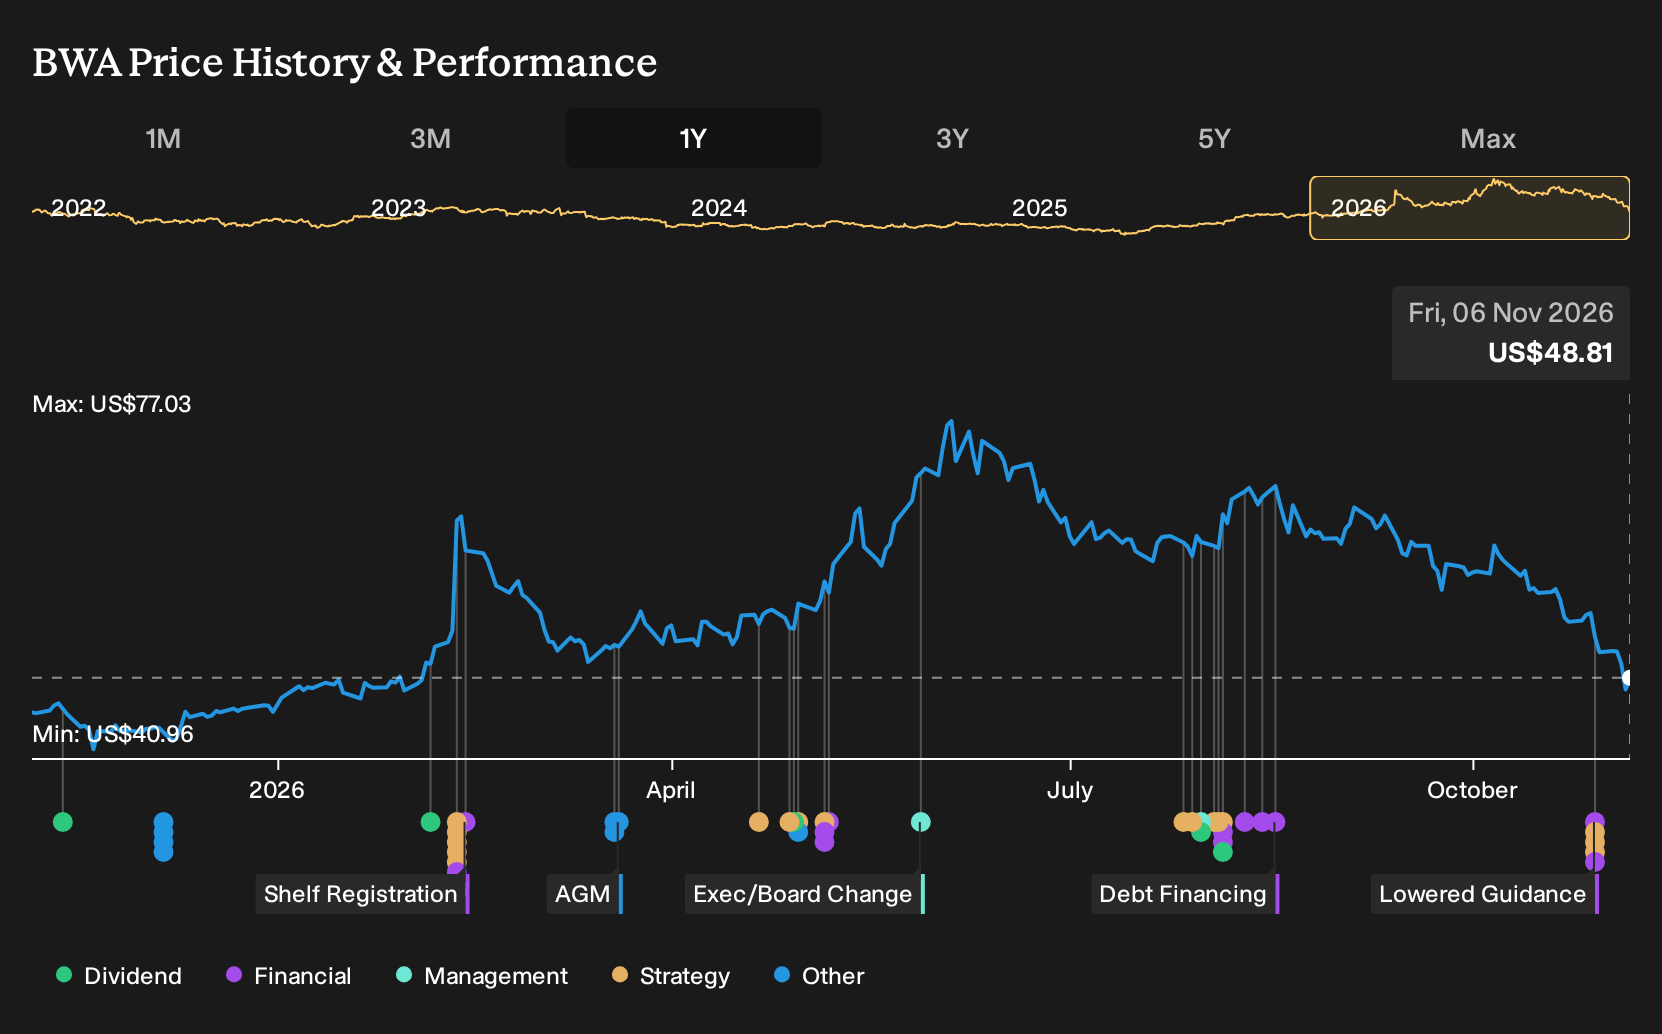
Exploring Other Perspectives
Some bullish analysts treat BorgWarner’s data center and industrial power push as the real catalyst. Before this guidance tweak and eMotor win, they were modeling revenue at about US$17.0b and earnings near US$1.4b by 2029. That is far above consensus, and it shows how widely opinions differ and may still shift as this news settles in.
Explore 3 other BorgWarner fair value estimates, including one that suggests potential upside of up to 112% from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis carefully.
- A great starting point for your BorgWarner research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for BorgWarner. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate BorgWarner's overall financial health at a glance.
Looking for more BorgWarner-like investment ideas?
If the BorgWarner story has you thinking about where else electrification, balance sheet strength or steadier cash flows could matter, the Simply Wall St Screener can help you widen the search without getting lost in endless tickers.
- For investors who care most about stability first and upside second, consider screening for 29 resilient stocks with low risk scores that keep risk scores in check while still leaving room for returns.
- If steady income matters more to you than price swings, zero in on companies with robust payouts using a curated set of 8 dividend fortresses that aim to combine higher yields with staying power.
- When you want to get ahead of the crowd, focus on quality first and publicity last by scanning through a pool of 19 high quality undiscovered gems that pair solid fundamentals with lighter market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com