


Akamai Technologies (AKAM) has put hard numbers around its next few years, pairing third quarter results with fresh forecasts for 2026 through 2028 that spell out expected revenue ranges and timing shifts.
Akamai Technologies’ earnings update and multiyear AI infrastructure deals landed against a sharp reset in sentiment, with the 30-day share price return down 20.57% and the 90-day move down 24.83%. However, the 1-day jump of 6.74% on the latest close hints at investors reassessing execution risk after clarified guidance and improved contract visibility. Over a longer stretch, total shareholder return is down 0.78% over one year and roughly 25% over three and five years, which signals fading long-term momentum despite headline-grabbing cloud and AI commitments.
Scan how other AI infrastructure and security leaders are priced and positioned by jumping into a curated set of 52 AI infrastructure stocks, while Akamai Technologies reshapes expectations with its Anthropic deal and multiyear guidance reset.
Bulls point to Akamai Technologies’ AI contracts and revenue outlook, while bears focus on the share price slide and earnings pressure. Which side does the current valuation math lean toward as the dust settles on this reset?
Most Popular Narrative: 46% Undervalued
Akamai Technologies closed at $83.09, while the most followed narrative pegs fair value at about $154.96. The gap the market is debating is wide and firmly tied to how its AI infrastructure build out plays through the income statement and cash flows.
Active capital deployment toward cloud infrastructure growth, including an expected 2026 CapEx level of about 40% of revenue and roughly US$5.5b of planned Anthropic related CapEx supported by zero coupon convertible debt financing and new power sourcing arrangements, is intended to build a 95 to 105 megawatt AI infrastructure portfolio. Management expects this portfolio to deliver about US$22m in annual revenue per megawatt and support future cash gross margins in the mid 60s to mid 70s range.
See why 38 investors see Akamai Technologies as 46% undervalued.
Result: Fair Value of $154.96 (UNDERVALUED)
Still, the narrative cracks if Akamai Technologies fails to earn acceptable returns on the US$5.5b Anthropic CapEx, or if core delivery declines outpace security and cloud momentum.
Find out about the key risks to this Akamai Technologies narrative.
Another View: What Akamai Technologies Looks Like On P/E
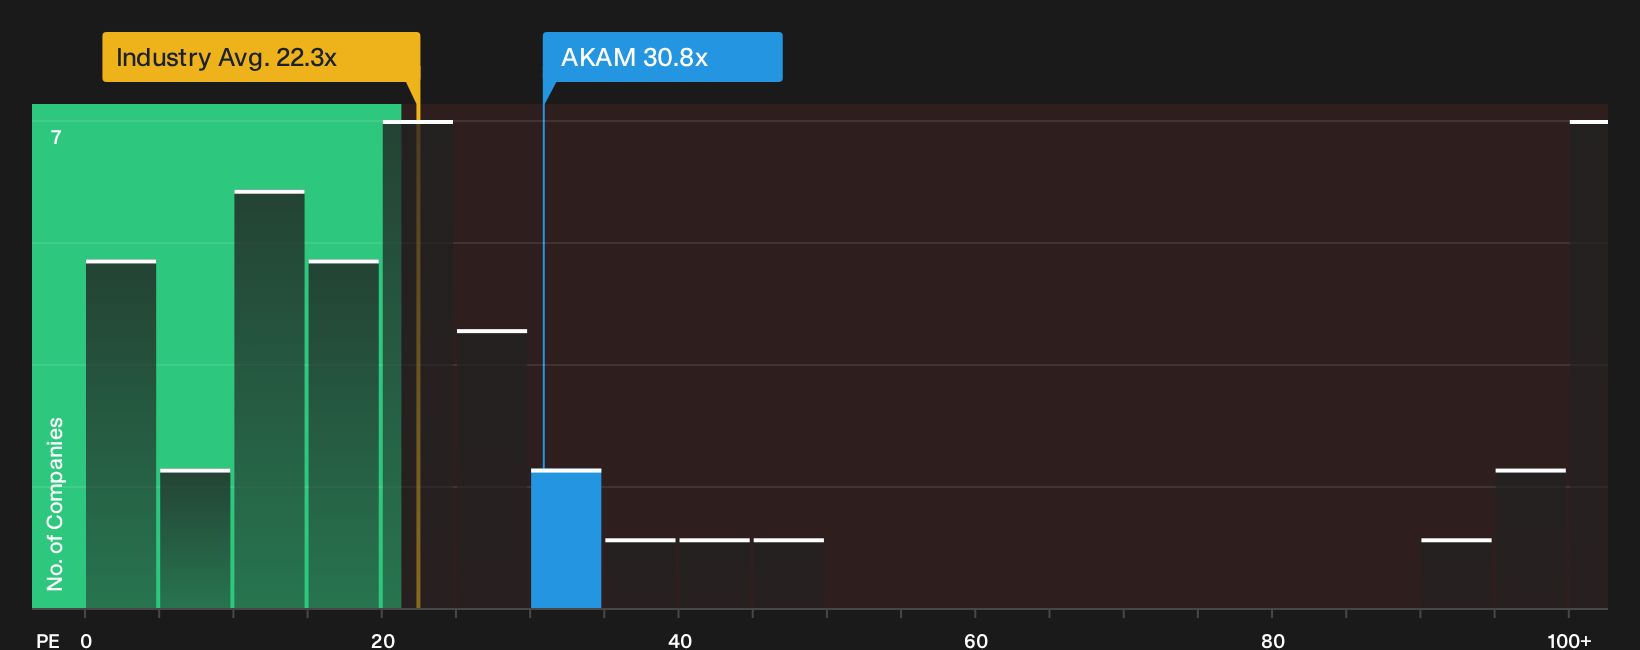
The narrative fair value of $154.96 presents Akamai Technologies as strongly undervalued. The P/E picture is less straightforward. At 30.8x earnings, AKAM trades richer than the US IT sector on 22.3x, yet cheaper than its peer group on 38.7x and below a fair ratio of 37.5x that the market could move toward. For investors, that mix of premium versus the wider industry and discount versus closer peers raises a simple question: Is this pricing a margin of safety or a signal that expectations already bake in a lot of AI and security optimism?
See what the numbers say about this price in our valuation breakdown, including how that earnings multiple compares across peers and the fair ratio See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Akamai Technologies is split, with some investors focused on upside potential and others fixated on the risks highlighted in recent updates. Move quickly, review the underlying data for yourself, and weigh both the 2 key rewards and 1 important warning sign
Looking for more Akamai Technologies sized investment ideas?
Do not park all your attention on a single ticker. Put fresh ideas on your radar with a quick scan through high conviction stock lists built from hard data.
- Target potential bargains by reviewing a curated spread of companies on the 39 high quality undervalued stocks and see which valuations appear disconnected from underlying fundamentals.
- Focus on resilience by checking the 29 resilient stocks with low risk scores and spot businesses that pair lower risk scores with more robust financial profiles.
- Hunt for future standouts by scanning the 19 high quality undiscovered gems and catch strong fundamentals before they land on everyone else's watchlist.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com