


Saputo stock: what the latest earnings and dividend decision signal
Saputo (TSX:SAP) just paired a fresh quarterly earnings update with a reaffirmed CA$0.21 per share dividend, giving investors new numbers to weigh against the stock’s recent share price performance.
Recent trading suggests investors are responding to that earnings and dividend update. The share price has climbed 5.69% in the last day and delivered a 14.23% 1 month share price return. The 1 year total shareholder return of 26.89% points to momentum that has been building rather than fading.
Scan how Saputo’s latest earnings and dividend move compares with other income-focused opportunities by reviewing our hand-picked list of 3 dividend fortresses in the market right now.
Saputo now trades only modestly below the average analyst target, even after a sharp run on upbeat earnings and steady dividends. Is that small discount a genuine opportunity, or a signal that caution is warranted?
Most Popular Saputo Narrative: 5.8% Undervalued
Saputo’s most followed narrative pegs fair value at CA$46.70, a touch above the latest CA$43.99 close, which puts the recent price move in context rather than rewriting the story.
A stronger balance sheet, with net debt to EBITDA around 1.4x and a target of 2.25x, together with a 5% dividend increase and an expanded share repurchase program of up to about 24 million shares, allows Saputo to step up capital returns while still funding growth projects. These actions can influence earnings per share and support valuation multiples.
See why 28 investors see Saputo as 6% undervalued.
Result: Fair Value of CA$46.70 (UNDERVALUED)
Still, the Saputo thesis relies on higher margin products to offset risks such as Canadian whey restrictions and rising input costs that could pressure earnings and cash generation.
Find out about the key risks to this Saputo narrative.
Another view on Saputo’s valuation
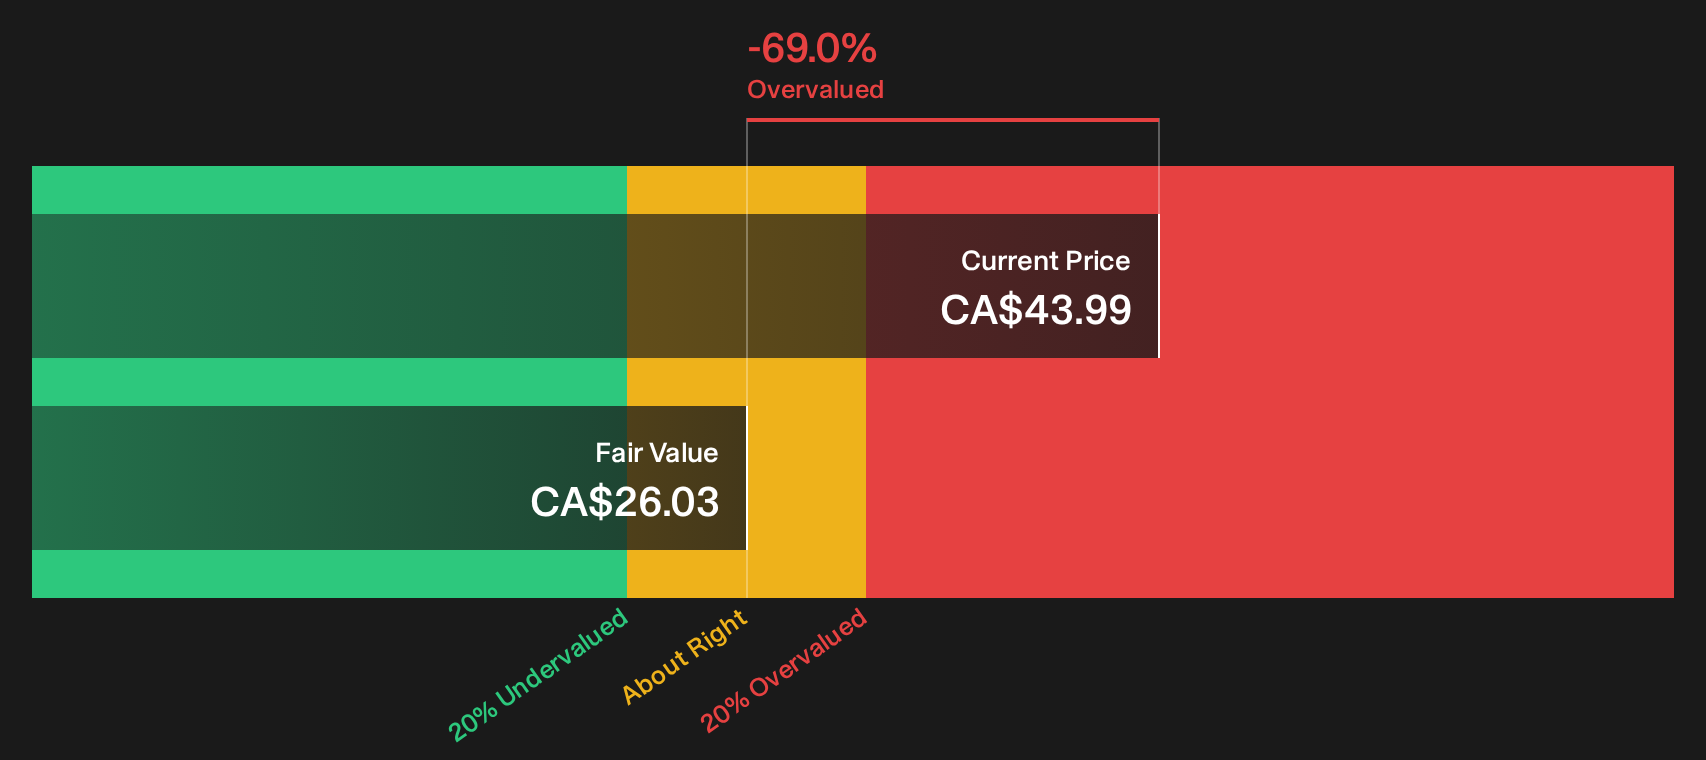
The narrative pegs Saputo as about 5.8% undervalued at a fair value of CA$46.70, slightly above the current CA$43.99 price. Our DCF model points in a very different direction. On that approach, the share price of CA$43.99 sits above an estimated future cash flow value of CA$26.03, which screens as expensive.
Two tools, two answers. The story then becomes which set of assumptions you find more realistic, and how much valuation risk you are comfortable carrying if the cash flow view is closer to the mark. Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Saputo for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 6 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the sentiment in this Saputo update feels mixed, that is the point. Momentum and valuation never line up perfectly. Take a closer look at the upside signals and risks for yourself by checking the 3 key rewards.
Looking for more Saputo sized investment ideas?
You have seen what Saputo looks like today. Do not stop there. The next move often comes from a stock you have not checked yet.
- Hunt for value that combines quality and a potential price gap by scanning our hand picked set of 6 high quality undervalued stocks.
- Strengthen your core holdings with companies that pair resilient finances and dependable metrics using the list of solid balance sheet and fundamentals (5 results).
- Get ahead of the crowd by spotting under the radar opportunities inside the 7 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com