


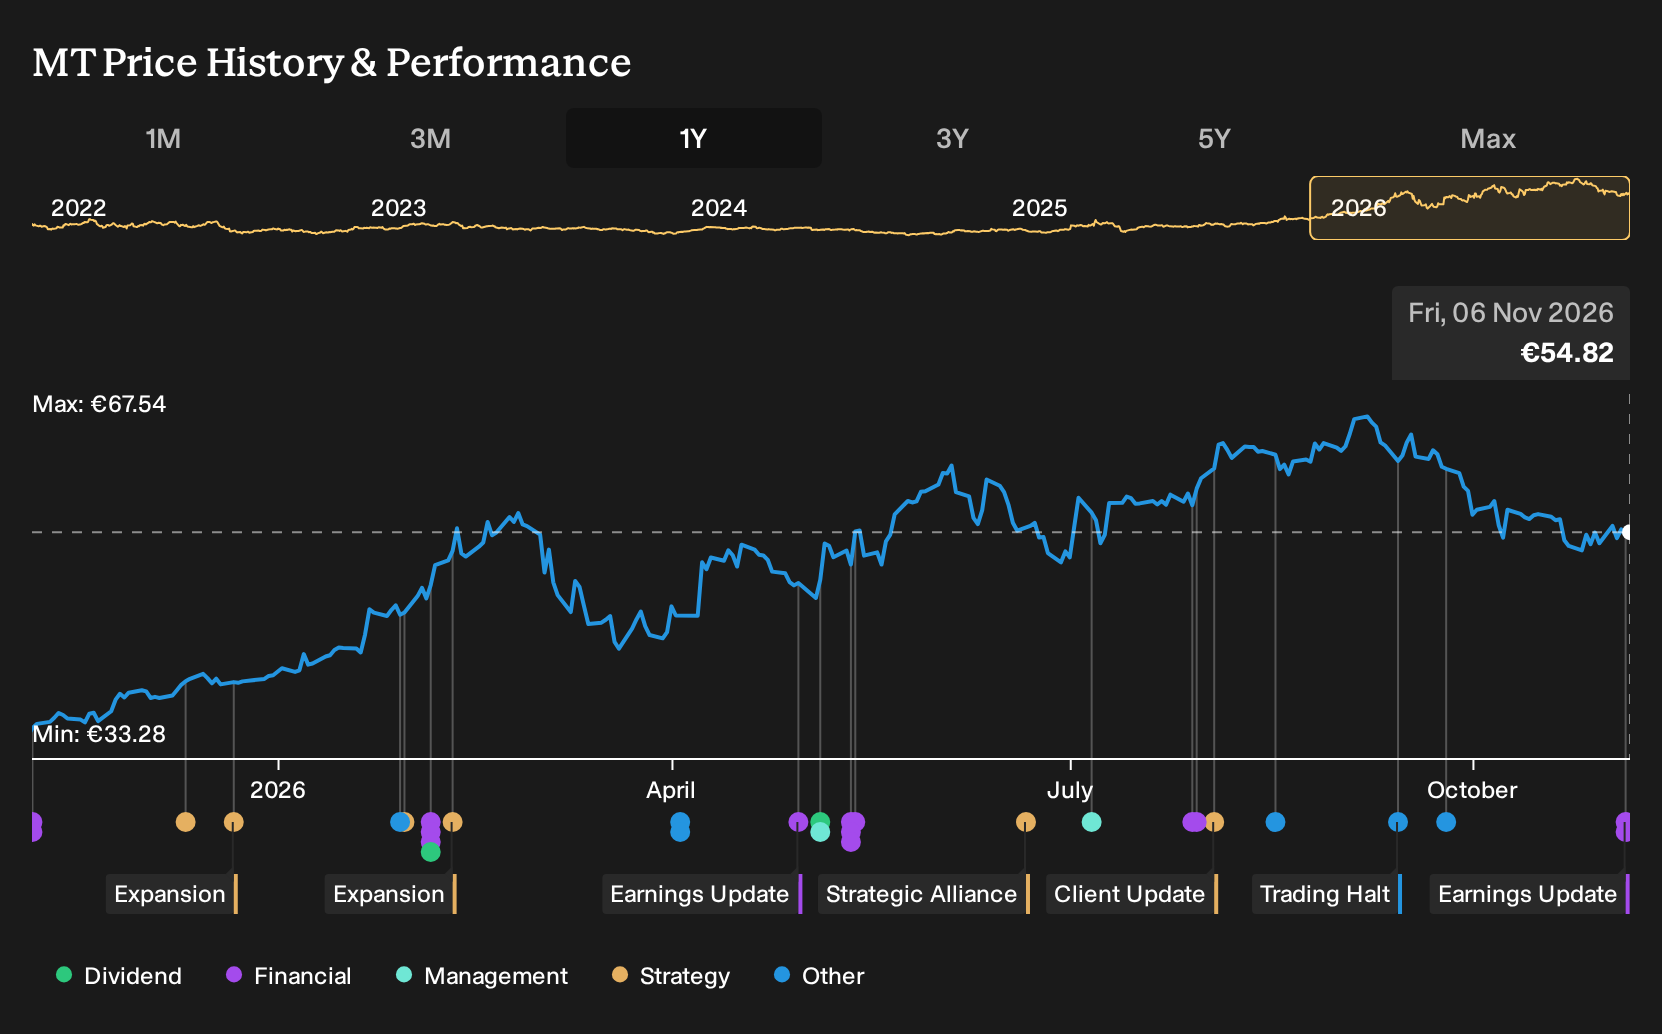
- ArcelorMittal reported Q3 2026 sales of US$16,466 million and a net loss of US$391 million, with basic loss per share of US$0.52 from continuing operations.
- Despite higher sales and slightly higher iron ore output, ArcelorMittal moved from profit to loss, highlighting pressure on profitability relative to volume performance.
- In the following sections, we examine how ArcelorMittal's investment narrative could be affected by this shift from net income to a quarterly loss.
See how other steel and materials stocks are trading under similar earnings pressure by reviewing our curated list of solid balance sheet and fundamentals (190 results) alongside ArcelorMittal.
ArcelorMittal Investment Narrative Recap
To own ArcelorMittal, you need to believe the heavy lifting in Europe, India and Liberia eventually translates into steadier earnings, even through choppy quarters. The recent Q3 2026 loss of US$391 million, despite higher sales, puts the focus squarely on execution. The near term catalyst is whether management can convert ongoing growth projects and decarbonization investments into cleaner, less volatile profitability.
The biggest near term risk sits in pressure on margins and one off items. Net profit margins of 1.6% for the last 12 months, down from 4.2% a year earlier, and a large one off loss of US$535 million leave less room for error if European reforms, Indian expansion or Liberia mining projects run into delays or regulatory issues.
The Q3 2026 earnings announcement is the key disclosure to focus on here. Sales reached US$16,466 million in the quarter and US$48,684 million for the first nine months, while net income for the nine month period was US$867 million compared with US$2,975 million a year earlier. That step down in profitability matters more for ArcelorMittal than the modest sales gap.
Production data in the same disclosure gives more texture to the story. Iron ore output for the quarter was 12.6 MT versus 12.1 MT a year ago, with crude steel production roughly stable but steel shipments lower. For catalysts around India, Liberia and low emission projects to play through, investors will likely watch how quickly shipments and mix improve relative to capacity and how any further operational disruptions, regulatory issues or Ukraine related impacts are contained.
What Analyst Assumptions Signal For ArcelorMittal
Consensus forecasts sketch out a very different version of ArcelorMittal from the one in the latest quarterly loss. Analysts are working with a revenue growth assumption of 6.7% a year over the next few years, rising profit margins and materially higher earnings by the end of the decade. The gap between those projections and the current profit trend is what you are really deciding on when you assess the stock today.
On earnings, the starting point in the analyst model is US$1.8b today. Forecast consensus points to US$5.7b of profit and US$7.92 in earnings per share by around 2029, with some more optimistic estimates going as high as US$9.3b. That implies earnings would need to increase by roughly US$3.9b from current levels for the central case to play out. These figures sit alongside an assumed lift in net margin from 2.9% to 7.5% over roughly three years, so the story is as much about pricing and mix as it is about raw volume.
Valuation work in the analyst report ties those profit numbers to a lower future P/E multiple. The modelling currently assumes ArcelorMittal would trade on about 12.6x those 2029 earnings, which is below the 25.2x P/E currently cited for both the stock and the wider GB metals and mining group. If that scenario held, the business would be generating higher earnings on a richer margin profile but with investors paying fewer euros for each dollar of profit than they do today.
The capital structure piece also matters for anyone thinking about per share outcomes. Analysts are baking in a modest 0.91% annual decline in the number of shares over the next three years, driven by ongoing buybacks. That kind of reduction is not dramatic on its own, yet when combined with the projected earnings step up it shapes a much more concentrated earnings base for remaining holders if the plan is delivered.
The discount rate assumptions round out the framework. The report uses a 7.85% rate to pull those longer dated cash flows back to today, with a slightly different 7.9% figure referenced in the price target discussion. Readers should treat those numbers as one possible hurdle for return expectations rather than a fact, then stress test whether a higher or lower required return meaningfully changes their view on ArcelorMittal’s current pricing.
ArcelorMittal's narrative projects US$76.3b revenue and US$5.7b earnings by 2029. This is built on 6.7% yearly revenue growth and an earnings increase of about US$3.9b from US$1.8b today.
Uncover how ArcelorMittal's fair value indicates a 27% potential upside to its current price before the discount closes.
Exploring Other Perspectives
One alternate view focuses on conflict risk around ArcelorMittal. The most bearish analysts were already working with slower revenue growth of about 4.5% a year and roughly US$5.5b of earnings by 2029 before this Q3 loss. That cohort effectively treats the stock as fairly priced, so this setback could prompt them to reassess. You can compare that more pessimistic outlook with the broader consensus and decide which perspective aligns more closely with your own expectations.
Explore 2 other ArcelorMittal fair value estimates, including one that suggests it could be worth just €69.59!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your ArcelorMittal research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for ArcelorMittal. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ArcelorMittal's overall financial health at a glance.
Looking For More Investment Ideas Beyond ArcelorMittal?
If ArcelorMittal has sharpened your thinking on risk, return and narrative, it can be useful to widen the lens and compare it with other opportunities. The Simply Wall St Screener helps you quickly filter the market so you can focus on businesses that fit your preferred balance of quality, income and resilience.
- For investors hunting for potential mispricings with strong fundamentals, scan a curated pool of 221 high quality undervalued stocks that may merit a closer look.
- If reliable income is your priority, use our income focused filter to zero in on 229 dividend fortresses that might suit a yield driven approach.
- For those who care most about resilience and downside protection, start with a 209 resilient stocks with low risk scores that score well on stability and risk metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com