


- Omnicom Group recently appointed Tom Schwenger as CEO of Omnicom Health's marketing business and was named a Leader in Forrester's global media management report, alongside fresh client wins and retained billings.
- The combination of industry recognition, new pharma and biotech focused leadership, and integration of Interpublic assets signals a push to scale Omnicom Group's AI enabled media and health marketing platform.
- We will now look at how Omnicom Group's Forrester leadership recognition could reshape its investment narrative for long term shareholders.
Scan how Omnicom Group's AI enabled media and health push compares to other potential breakouts in marketing and data driven platforms with our hand picked 36 high quality undervalued stocks.
Omnicom Group Investment Narrative Recap
For an investor to stay with Omnicom Group, the key belief is that the shift toward data and AI led media, plus the integration of Interpublic assets, will matter more than recent earnings volatility and higher debt costs. The short term swing factor is execution on new Omni and Acxiom backed offerings that can attract larger media and health budgets.
The biggest near term risk remains pressure on traditional advertising and uneven regional trends, which could dilute the benefit from higher growth segments. The Tom Schwenger appointment does not transform that risk on its own. However, it slightly improves the odds that healthcare becomes a more durable contributor.
The most relevant development here is Omnicom Group being named a Leader in Forrester's global media management report, alongside new client wins and retained billings. That third party recognition sits directly next to the hiring of a pharma and biotech focused CEO for Omnicom Health, which supports the same data heavy story.
If the enlarged media management network and Omni AI tools see broader adoption, Schwenger's focus on tailored engagement models for life sciences clients could turn healthcare into a clearer catalyst for revenue mix and margins. Execution risk is still present, especially with advertising weakness and higher interest expense, so progress in signed scopes and renewals will matter more than headlines.
What The Current Omnicom Group Forecasts Assume
Omnicom Group's narrative projects US$26.0b revenue and US$2.6b earnings by 2029. This rests on analysts modeling 5.2% yearly revenue growth and an earnings increase of about US$2.2b from US$390.2m today.
Uncover why Omnicom Group's fair value indicates an 18% potential upside to its current price, which could narrow quickly.
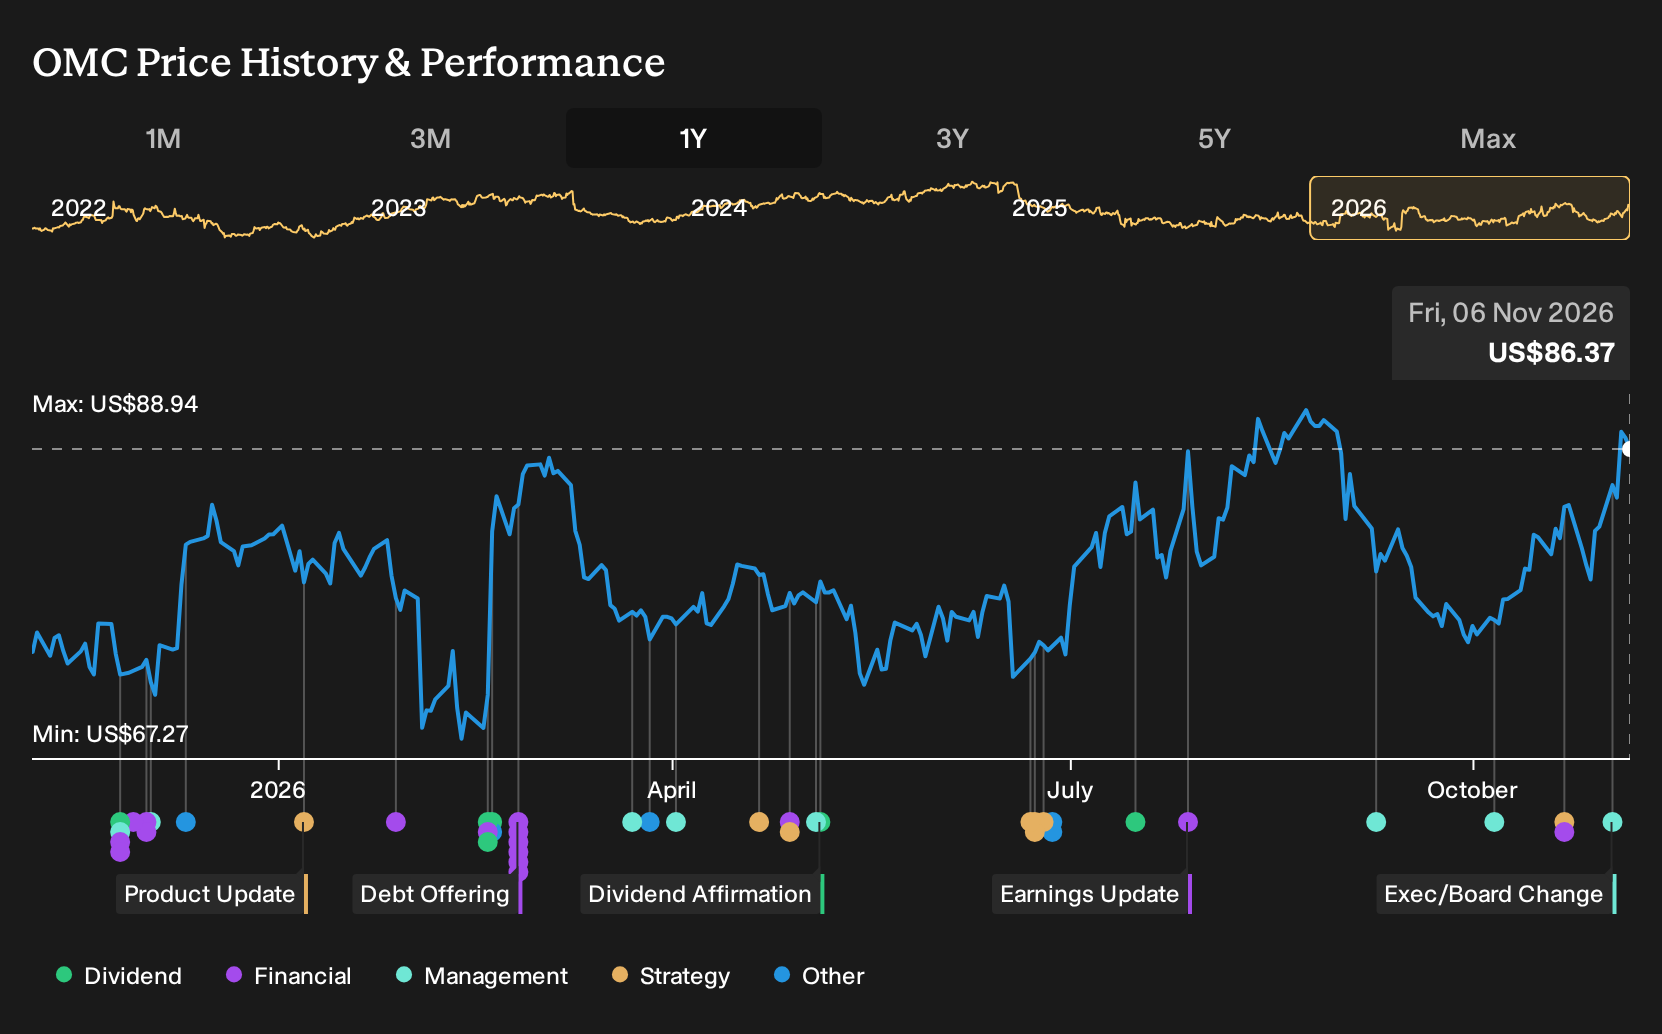
Exploring Other Perspectives
One alternate view is that Omnicom Group may struggle to turn its media scale and AI tools into real pricing power as more marketing work moves in house. The most bearish analysts were penciling in about US$25.8b of revenue and US$2.7b of earnings by 2029, yet still only saw a US$77.0 fair value. That is a tighter, more cautious story than consensus. The Tom Schwenger appointment plus Forrester recognition could give you fresh reasons to recheck which side of that spread you find more convincing.
Explore 3 other Omnicom Group fair value estimates, including one that suggests up to 11% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own research and judgment.
- A great starting point for your Omnicom Group research is our analysis highlighting 2 key rewards and 5 important warning signs that could impact your investment decision.
- See our latest analysis for Omnicom Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Omnicom Group's overall financial health at a glance.
Looking For More Omnicom Group Sized Investment Ideas?
Once you have a view on Omnicom Group, it can help to line it up against other potential opportunities that fit different risk, income, and balance sheet profiles using the Simply Wall St Screener.
- For investors who care most about resilient businesses and capital preservation, consider starting with a 31 resilient stocks with low risk scores that aim to keep downside risk in check.
- If income is your focus and you want candidates that might support regular payouts, scan a curated set of 7 dividend fortresses that could suit a yield oriented approach.
- Readers hunting for companies with strong financial foundations can review a list of solid balance sheet and fundamentals (25 results) to compare with Omnicom Group's profile.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com