


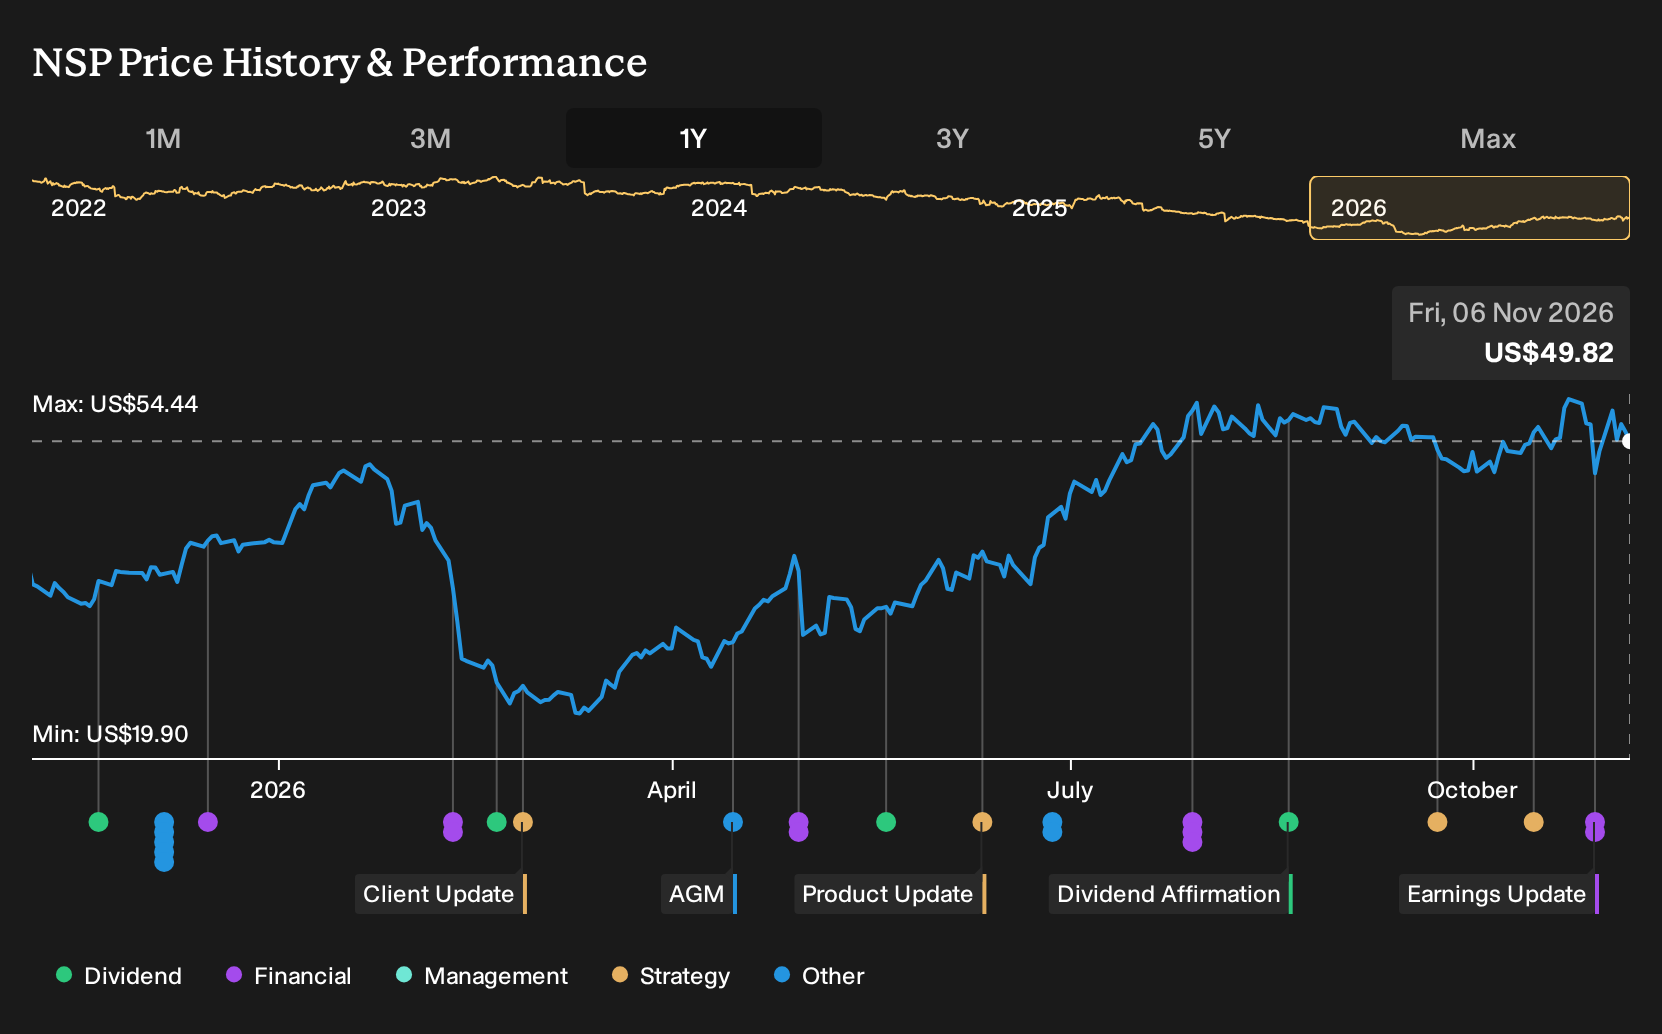
- Insperity reported third quarter 2026 sales of US$1,651 million and a small net loss of US$1 million, with nine month net income reaching US$36 million on US$5,232 million of sales.
- Management tied the better third quarter outcome and higher full year 2026 earnings guidance to margin recovery work, including pricing adjustments, client retention efforts and tighter expense control.
- We will now look at how Insperity's margin recovery progress and higher full year guidance could reshape the existing investment narrative.
Compare Insperity's margin repair story with other employers focused on resilient cash flows and disciplined costs by scanning our curated list of list of solid balance sheet and fundamentals (25 results)
Insperity Investment Narrative Recap
For an investor to stay with Insperity, the core belief is that margin repair on existing clients and newer offerings like HRScale can offset soft worksite employee trends and healthcare cost volatility. The latest quarter and updated 2026 earnings guidance reinforce that story, since profitability over nine months stayed positive even with a small third quarter loss.
In the short term, the key catalyst is continued progress on pricing, benefits design and cost discipline, which management links to the recent adjusted EBITDA improvement. The biggest risk still sits with healthcare and benefits expense. Fourth quarter net income guidance, which ranges from a loss to a modest profit, underlines how exposed earnings remain to benefit cost swings.
The most relevant update for that debate is Insperity’s full year 2026 outlook. Management now guides to net income of US$32 million to US$45 million and diluted EPS of US$0.81 to US$1.16, alongside a fourth quarter range that stretches from a US$6 million loss to an US$8 million profit.
Those figures, combined with management’s separate guidance that adjusted EPS could land between US$1.93 and US$2.28, keep attention firmly on execution. For you as a shareholder, the operational question is whether pricing, HRScale ramp, client retention and AI driven productivity can consistently outrun benefit inflation and tepid worksite employee counts.
Insperity's current analyst narrative points to revenues of US$7.7 billion and earnings of US$145.3 million by 2029, anchored on forecast top line growth of 3.7% per year. That path assumes earnings move from a loss of US$16.0 million today to the projected US$145.3 million, an increase of about US$161 million over the period.
Uncover how Insperity's fair value indicates a 4% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One bullish twist in the Insperity story centers on HRScale. The most optimistic analysts were already penciling in revenue of about US$7.8b and earnings of roughly US$147.8 million by 2029 before this quarter, assuming HRScale economics match HR360 over time. You can treat this fresh margin news as a prompt to compare that upbeat path with more cautious views.
Explore 3 other Insperity fair value estimates, including one that suggests as much as 261% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Insperity research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Insperity. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Insperity's overall financial health at a glance.
Looking For More Investment Ideas Beyond Insperity?
Once you have a view on Insperity, it can help to widen the lens and compare it with other businesses that fit different risk and income profiles using the Simply Wall St Screener.
- For investors who care most about balance sheet resilience and steady fundamentals, scan a curated list of solid balance sheet and fundamentals (25 results) that may offer a different mix of quality and stability.
- If the goal is to back companies that look attractively priced relative to their fundamentals, review a focused set of 36 high quality undervalued stocks that might fit a value oriented approach.
- Income focused investors who prioritise reliable cash returns can check out a group of 7 dividend fortresses that pair higher yields with fundamental strength.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com