


Fair Isaac (FICO) just paired a strong earnings release with recent adoption wins for its scoring products, including new participants in the FICO Preferred Program and an upgrade to FICO Auto Score 10 at Arvest Bank.
Despite the upbeat earnings release and new client wins, Fair Isaac’s share price has declined 57.13% year to date and its 1 year total shareholder return is down 59.51%. However, a 5 year total shareholder return of 87.54% points to much stronger earlier momentum that has faded sharply over the past year.
Spot other credit and risk analytics plays showing similar momentum by scanning the 19 high quality undiscovered gems, which have been hand picked for strong fundamentals and under the radar potential.Fair Isaac is growing revenues and earnings while the share price has dropped hard over the past year. Is this slide about the business itself, or mostly about sentiment and valuation resetting?
Most Popular Narrative: 11.4% Overvalued
According to the most followed Fair Isaac narrative, the current share price of $704.55 sits above an estimated fair value of $632.72, which puts recent earnings strength against a cooler view on how much investors are paying for that profile.
At $711.23, FICO still looks overvalued or slightly overvalued, even after its recent sudden price drop. I would probably buy or add below $512.46.
See why 2 investors see Fair Isaac as 11% overvalued.
Result: Fair Value of $632.72 (OVERVALUED)
Still, Fair Isaac faces real swing factors, including how lenders respond to VantageScore and whether debt-funded buybacks limit future financial flexibility.
Find out about the key risks to this Fair Isaac narrative.
Another View: Fair Isaac Looks Cheap On Earnings
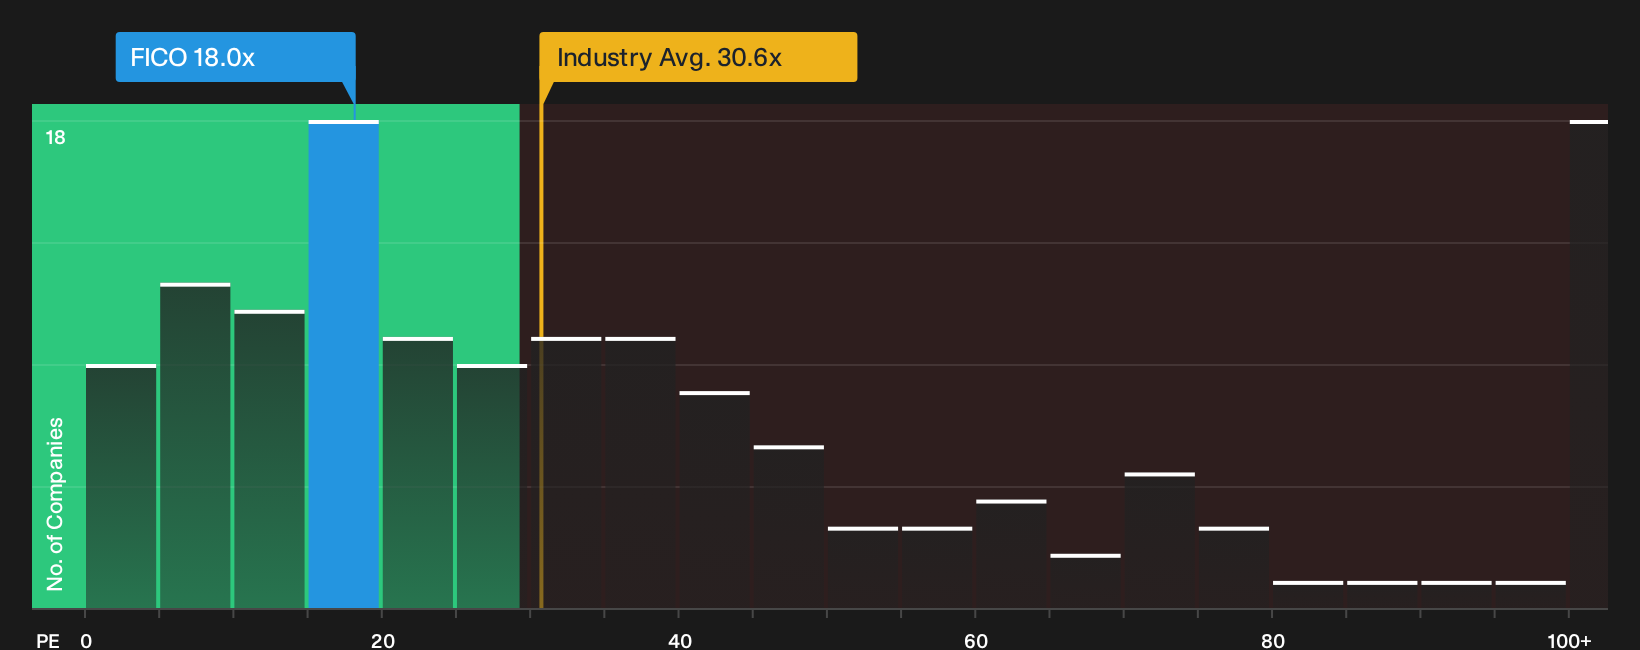
Where the dominant Fair Isaac narrative leans on a detailed fair value of $632.72 and calls the stock 11.4% overvalued, the simple earnings multiple points in the opposite direction. At a P/E of 18x against a US Software average of 30.7x and a fair ratio of 31.3x, the current tag looks more like a discount than a premium. If the market shifts even part of that gap toward the fair ratio, how comfortable are you ignoring what the P/E is signaling today?
To pressure test that multiple against the underlying assumptions and see how much room there might be before the P/E moves, See what the numbers say about this price — find out in our valuation breakdown.
Here is how Fair Isaac’s P/E stacks up visually against peers and the broader industry, which helps frame whether the lower multiple reflects caution or a potential opportunity,
Next Steps
Sentiment on Fair Isaac is split, with some investors focusing on valuation pressure and others pointing to underlying strengths that still attract capital. To weigh both sides quickly and build your own view, review the 4 key rewards and 2 important warning signs.
Looking for more Fair Isaac investment ideas?
If Fair Isaac has sharpened your interest in credit and risk plays, do not stop here. Broader screening can reveal opportunities that match your risk, income, and growth preferences.
- Target resilient balance sheets and dependable fundamentals by scanning a list of solid balance sheet and fundamentals (25 results) to see which businesses line up with a quality first checklist.
- Hunt for potential mispricings by reviewing a 36 high quality undervalued stocks that filters for strong cash generation at prices that may not fully reflect those traits.
- Prioritise stability and sleep at night holdings by checking a 31 resilient stocks with low risk scores tailored for investors who want smoother return profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com