


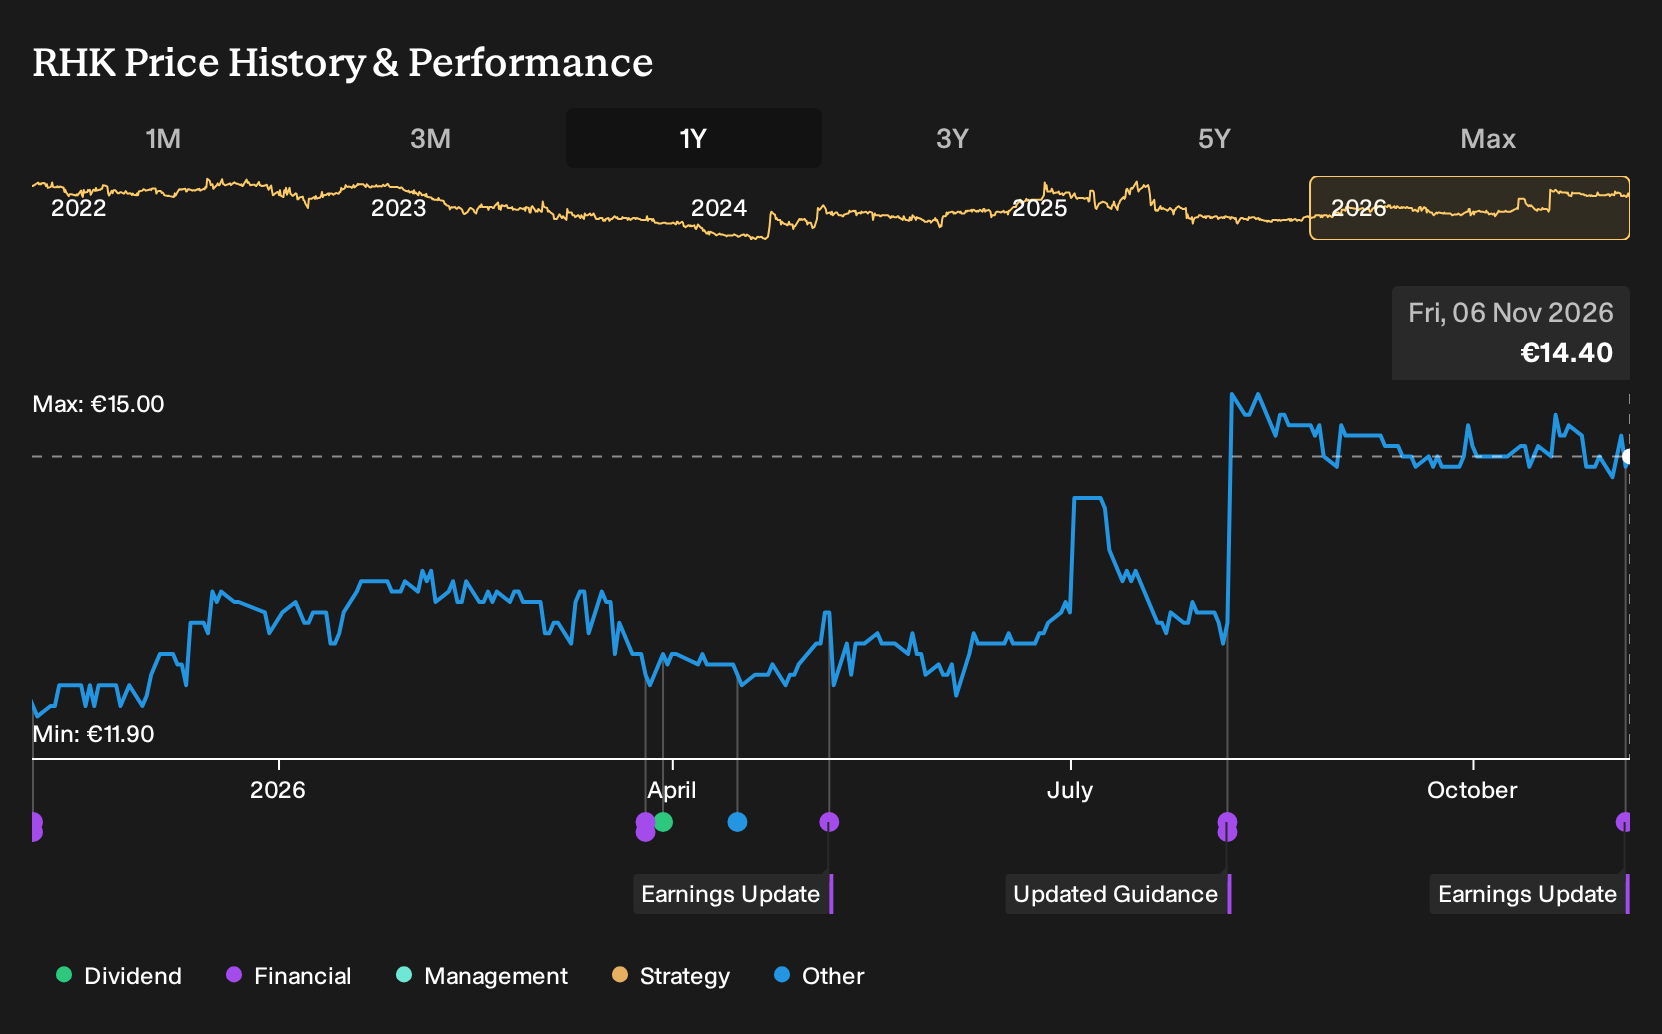
- RHÖN-KLINIKUM reported nine month 2026 figures with sales of €1,303.8 million, revenue of €1,546.79 million and net income of €31.61 million, alongside basic and diluted EPS from continuing operations of €0.47.
- The widening gap between revenue and sales, combined with higher earnings per share compared to the prior year period, points to important shifts in RHÖN-KLINIKUM’s business mix and cost structure that investors may want to understand.
- This analysis now looks at how RHÖN-KLINIKUM’s investment narrative may be affected by the higher nine month net income and earnings per share.
What Is RHÖN-KLINIKUM's Investment Narrative?
To stay invested in RHÖN-KLINIKUM, you need to believe in a fairly simple idea. The group has to keep running its clinics efficiently enough that modest revenue growth and tight cost control translate into steady earnings. The latest nine month figures, with higher net income and EPS versus a year ago, point to that execution focus. Management still operates in a capital intensive field where beds, buildings and equipment tie up a lot of cash, so consistent returns on that base matter more than headline expansion.
In the short term, the key swing factors look operational rather than story driven. Profitability needs to hold up even if revenue is forecast to grow 2.9% per year, while earnings are expected to rise faster. The fresh results fit that pattern, with profit outpacing the top line. At the same time, the stock trades on a 22.9x P/E, which screens as more expensive than sector and peer averages, so any wobble in hospital demand, pricing or staffing costs can affect performance quickly.
Yet one structural pressure on RHÖN-KLINIKUM's funding mix and returns still hangs over the equity story...
There's only one way to know the right time to buy, sell or hold RHÖN-KLINIKUM. Head to Simply Wall St's company report for the latest analysis of RHÖN-KLINIKUM's Fair Value.
Form Your Own Verdict
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your RHÖN-KLINIKUM research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for RHÖN-KLINIKUM. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate RHÖN-KLINIKUM's overall financial health at a glance.
Looking For More Ideas Beyond RHÖN-KLINIKUM?
If this RHÖN-KLINIKUM review has sharpened your thinking but you want a wider watchlist, the Simply Wall St Screener can help you scan for other companies that fit your risk, income, and quality preferences in just a few minutes.
- If you care most about quality at a reasonable entry point, start with a focused set of potentially mispriced opportunities using the 219 high quality undervalued stocks.
- For investors who want income on top of potential capital returns, filter for sturdier payout profiles by running the 228 dividend fortresses.
- If resilience matters more than excitement right now, narrow your watchlist to steadier profiles by checking the 211 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com