


Hannover Rück (XTRA:HNR1) came into focus after J.P. Morgan cut its rating on the reinsurer, noting that expectations for a mild 2026 hurricane season and rising sector capital could pressure reinsurance pricing in 2027.
The downgrade triggered a 1-day share price decline of 4.37% to €293.0. However, Hannover Rück still shows building momentum with a 30-day share price return of 11.32% and a 1-year total shareholder return of 23.8%, extending to 117.5% over five years.
Scan beyond Hannover Rück and stress test your thesis against a hand picked 209 resilient stocks with low risk scores that may hold up better if reinsurance pricing pressure persists.
The downgrade just clipped Hannover Rück after a strong run, which leaves you weighing two paths: step in after this pullback or wait to see if the valuation gives you a second chance.
Most Popular Narrative: 5% Overvalued
The most followed valuation view on Hannover Rück pegs fair value at €279.94, which sits below the latest close at €293. That gap frames the downgrade as a pricing question rather than a story about broken fundamentals.
Softening risk adjusted prices in traditional P&C treaty business alongside an 83.2% combined ratio in H1 2026 and continued additions to prudency reserves indicate Hannover Rück is still using underwriting discipline and reserving to protect margins, which can support net margin and earnings resilience as the cycle develops.
See why 32 investors see Hannover Rück as 5% overvalued.
Result: Fair Value of €279.94 (OVERVALUED)
Still, the narrative can crack if P&C pricing keeps softening or Life & Health growth cools as competition intensifies in key financial solutions markets.
Find out about the key risks to this Hannover Rück narrative.
Another Lens On Hannover Rück’s Value
Analyst targets frame Hannover Rück as modestly overvalued around €293 versus a €279.94 fair value, yet the SWS DCF model points in the opposite direction. On that cash flow view, the stock trades about 55.5% below an estimated value of €658.05, which raises a simple question: Is the market underestimating long term cash generation or are the cash flow assumptions too generous?
To pressure test that cash flow view against your own assumptions on pricing, claims and reinvestment yields, Look into how the SWS DCF model arrives at its fair value.
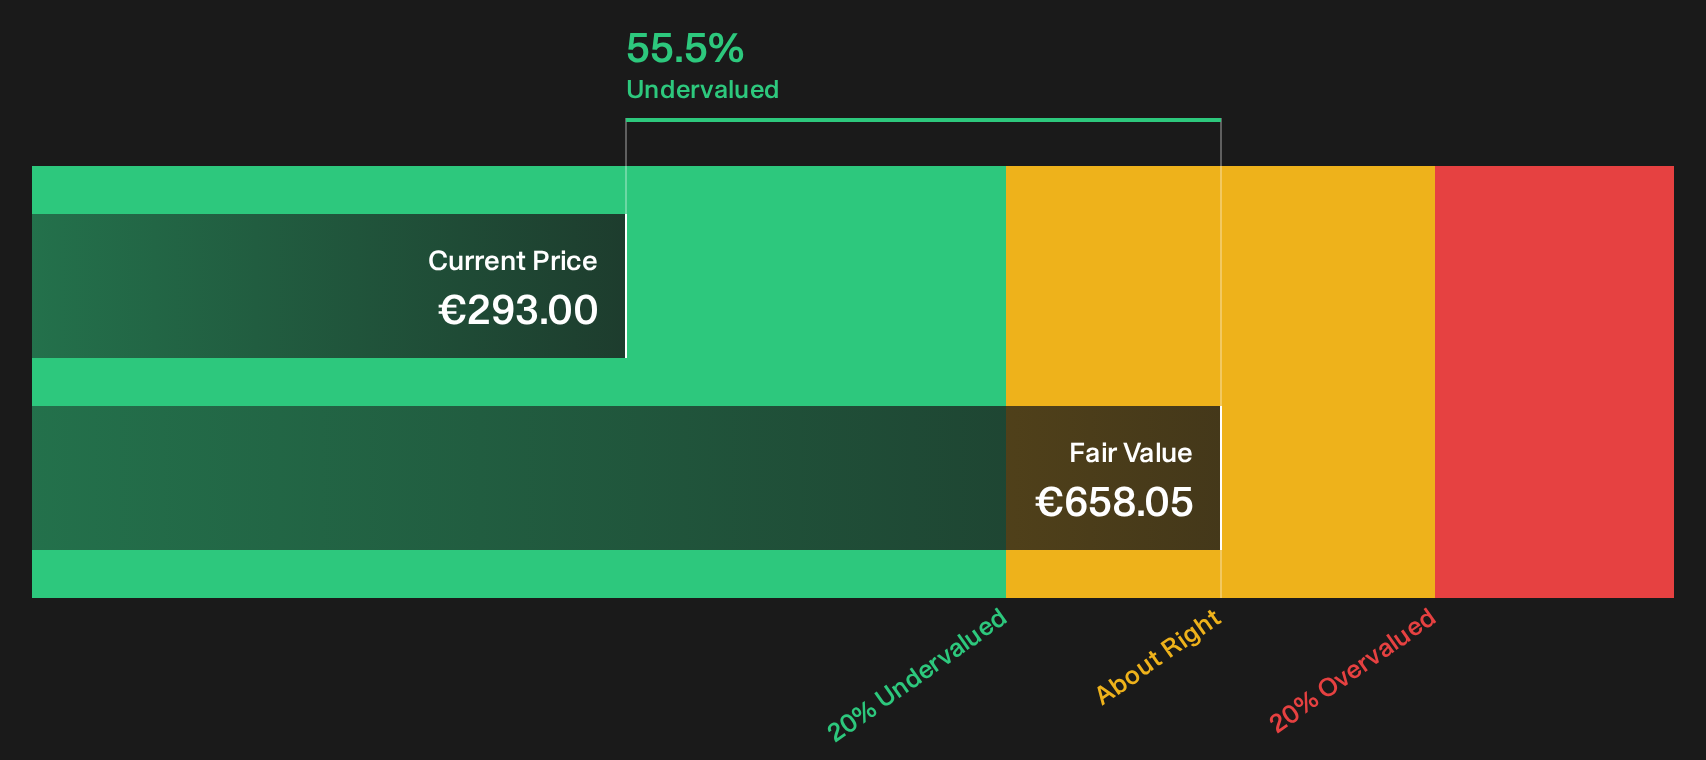
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Hannover Rück for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 222 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Hannover Rück can create hesitation, so move quickly through the data, test your own assumptions, and then weigh the 4 key rewards
Looking for more investment ideas beyond Hannover Rück?
Do not stop with one reinsurer. Use the Simply Wall Street Screener to test fresh ideas now, before the next round of opportunities moves without you.
- Target resilient compounding potential by scanning a curated 222 high quality undervalued stocks that combines quality fundamentals with pricing that still looks reasonable on the numbers.
- Strengthen capital preservation by filtering candidates through a list of solid balance sheet and fundamentals (192 results) that focuses on robust financial positions and cleaner balance sheets.
- Hunt for under-the-radar potential by running a 582 high quality undiscovered gems that surfaces lesser-known stocks with stronger fundamentals than their profile suggests.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com