


- Futu Holdings has recently highlighted rapid growth in funded client accounts, reaching about 3.84 million, with nearly 60% now sourced from overseas markets.
- The business increasingly looks like a pure play on interest income, since its digital brokerage and wealth platforms actively deploy idle client cash.
- We will examine how Futu Holdings' sharp funded account expansion reshapes the investment narrative around its cash deployment model.
Futu Holdings Investment Narrative Recap
To own Futu Holdings, you need to believe its interest income model and digital brokerage platforms can keep attracting and retaining funded clients globally. The sharp rise to about 3.84 million funded accounts, with nearly 60% overseas, shows that the franchise is leaning harder into international cash rich users who feed that engine.
The key short term swing factor is still the rate environment and how effectively Futu Holdings deploys idle balances into interest earning assets without raising its own funding costs too aggressively. The biggest near term risk stays the same. Regulatory or legal setbacks around China related activities could hit client assets, trading activity and economics on that cash.
There have been no fresh company specific announcements tied directly to this funded account milestone. The most relevant information remains the previously disclosed international expansion and product build out. For investors, the link is straightforward: a broader overseas footprint gives Futu Holdings more pools of client cash to potentially deploy across cycles.
The earlier disclosure that markets such as Singapore, the U.S., Japan, Australia and Canada show rising client assets matters here, because it frames where incremental funded accounts may be coming from. Those regions, combined with wealth management assets of around HKD 178b to HKD 180b and the VATP license at PantherTrade, shape potential catalysts and widen the range of outcomes if trading or regulation turn less supportive.
Futu Holdings' current assumptions point to forecast revenues of about HK$30.5b and earnings of HK$15.7b by 2029, based on analysts who model revenue expanding at roughly 8.3% a year and earnings rising from about HK$11.1b today to that HK$15.7b level, an increase of roughly HK$4.6b over the period.
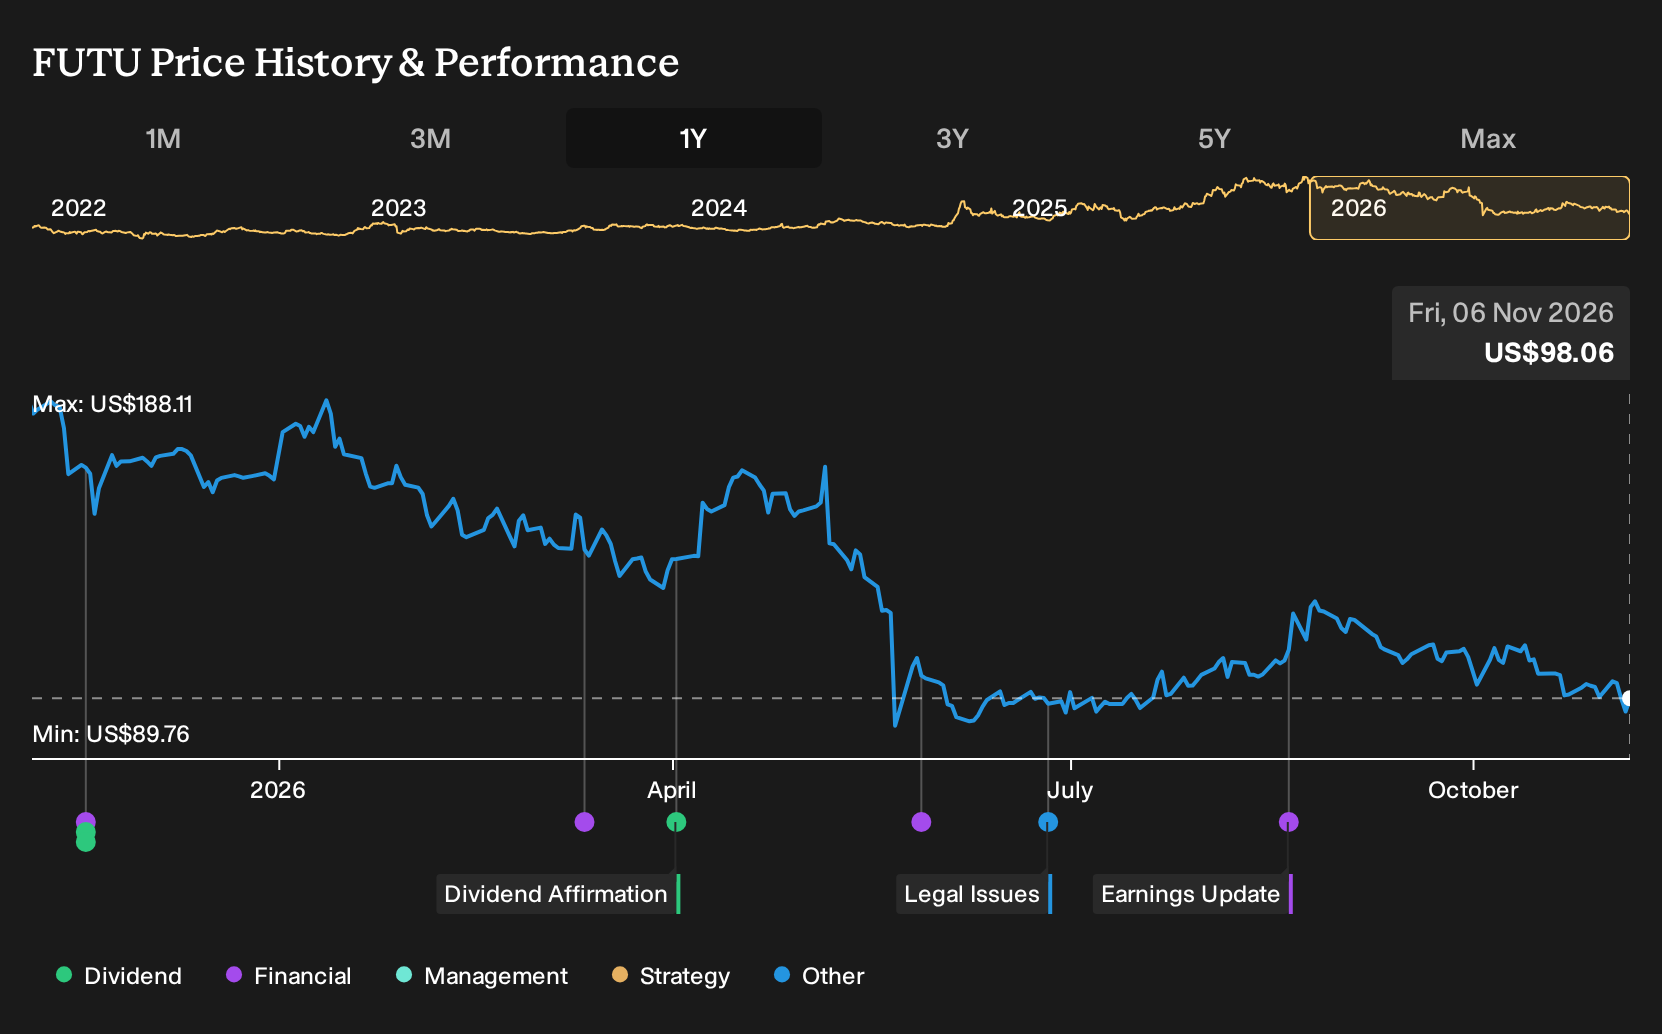
Uncover why Futu Holdings' fair value indicates a 64% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One big swing factor you might weigh differently is regulatory pressure on Futu Holdings. The most cautious analysts built their story around legal and compliance drag, which is why they were only pencilling in revenue of about HK$27.7b and earnings near HK$14.0b by 2029. Those forecasts came before this funded account milestone, so views may evolve.
Explore 4 other Futu Holdings fair value estimates, including one that suggests it could be worth just $121.88!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Futu Holdings research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Futu Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Futu Holdings' overall financial health at a glance.
Looking for more investment ideas beyond Futu Holdings?
If the Futu Holdings story has you thinking about other ways to put capital to work, the Simply Wall St Screener can help you quickly surface stocks that fit very different playbooks, from income resilience to balance sheet strength and early stage potential.
- If dependable cash flows matter to you, scan for income opportunities using our 7 dividend fortresses that already clear a 5% yield hurdle.
- If capital protection is your priority, narrow your watchlist with a 31 resilient stocks with low risk scores that screens for resilient businesses with sturdier risk profiles.
- If you are hunting for earlier stage ideas with room to grow, cast a wider net across the market using our 9 elite penny stocks with strong financials and see which smaller companies still pair ambition with solid financials.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com