


- Voya Financial expanded its Multiple Employer Solutions business after rapid growth toward roughly US$200b in assets, while recently reporting higher third quarter net income, earnings per share from continuing operations and a larger common dividend for late 2026.
- The combination of scaled pooled employer plan capabilities, extended recordkeeping services for smaller employers and continued activist pressure highlights how Voya Financial is trying to deepen workplace retirement reach while defending its governance approach.
- We will examine how Voya Financial’s investment narrative is influenced by the expanded Multiple Employer Solutions platform and recent earnings update.
Voya Financial Investment Narrative Recap
To be comfortable owning Voya Financial, you need to believe the workplace focused model can keep turning large retirement and benefits relationships into stable fee and premium streams while earnings volatility stays contained. The recent Multiple Employer Solutions expansion supports that belief, since it speaks directly to growing pooled plans and broadening the retirement funnel.
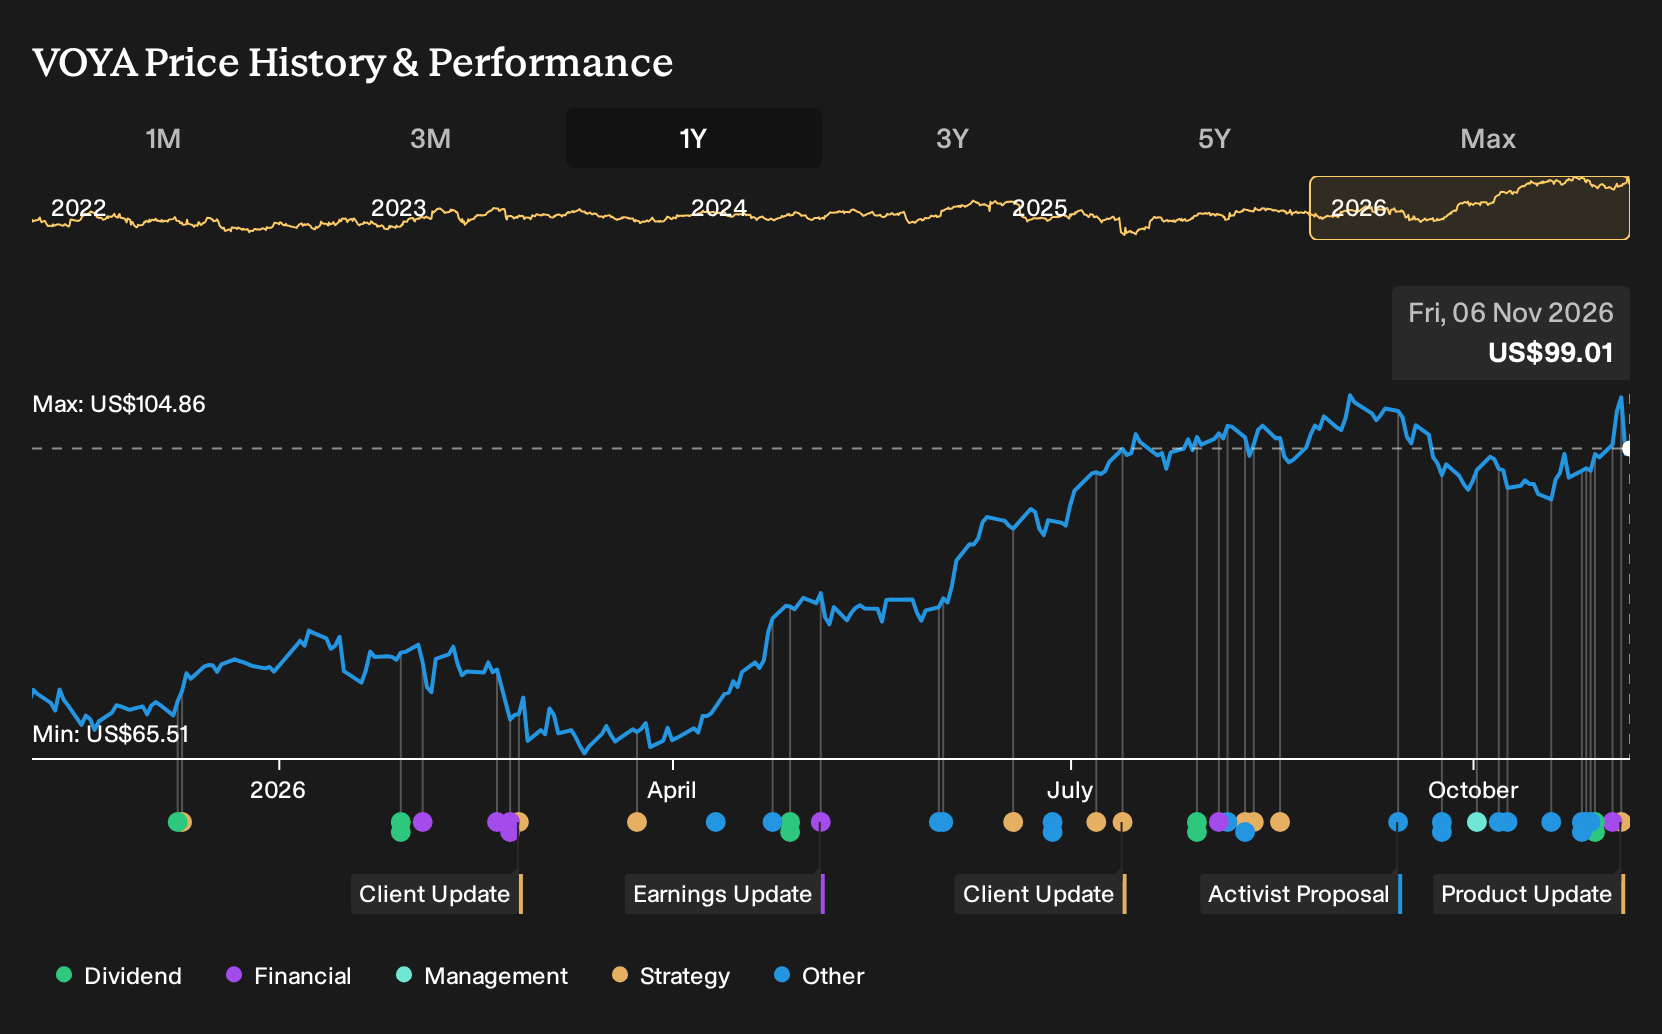
The near term swing factor remains earnings quality, including how alternative investments and Employee Benefits results track expectations. Third quarter 2026 showed higher net income and EPS despite lower revenue, which helps sentiment, but the TOMS Capital campaign keeps governance risk in focus if disputes distract leadership or complicate capital decisions.
The dividend increase to US$0.57 per share for the fourth quarter of 2026 sits right in the middle of these moving pieces. It ties into Voya Financial’s existing income story, where the stock already carries a 1.9% dividend yield and has been framed as offering reliable payouts alongside fee based growth plans.
For catalysts, a higher common dividend can matter because it puts more weight on the cash generation side of the thesis at the same time activist scrutiny is intense. If operating execution around MES expansion, retirement flows and Employee Benefits margins lines up with that higher distribution, the payout becomes a more visible part of how investors judge whether the current trajectory is on track.
Voya Financial's narrative points to revenue of US$8.5b and earnings of US$1.1b by 2029, based on analysts' forecasts. That path assumes revenue grows by 1.4% a year, and that profits rise by about US$533m from current earnings of US$567m to reach the 2029 consensus level.
Uncover why Voya Financial's fair value indicates a 9% potential upside to its current price, which may not last much longer.
Exploring Other Perspectives
One alternate view focuses on Employee Benefits. The most optimistic analysts, who were previously penciling in revenue of about US$8.7b and earnings near US$1.3b by 2029, view Stop Loss repricing and underwriting discipline as key earnings swing factors, in addition to retirement scale. Their expectations are more upbeat than consensus, and the new Voya Financial MES expansion could eventually lead both narratives to evolve.
Explore another Voya Financial fair value estimate, including one that suggests potential upside of as much as 44% from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Voya Financial research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Voya Financial. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Voya Financial's overall financial health at a glance.
Looking for more investment ideas beyond Voya Financial?
Voya Financial might fit your watchlist, but your next strong idea could come from a very different corner of the market. The Simply Wall St screener lets you filter for the mix of quality, income and risk that suits your own plan.
- For investors who want income to play a bigger role in returns, scan a curated set of high yield opportunities through the 7 dividend fortresses.
- If capital preservation and steady balance sheets matter most to you, narrow the field using a 31 resilient stocks with low risk scores that filters for resilience first.
- When you want to widen the search beyond Voya Financial and focus on quality at a reasonable price, start with a 38 high quality undervalued stocks that blends fundamentals with valuation discipline.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com