


Why Exelon Stock Is Back In Focus
Exelon (EXC) is drawing fresh attention after reaffirming long term earnings guidance, reporting mixed third quarter 2026 results, and keeping its regular dividend unchanged, while also highlighting growing exposure to data center power demand.
Recent trading reflects that push and pull. The share price is down 1.96% over the past day and 1.17% over the past week, following a 9.24% 1 month share price return and a 3.87% year to date share price gain that points to improving momentum. A 39.51% 5 year total shareholder return indicates that longer term holders have already seen meaningful value creation.
Compare Exelon with a curated group of utilities exposed to similar long term themes in grid demand and data centers by screening for 41 power grid technology and infrastructure stocks.
Exelon appears to be a solid regulated utility with grid projects tied to data centers and reaffirmed earnings guidance. After the recent share price run, is that quality already fully reflected in the valuation?
Most Popular Narrative: 4% Undervalued
Exelon closed at $45.62 compared with a narrative fair value estimate of $47.59, which points to a modest valuation gap built on grid investment expectations and data center related load assumptions.
The rebalanced US$41.7b capital plan that shifts US$1.5b into higher earning transmission while deferring US$1.1b of lower priority distribution projects positions Exelon to pursue its targeted 7.9% rate base growth with a tilt toward assets that can support operating EPS and cash flow.
See why 39 investors see Exelon as 4% undervalued.
Result: Fair Value of $47.59 (UNDERVALUED)
Still, regulatory setbacks around rate cases and any tightening in customer affordability or credit conditions could challenge Exelon’s US$41.7b capex plan and its earnings narrative.
Find out about the key risks to this Exelon narrative.
Another View On Exelon’s Valuation
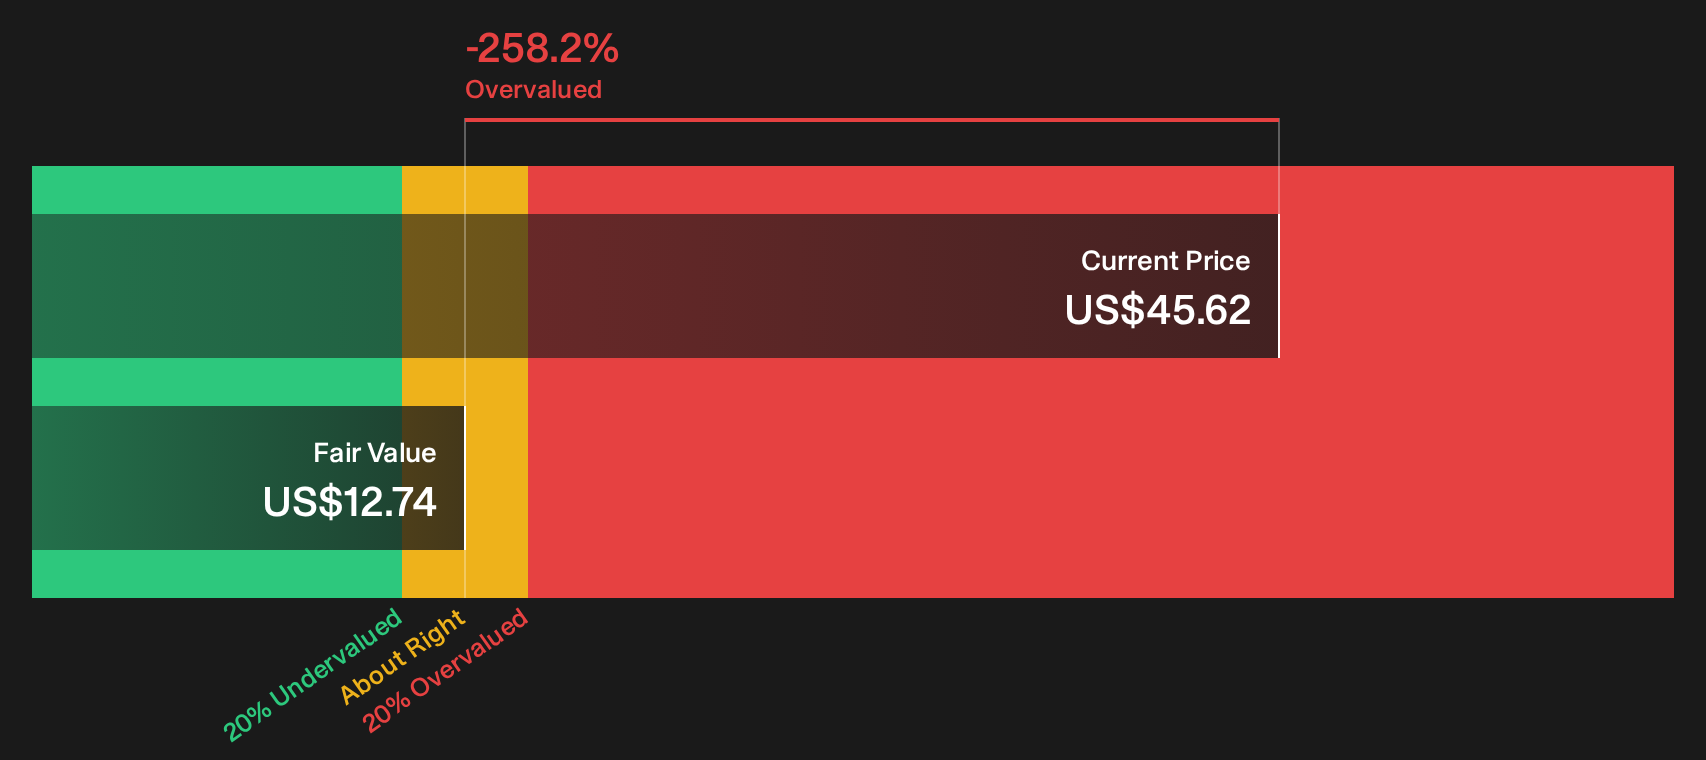
There is a different signal when Exelon is run through the SWS DCF model. On this framework, the estimated future cash flow value is $12.74 per share, well below the current $45.62 price, which frames the stock as overvalued rather than modestly undervalued.
That kind of gap suggests investors are putting a higher price on Exelon’s regulated earnings stream than the cash flow model supports. The question is whether long term rate base plans and data center driven load justify paying that premium, or if cash generation should be the anchor.
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Exelon for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 38 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Exelon’s valuation and growth plans can pull opinions in different directions, so move fast, test the numbers yourself, and carefully examine both the upside and downside before deciding where you land with the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Exelon?
If Exelon has sharpened your interest in regulated utilities and dependable cash flow, you can use that momentum to broaden your opportunity set with a few targeted stock screens.
- Pinpoint quality at a discount by scanning a curated 38 high quality undervalued stocks that filters for strong fundamentals and pricing that may not fully reflect them yet.
- Prioritise resilience by reviewing a 31 resilient stocks with low risk scores tailored to companies with steadier balance sheets and lower measured risk scores than the broader market.
- Spot tomorrow’s potential leaders early by checking a 19 high quality undiscovered gems that highlights lesser known businesses with solid underlying metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com