


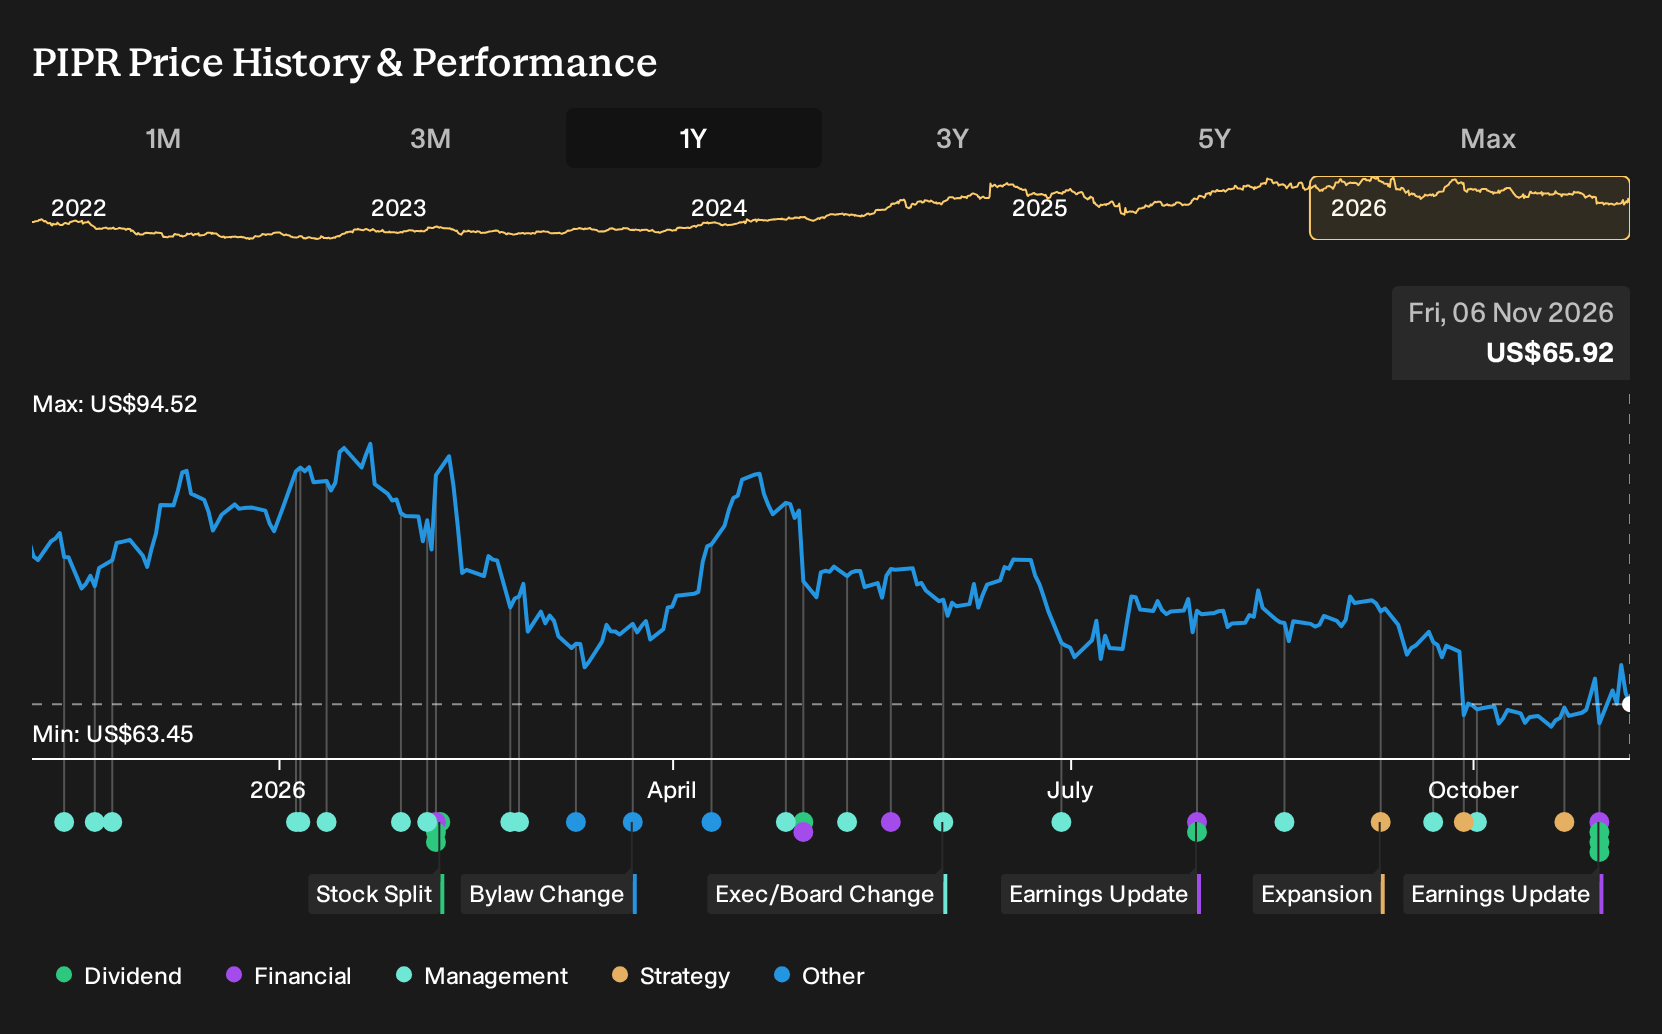
- Piper Sandler Companies reported third quarter 2026 revenue of US$443.65 million and net income of US$55.42 million, alongside a new US$200 million share repurchase authorization and a US$0.20 per share quarterly dividend declared on October 30, 2026.
- Short term earnings softness contrasts with higher nine month revenue and profit, while the fresh buyback plan and ongoing dividend indicate that management is prioritizing disciplined capital deployment in line with current operating trends.
- Next, the focus turns to how Piper Sandler Companies' mixed earnings and new US$200 million repurchase plan could influence its investment narrative.
Piper Sandler Companies Investment Narrative Recap
To hold Piper Sandler Companies, an investor needs to be comfortable with an advisory and capital markets firm whose earnings ebb and flow with deal activity, issuance and trading volumes. The latest quarter showed softer revenue and profit than a year ago, while the nine-month figures were higher, so the near term story is really about resilience rather than acceleration.
The key short term swing factor is how quickly corporate finance, bank M&A and public finance pipelines convert into closed transactions and fees. The main operational risk remains a slowdown in equity and fixed income activity or weaker depository valuations that delay deals. This earnings update does not fundamentally change either that catalyst or that threat.
The new US$200 million share repurchase authorization running through 2028 is the headline development for this earnings release. It sits alongside ongoing hiring needs in technology, government services, defense and artificial intelligence coverage, and it will be judged against Piper Sandler Companies' ability to keep funding that expansion while managing compensation and occupancy costs.
For you as a shareholder, the plan directly intersects with the biggest current levers on the story. If advisory, public finance and trading activity remain solid, buybacks can offset dilution from equity compensation and keep per share metrics supported. If deal flow slows or private credit and sponsor activity cools, a long dated repurchase program might become less of a focus than preserving flexibility around funding and earnings quality.
Piper Sandler Companies' current consensus assumes revenue grows at 7.6% a year and earnings rise from US$302.5 million today to US$336.1 million by 2029, a US$33.6 million increase on the path to forecast revenues of US$2.6b in that same year.
Discover why Piper Sandler Companies' fair value suggests a 13% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Fair value estimates for Piper Sandler Companies from 3 members of the Simply Wall St Community span a wide band, from US$25.62 to US$74.75 per share. That spread shows how far opinions can stretch before the new earnings, dividend and buyback details are fully absorbed. You can use those contrasts to stress test your own view.
Explore 2 other Piper Sandler Companies fair value estimates, including one that suggests as much as 61% downside from the current price.
Reach Your Own Conclusion
Do not just follow the ticker; dig into the data and build a conviction that is truly your own.
- A great starting point for your Piper Sandler Companies research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Piper Sandler Companies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Piper Sandler Companies' overall financial health at a glance.
Looking For More Investment Ideas Beyond Piper Sandler Companies?
Once you have a view on Piper Sandler Companies, it can help to widen the lens and compare it with other businesses that share similar qualities or offer different trade offs on risk, income and balance sheet strength.
- For investors hunting for mispriced quality, review our 38 high quality undervalued stocks that combine resilient finances with the potential for a better entry point.
- If capital preservation and steadier profiles matter most to you, scan a 31 resilient stocks with low risk scores that aim to keep downside pressures in check.
- When balance sheet strength is the first filter, start with a list of solid balance sheet and fundamentals (25 results) and see which companies currently pass those tests.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com