


- Coupang reported third quarter 2026 revenue of US$9,962 million compared with US$9,267 million a year earlier, alongside a move from a US$95 million profit to a US$501 million net loss, and issued fourth quarter guidance for constant currency revenue growth of 13% to 14% with continued Product Commerce recovery.
- The sharp swing from net income to losses in both the quarter and the first nine months, despite higher sales, points to pressure on Coupang’s cost structure and profitability. This now sits at the center of analyst concerns about its near term earnings power.
- Next, the focus will be on how Coupang’s revenue growth paired with a renewed net loss could reshape the broader investment narrative.
Compare Coupang's sharp swing into losses with other e commerce players that still screen well on balance sheet strength and fundamentals by checking our curated list of solid balance sheet and fundamentals (25 results).
What Is Coupang's Investment Narrative?
Coupang’s story still comes down to whether you believe its high volume logistics engine in Korea and newer services like Eats and Play can eventually support consistent profits, not just big revenue lines. The third quarter loss of US$501 million and nine month loss of US$1,337 million put execution in the spotlight. Heavy fulfillment infrastructure, marketing and developing offerings all demand cash. Guidance for 13% to 14% constant currency revenue growth in the fourth quarter suggests management still sees solid demand in Product Commerce, but the near term question is how much more capital this model consumes before margins steady.
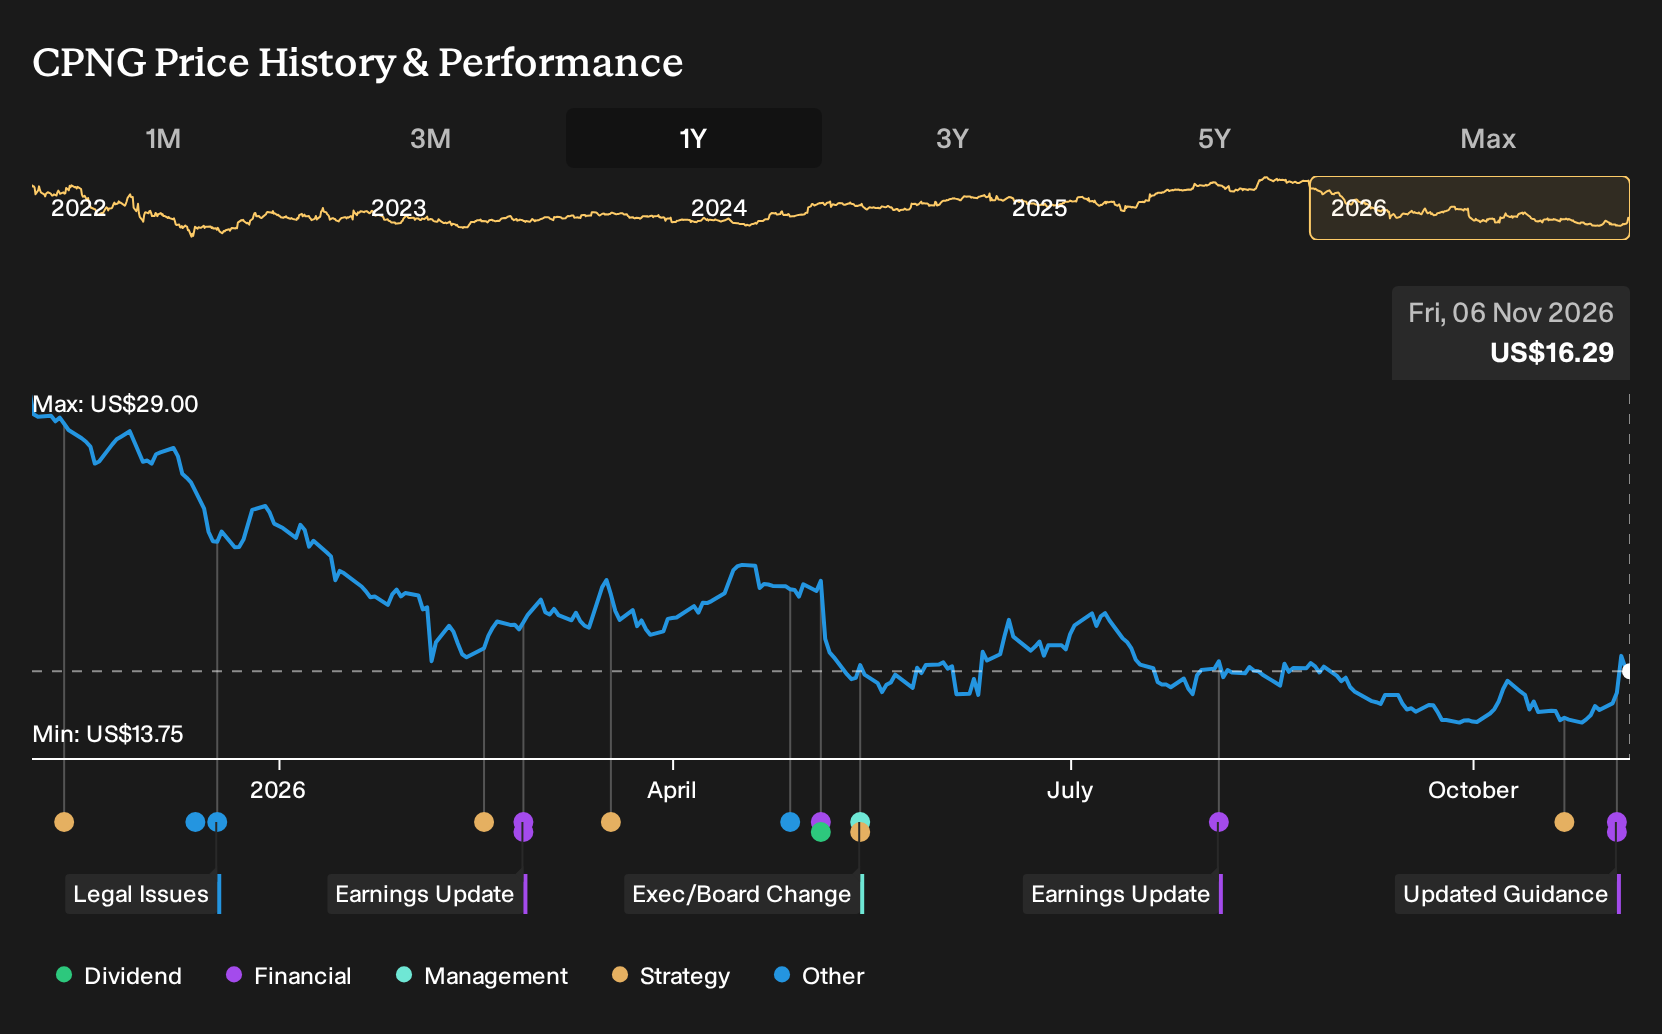
In the short term, the key catalysts are proof that Product Commerce can grow without further erosion in earnings and clearer disclosure on how much the Developing Offerings segment weighs on results. Analyst enthusiasm on long term earnings forecasts and discounted valuation metrics helps sentiment, yet the stock’s roughly 43% decline over the past year shows how quickly the market has been marking down execution risk. Any hint that costs remain sticky relative to that 13% to 14% growth outlook would likely keep focus on cash burn and funding mix rather than on revenue alone.
Still, the more uncomfortable part of the Coupang story starts when you look at one pressure point that keeps quietly growing in the background:
There's only one way to know the right time to buy, sell or hold Coupang. Head to Simply Wall St's company report for the latest analysis of Coupang's Fair Value.
Exploring Other Perspectives
One alternate view zooms in on Coupang’s regulatory and tax exposure. The most pessimistic analysts were already baking in revenue of about US$47.2b and earnings near US$1.1b by 2029 before this quarter, yet still saw the stock needing a P/E close to 29.5x. That gap shows how sharply opinions can differ. It may be useful to compare several narratives yourself and decide which assumptions feel realistic.
Explore 5 other Coupang fair value estimates, including one that suggests as much as 8% downside from the current price.
Reach Your Own Conclusion
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Coupang research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Coupang. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Coupang's overall financial health at a glance.
Looking For More Ideas Beyond Coupang?
If Coupang's latest results have you rethinking where to put fresh capital, it can help to line it up against other businesses with different strengths and risk profiles. The Simply Wall St Screener makes it easy to scan for that next idea without sifting through hundreds of tickers by hand.
- For investors hunting for potentially overlooked value stories with strong fundamentals, start with a curated set of 19 high quality undiscovered gems that may not yet be on every radar.
- If capital preservation and steadier profiles matter most to you right now, narrow the field to a 31 resilient stocks with low risk scores that still passes fundamental checks.
- When income is the priority, focus your research on a 7 dividend fortresses that combines higher yields with balance sheet support.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com