


- Applied Digital reported very large year on year revenue growth of 322.4% and approximately US$36b of contracted lease value across 1.41 GW of data center capacity, although the business still recorded a net margin of 53% loss and carries substantial funding needs for about 800 MW of additional buildout.
- The firm is expanding high performance computing hosting and AI focused leases while taking on higher operating costs, interest expense and a roughly US$6.4b debt load. This puts financing terms and execution on its construction pipeline at the center of its long term economics.
- Next, the focus turns to how Applied Digital's heavy use of long term hyperscaler leases and related financing demands could reshape its investment narrative.
Applied Digital Investment Narrative Recap
To own Applied Digital, you need to believe the long term AI and high performance computing demand justifies a heavily leveraged build first model. The main near term catalyst sits in the construction timetable for the roughly 600 megawatts management aims to bring online over the next year and in how smoothly those sites move from spend to revenue producing capacity.
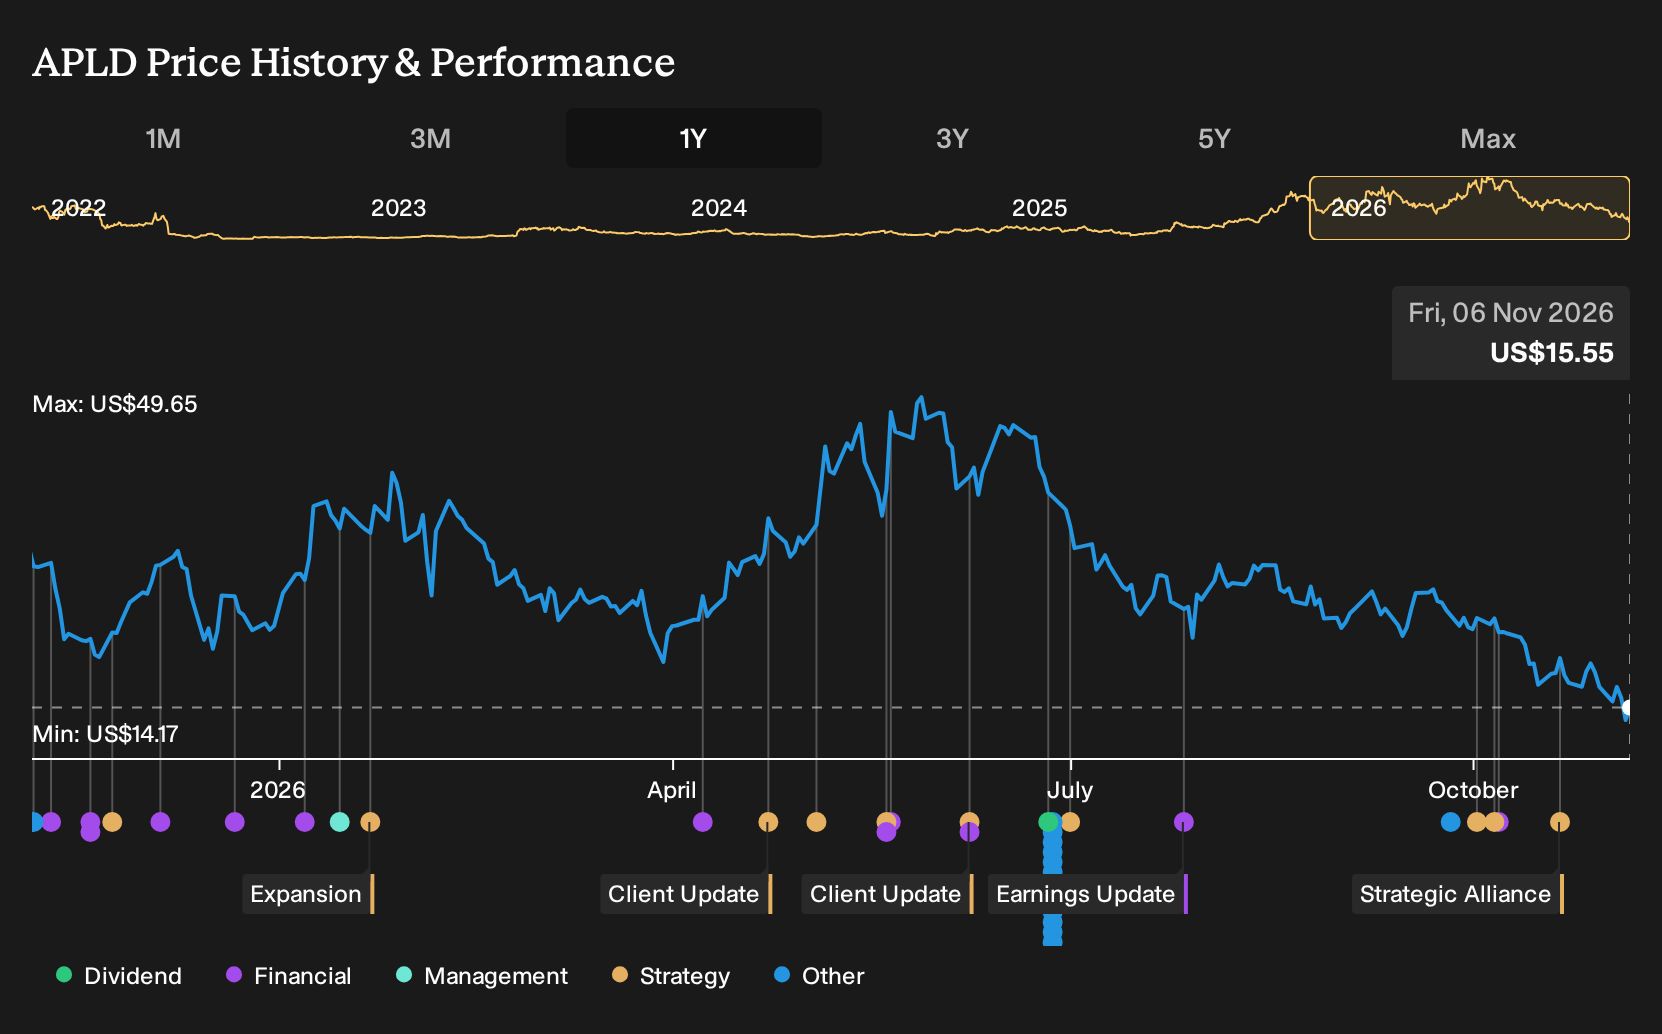
The biggest risk is still funding and servicing the remaining 800 megawatts of planned buildout while already carrying about US$6.4b of debt and a 53% net loss margin. The recent share price pop around competitor funding does not change that financing dependency in a meaningful way.
The most relevant recent development for this story is management securing financing to fund further construction and operations growth, while still needing capital for roughly 800 megawatts of additional capacity. That mix of progress and remaining gap frames the stock reaction to peer funding news and keeps Applied Digital’s next debt deal in sharp focus.
With interest expense already above base rent revenue, the terms on upcoming borrowings matter as much as the headline amount raised. Any higher cost structure would weigh directly on net margins and cash flow from those US$36b of long dated hyperscaler contracts. This is why investors keep tying every catalyst back to funding quality and execution speed.
Applied Digital's current analyst narrative points to revenues of US$3.4b and earnings of US$41.0m by 2029, underpinned by an assumed 57.6% yearly revenue growth rate and a swing in earnings of roughly US$493m from the loss of US$451.8m reported today.
Discover why Applied Digital's fair value indicates a 292% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some readers will focus less on Applied Digital’s construction pace and more on the risk that tighter credit hangs over everything. The most cautious analysts were modeling roughly US$2.2b of revenue and US$164.8m of earnings by 2029 before this news, yet still saw only limited upside. This shows how widely opinions can diverge and how quickly forecasts could shift after fresh funding headlines.
Explore 5 other Applied Digital fair value estimates, including one that suggests it could be worth just $22.15!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Applied Digital research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Applied Digital. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Applied Digital's overall financial health at a glance.
Looking For More Ideas Beyond Applied Digital?
Once you have a view on Applied Digital, it can help to line it up against other opportunities that fit different risk and quality profiles. The Simply Wall St Screener lets you do that quickly so you can see how this stock compares with a broader watchlist of potential candidates.
- For investors who want quality at a discount, scan a focused group of 38 high quality undervalued stocks that combine stronger fundamentals with prices that may not fully reflect them yet.
- If capital preservation ranks high on your list, filter for 31 resilient stocks with low risk scores that score well on stability and financial resilience.
- To widen your research beyond well known tickers, hunt through 19 high quality undiscovered gems that pair solid metrics with relatively low market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com