


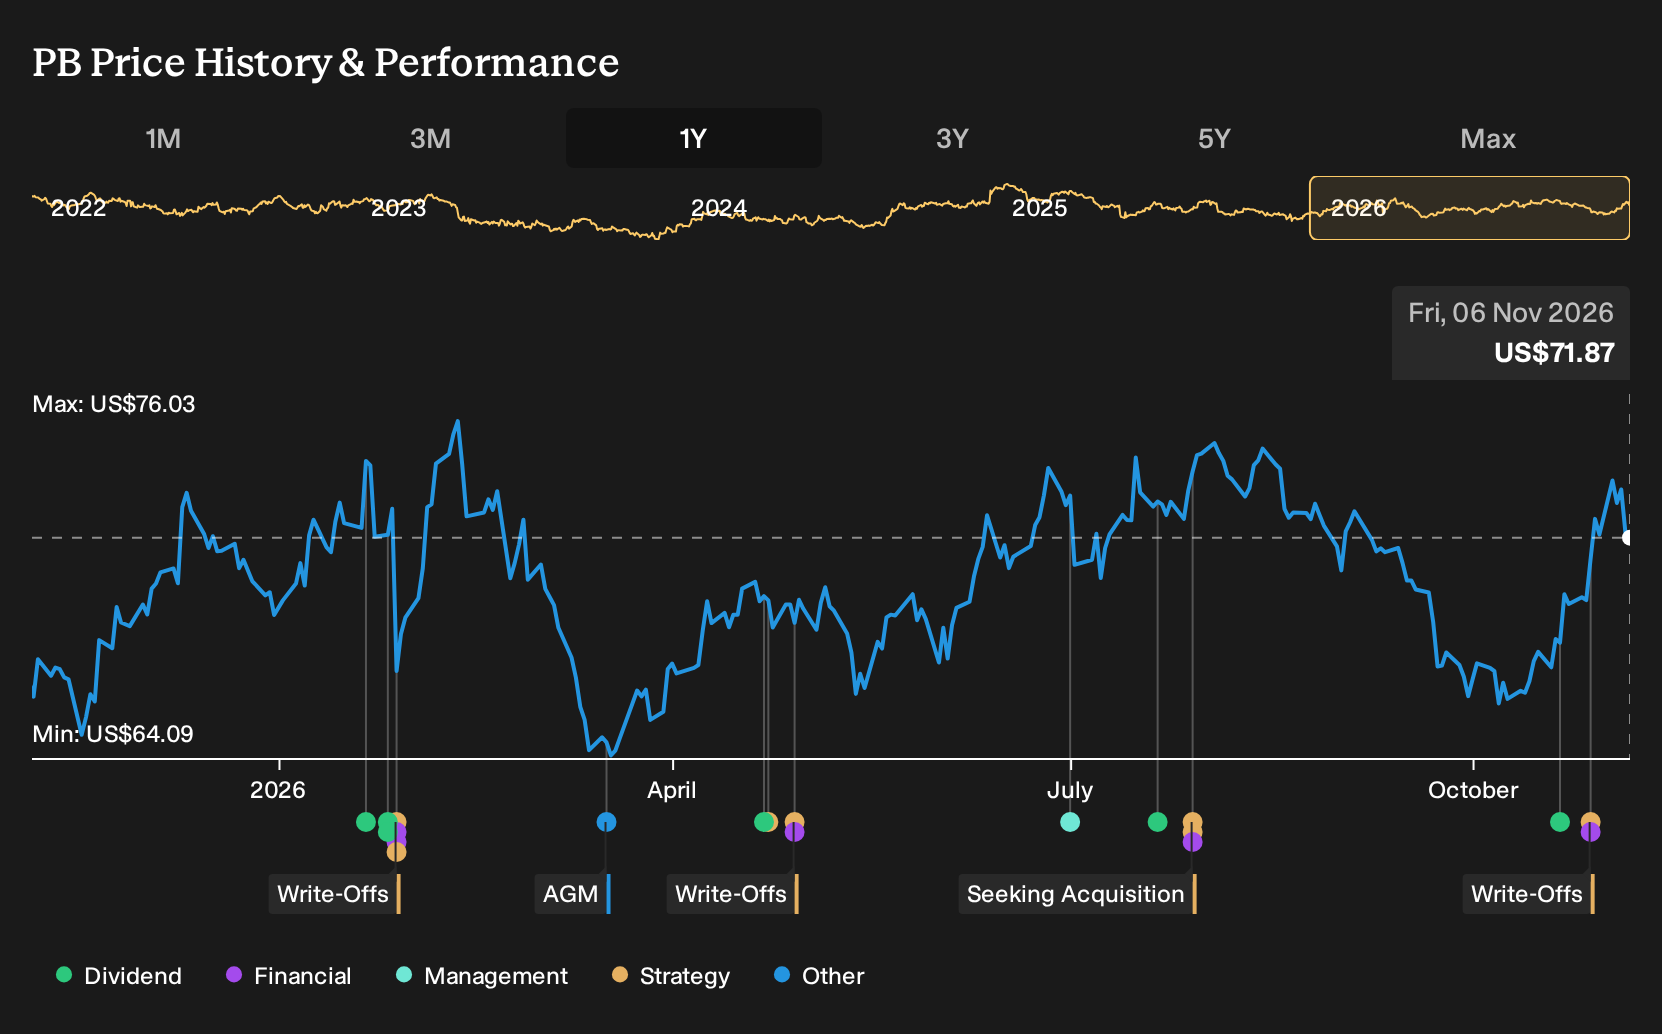
- Prosperity Bancshares reported third quarter 2026 net interest income of US$442.98 million and net income of US$141.46 million, alongside basic and diluted EPS from continuing operations of US$1.18. The company also disclosed lower net charge offs of US$4.44 million compared with the prior year.
- Alongside these results, Prosperity Bancshares continued to reduce its share count, completing US$102.54 million of buybacks covering 1.55% of shares under its 2026 repurchase program.
- The next question for investors is how Prosperity Bancshares' latest earnings mix, including lower net charge offs, may influence its longer term investment narrative.
Scan how Prosperity Bancshares stacks up against other banks returning cash to shareholders by reviewing our hand picked 7 dividend fortresses with resilient income profiles and balance sheets.
Prosperity Bancshares Investment Narrative Recap
To own Prosperity Bancshares, you need to be comfortable with a regional bank focused on Texas and Oklahoma that leans on acquisitions, efficiency and a relatively low cost deposit base to support earnings. The latest quarter fits that story, with higher net interest income and lower net charge offs, but earnings per share from continuing operations remaining below last year.
The key short term swing factor is still how clean credit stays, as prior spikes in charge offs showed how quickly credit costs can move. The biggest risk remains weak organic loan growth in a competitive Texas market, which could keep pressure on revenue momentum even if margins hold up.
The most relevant update for that thesis is the third quarter 2026 earnings release. Net interest income of US$442.98 million and net income of US$141.46 million, alongside nine month net income of US$426.31 million, show Prosperity Bancshares generating earnings capacity that can support its integration plans and technology investments if maintained.
Within that print, the drop in net charge offs to US$4.44 million compared with US$6.46 million a year ago points to a quieter quarter on credit costs after the earlier spike tied to shared national credits. For investors tracking catalysts, ongoing credit stability and consistent net interest income will matter for how the bank funds growth, absorbs competition in Texas and continues returning capital through dividends and buybacks.
Prosperity Bancshares' current analyst narrative points to revenues of US$2.5 billion and earnings of US$1.1 billion by 2029. These figures are built on assumed annual revenue growth of 21.1% and an earnings increase of about US$538 million from US$562.3 million today.
Discover how Prosperity Bancshares' fair value suggests a 13% potential upside to its current price that may not be available for long.
Exploring Other Perspectives
The Simply Wall St Community currently supplies 2 fair value views on Prosperity Bancshares, ranging from roughly US$82 to US$117 per share. This represents a wide spread for just a couple of estimates. Those opinions were formed before the latest earnings, credit trends and buybacks, which provides a reason to explore more recent and contrasting viewpoints.
Explore another Prosperity Bancshares fair value estimate, including one that suggests as much as 62% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Prosperity Bancshares research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Prosperity Bancshares. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Prosperity Bancshares' overall financial health at a glance.
Looking For More Investment Ideas Beyond Prosperity Bancshares?
If you want to put Prosperity Bancshares' results in context, compare it with other opportunities that share traits you care about, whether that is income strength, balance sheet resilience or mispriced quality. The Simply Wall St Screener can help you scan a broader universe efficiently so you can spend more time on judgment and less on raw data work.
- For investors who want a focus on resilience and low downside risk, review a curated 31 resilient stocks with low risk scores that can help you spot businesses where stability is the main attraction.
- If you prefer companies with cleaner finances and room to fund growth internally, filter for firms using the list of solid balance sheet and fundamentals (25 results) and see which ones match your comfort zone on debt and cash.
- When you are hunting for opportunities the market may be overlooking, scan a hand picked 19 high quality undiscovered gems and compare their fundamentals with the expectations baked into current prices.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com