


STAAR Surgical (STAA) is back in focus after its recent earnings release, which showed weaker third quarter sales but a return to profitability over the first nine months of 2026.
STAAR Surgical’s share price has been volatile around these results, with a 1-day share price return decline of 5.65%, a 30-day share price return of 16.34%, and a year-to-date gain of 6.82%, which together point to improving short-term momentum. In contrast, the 1-year total shareholder return decline of 5.05% and the 3-year total shareholder return decline of 24.72% underline how sentiment has weakened over a longer horizon as investors reassess growth prospects and risk around its refractive lens business.
Spot fresh ideas with similar risk reward profiles by scanning our hand-picked 19 high quality undiscovered gems alongside STAAR Surgical after this earnings reset.Bulls point to STAAR Surgical’s return to profit and implied discount to estimated value. Bears focus on sliding quarterly sales and China risk. Which side do the current valuation markers support next?
Most Popular Narrative: 10% Undervalued
On the most followed view, STAAR Surgical screens around 10% below its assessed fair value of $28, versus a last close of $25.21. That gap reflects a story built less on rapid sales expansion and more on margin repair and disciplined cost control.
The Nidau, Switzerland facility is planned to supply all EVO and EVO+ lenses shipped to China by the end of 2026, which would remove China tariffs on those products and has the potential to lift gross margin and net income once higher cost inventory is worked through.
See why 8 investors see STAAR Surgical as 10% undervalued.
Result: Fair Value of $28 (UNDERVALUED)
Still, the narrative can crack if China stays sluggish or if the Nidau shift fails to ease tariff and cost pressures on STAAR Surgical’s margins.
Find out about the key risks to this STAAR Surgical narrative.
Another View: STAAR Surgical Looks Expensive On Sales
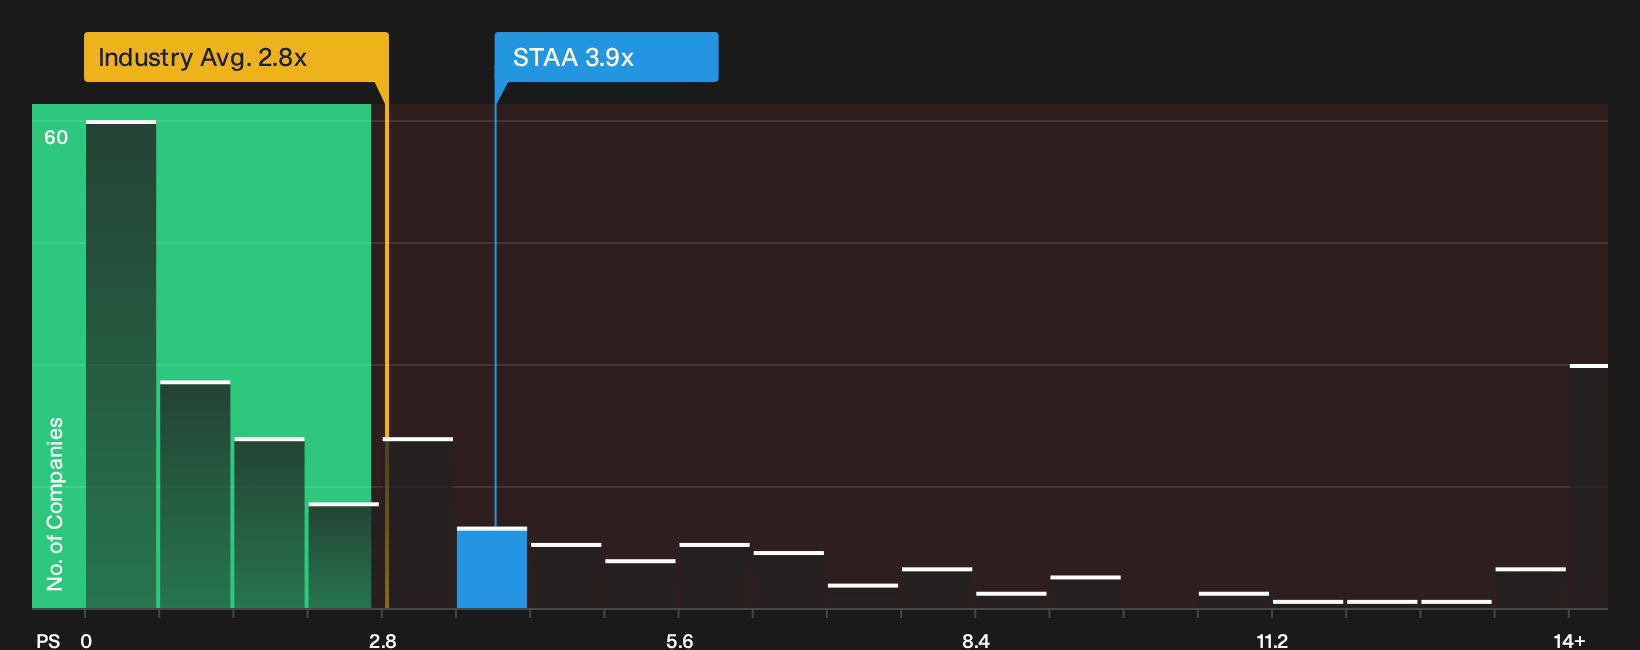
The DCF lens paints STAAR Surgical as roughly 13.5% below an estimate of future cash flow value at $29.16. A different picture appears when using the P/S ratio. The stock trades at 3.9x sales versus a fair ratio of 2.9x and a US Medical Equipment average of 2.8x, which points to valuation risk if growth or margins disappoint.
Put simply, our P/S based view suggests investors are already paying up on revenue for a business where execution still has hurdles to clear. The key question is whether personal assumptions line up more with the cash flow story or the richer sales multiple being paid today. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views remain on whether the current mood toward STAAR Surgical is too cautious or not cautious enough. Move quickly through the numbers and sentiment, then stress test your own thesis against the 3 key rewards and 1 important warning sign.
Looking for more STAAR Surgical sized opportunities?
If you only focus on STAAR Surgical, you risk missing other setups where quality, price and risk line up even better for your portfolio.
- Target companies that combine resilient operations with compelling prices by scanning our hand picked 31 resilient stocks with low risk scores.
- Prioritize financial strength and reduce nasty surprises by running through the list of solid balance sheet and fundamentals (25 results).
- Hunt for mispriced potential before the crowd catches on with the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com