


- DMG MORI reported third quarter 2026 sales of €548.9 million compared with €456.7 million a year earlier. Net income for the period was €23.8 million compared with €114.4 million. For the first nine months, sales were €1,544.3 million with net income of €48.6 million, versus €1,409.2 million in sales and €148.3 million in net income a year before.
- The sharp gap between higher sales and much lower earnings suggests rising costs, pricing pressure or changes in product mix are weighing on DMG MORI’s profitability even as overall activity remains solid.
- This article examines how DMG MORI’s investment narrative is influenced by rising sales alongside a steep decline in reported net income.
Compare DMG MORI’s margin squeeze with peers by scanning 90 robotics and automation stocks, which may be handling cost pressure and pricing power differently.
What Is DMG MORI's Investment Narrative?
The big idea for a shareholder in DMG MORI is simple. You need to believe the machine tools and services platform can keep demand reasonably steady while management works through weaker profitability. The latest quarterly report fits that tension. Sales for both the quarter and nine month period were higher in euro terms, yet earnings for both periods were much lower. That combination keeps the focus squarely on execution, cost discipline and pricing, not on growth stories.
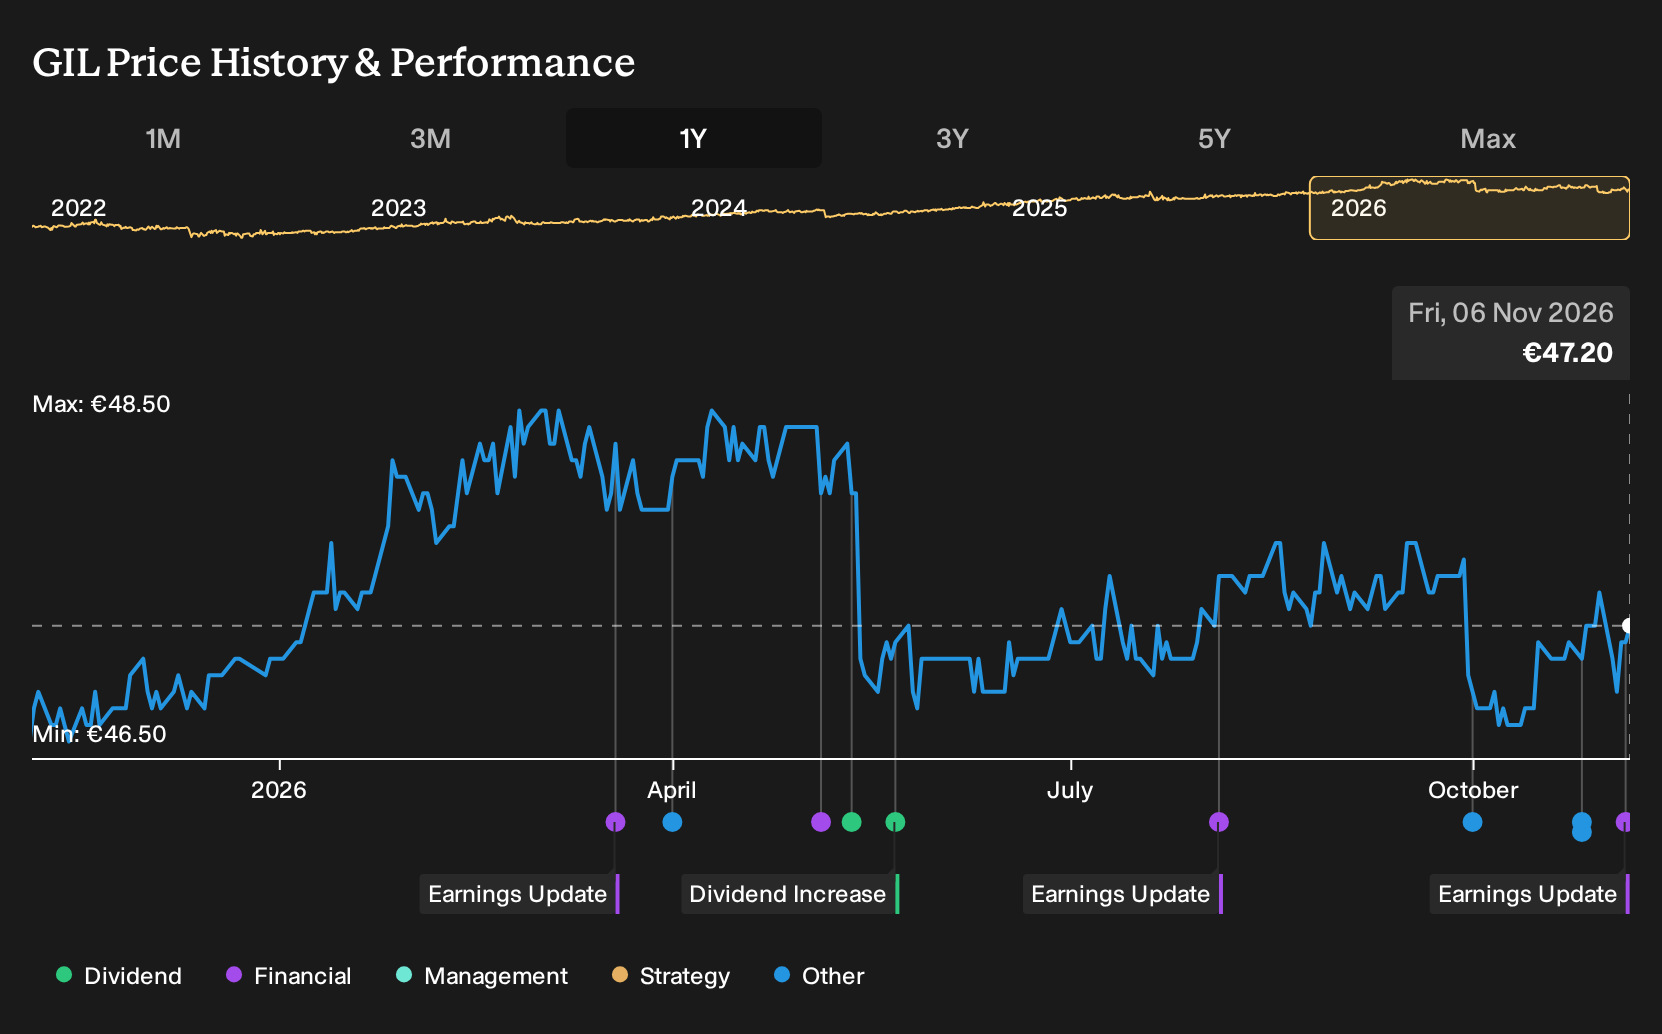
In the short term, the key swing factors look operational instead of macro. Investors will likely watch whether DMG MORI can protect margins in a capital intensive business that depends on complex production, software and after sales support. Recent data showing earnings declining by 1.2% per year over five years, lower net profit margins than last year and a relatively high P/E of 44.8x compared with peers underlines that pressure. The latest results reinforce those existing concerns rather than reset them.
Yet there is a less obvious pressure point sitting in the background that could matter far more if ...
There's only one way to know the right time to buy, sell or hold DMG MORI. Head to Simply Wall St's company report for the latest analysis of DMG MORI's Fair Value.
Decide For Yourself
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so consider your own analysis and judgment.
- A great starting point for your DMG MORI research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for DMG MORI. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate DMG MORI's overall financial health at a glance.
Looking For More Ideas Beyond DMG MORI?
If this DMG MORI story has you rethinking portfolio balance, it can help to widen the lens and see how other businesses stack up on different qualities such as value, balance sheet strength, and income potential. The Simply Wall St Screener can surface a range of stocks that match the specific traits you care about most.
- For investors who like a margin of safety on price, review companies flagged as potential value opportunities through the 222 high quality undervalued stocks.
- If capital protection and financial resilience matter most to you, filter for companies with robust finances using the list of solid balance sheet and fundamentals (192 results).
- For those searching beyond the usual large caps, scan for quality businesses that are still flying under the radar via the 582 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com