


Perella Weinberg Partners (PWP) reported a stronger third quarter along with a fresh dividend decision, posting US$17.56 million in net income and affirming a US$0.07 quarterly payout to Class A shareholders.
Perella Weinberg Partners shares closed at US$13.68, and despite the stronger third quarter and affirmed dividend, the stock has fallen 12.7% over the past month and 22.1% year to date on a share price basis. That short term weakness contrasts with a 3 year total shareholder return of 38.9%, which suggests earlier investors have still seen meaningful gains even as recent price momentum has cooled.
Spot opportunities other investors might be missing by comparing Perella Weinberg Partners with a curated 38 high quality undervalued stocks that pairs resilient cash flows with stronger balance sheets.Perella Weinberg Partners has delivered a stronger quarter while the share price has pulled back sharply, leaving a gap between the current US$13.68 level and analyst targets. Is that discount justified once you line it up against fair value estimates?
Price-to-Earnings of 32.8x: Is it justified?
Perella Weinberg Partners trades at a P/E of 32.8x, which looks expensive against its peer group average of 25.4x, even though it sits slightly below the broader US Capital Markets industry on 36.3x.
The P/E ratio compares the share price to earnings per share and, for an advisory firm like Perella Weinberg Partners, it often reflects how much investors are willing to pay for its fee pool and advisory pipeline. A higher multiple usually signals that the market is building in stronger or more resilient profitability, while a lower one suggests more caution around future earnings power.
Here, the stock carries a richer P/E tag than its closer peer set even though return on equity is described as low at 11.8% and earnings over the past year went backwards by 28%, with margins slipping from 6.2% to 4.3% and a large one off loss of $18.5m weighing on reported results. That combination points to investors paying up for a business that has become profitable over the past 5 years, growing earnings by 13.2% per year, but with more mixed recent earnings quality.
Against the wider industry, the P/E looks more restrained, with Perella Weinberg Partners on a lower multiple than the US Capital Markets average of 36.3x. This suggests the market is still pricing the stock with less optimism than the broader group, even as revenue is forecast to grow 20.1% per year, faster than both the US market at 13.2% and the 20% high growth marker referenced in forecasts.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 32.8x (ABOUT RIGHT)
Still, the story can change quickly if advisory deal volumes soften further or if that 32.8x P/E compresses as investors reassess the quality of Perella Weinberg Partners’ earnings.
Find out about the key risks to this Perella Weinberg Partners narrative.
Another View On Perella Weinberg Partners: Cash Flows Send A Different Signal
The P/E picture paints Perella Weinberg Partners as roughly in line with the broader industry, but the SWS DCF model takes a much tougher stance. On that framework, the estimated future cash flow value sits at US$6.62 per share while the market price is US$13.68, which points to the shares trading well above that cash flow based estimate. If one model says "about right" and another flags potential overvaluation, which lens do you give more weight to in your own process?
Look into how the SWS DCF model arrives at its fair value.
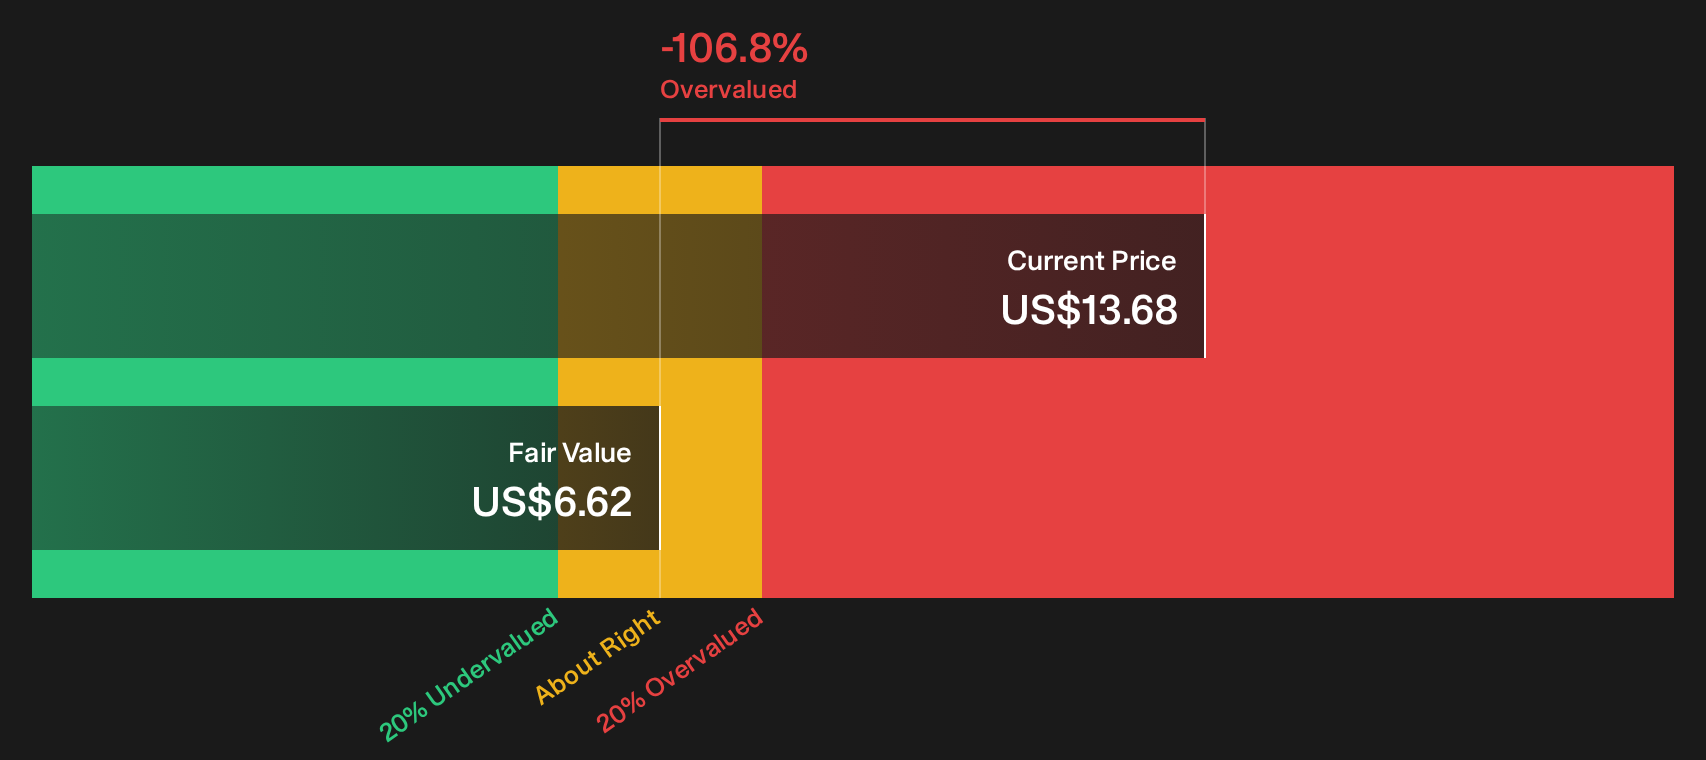
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Perella Weinberg Partners for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 38 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
With Perella Weinberg Partners presenting mixed signals on valuation, sentiment, and cash flows, the key question is how you weigh the balance of opportunity and risk. Act promptly, review the key data points, and stress test your own thesis against the 2 key rewards and 1 important warning sign.
Looking for more Perella Weinberg Partners sized investment ideas?
If Perella Weinberg Partners has sharpened your focus on valuation and earnings quality, do not stop there. The next step is widening your opportunity set with a curated set of screeners that spotlight different angles of risk and reward.
Use the Simply Wall Street Screener to spot focused ideas before they hit the crowd. Each list below applies clear, consistent rules so you can quickly compare companies without getting lost in noise.
- Target steadier capital preservation and avoid lopsided downside by reviewing a 31 resilient stocks with low risk scores that concentrates on businesses with more resilient risk profiles.
- Hunt for quality at a discount by scanning a 19 high quality undiscovered gems that filters for strong fundamentals the broader market may not be paying attention to yet.
- Prioritise stronger financial footing by working through a list of solid balance sheet and fundamentals (25 results) that focuses on companies with healthier leverage and liquidity support.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com