


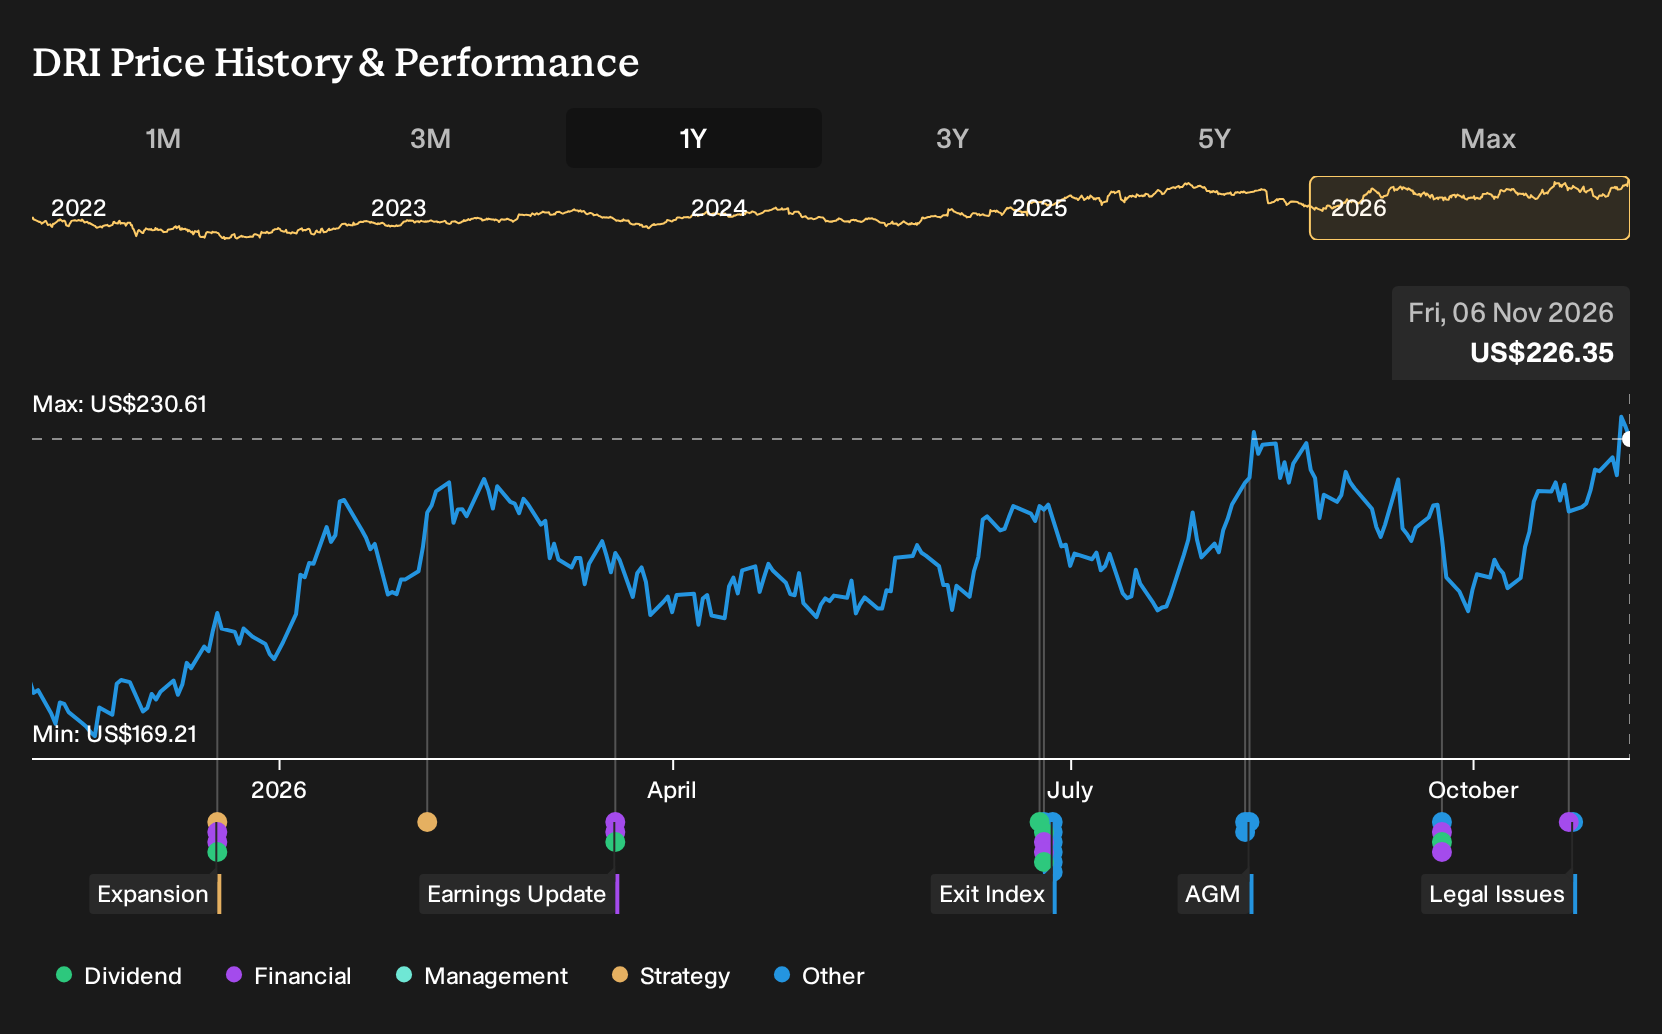
Investors who held Darden Restaurants over the past year are up 31.2%, including dividends. That outcome looks simple on a chart, yet it came after early research split between a bullish view that Uber Direct, smaller formats and menu promotions could support earnings, and a bearish case that legacy formats and slower digital progress might cap returns. If you had capital to put to work on 2025-11-06, which of those competing stories would you have trusted?
If the move has made Darden Restaurants harder to judge, start where the gap is still open and scan 38 high quality undervalued stocks.
The Two Darden Restaurants Stories Investors Had To Weigh
The shares cost US$178 at the start of the period, and anyone looking at Darden Restaurants then had to decide which story felt more realistic.
The bullish narrative pointed to a Fair Value of US$225, a price that would only make sense if assumptions such as 5.5% revenue growth and a 10.0% profit margin played out, helped by Uber Direct delivery and smaller restaurant formats.
The bearish view anchored on a Fair Value of US$157, based on concerns that heavy reliance on traditional dining formats and slower digital adoption could keep pressure on margins and demand.
What The Results Changed For The Darden Restaurants Debate
The biggest new fact for Darden Restaurants was revenue of US$3,200.3m in Q1 2027 compared with US$3,044.7m in Q1 2026. This supported the bullish focus on demand and new formats. The catch is that earnings moved the other way. Net income slipped and net margin declined from 8.5% to 7.3%, which challenged the cleaner profit story. Overall, the evidence cut both ways.
The key lesson is simple. When a thesis leans on margin expansion, do not just track sales. Watch whether net margin and profit per share move in the same direction as the growth story you are being sold.
What Today's Darden Restaurants Price Already Assumes
Darden Restaurants now trades at US$226 after a 31.2% total return over the past year. The selected Narrative’s Fair Value sits below the current price, so that framework treats the recent run as pricing in a fairly optimistic path.
The Narrative centers on weekday lunch traffic at Olive Garden, disciplined pricing, cost control and new unit economics. A buyer today has to judge whether lunch traffic, pricing roughly in line with 3% inflation and new openings can all hold together without squeezing restaurant level margins.
"Although Darden Restaurants is leaning on brand specific menu and daypart initiatives at Olive Garden to revive weekday lunch, the reported deterioration of weekday lunch traffic by hundreds of basis points versus pre COVID creates a risk that marketing around soup, salad and breadsticks and the new lunch platform test in FY2027 fails to restore traffic density."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
Before The Next Story Makes Headlines
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 41% below our estimate - targets faster brownfield tieback projects using standardized subsea systems and long duration services contracts.
- Company 2 - 40% below our estimate - captures AI related air cargo and compliance work as automation reshapes freight forwarding and brokerage workloads.
- Company 3 - 49% below our estimate - expands an asset light hotel network while layering on a fast growing retail ecosystem for guests.
Three companies from the same screener. Open the full list of 25 financially solid companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com