


BeOne Medicines has turned in a strong share price run in recent years, which puts fresh focus on whether its current valuation can still be explained by its earnings power. After that kind of climb, the question for anyone looking at the stock is how well the price lines up with what the business earns today.
- Over the past 3 years the stock has returned 104.4%, which puts real weight on the question of how much earnings strength is already reflected in the share price.
- The FDA Priority Review for the BRUKINSA and rituximab combination in first line mantle cell lymphoma may support expectations for future profit streams, which in turn feeds directly into how investors think about what they are willing to pay for those earnings.
- Your read on BeOne Medicines is one view; the desks covering it have another. See what analysts think BeOne Medicines's shares could be worth.
The issue now is whether BeOne Medicines' current share price around US$406.96 is adequately backed by the earnings the company is generating.
If you want a broader starting point alongside BeOne Medicines, a focused stock screen built around 38 high quality undervalued stocks can help you line up other ideas against this earnings story.
Does BeOne Medicines Look Pricey on Earnings?
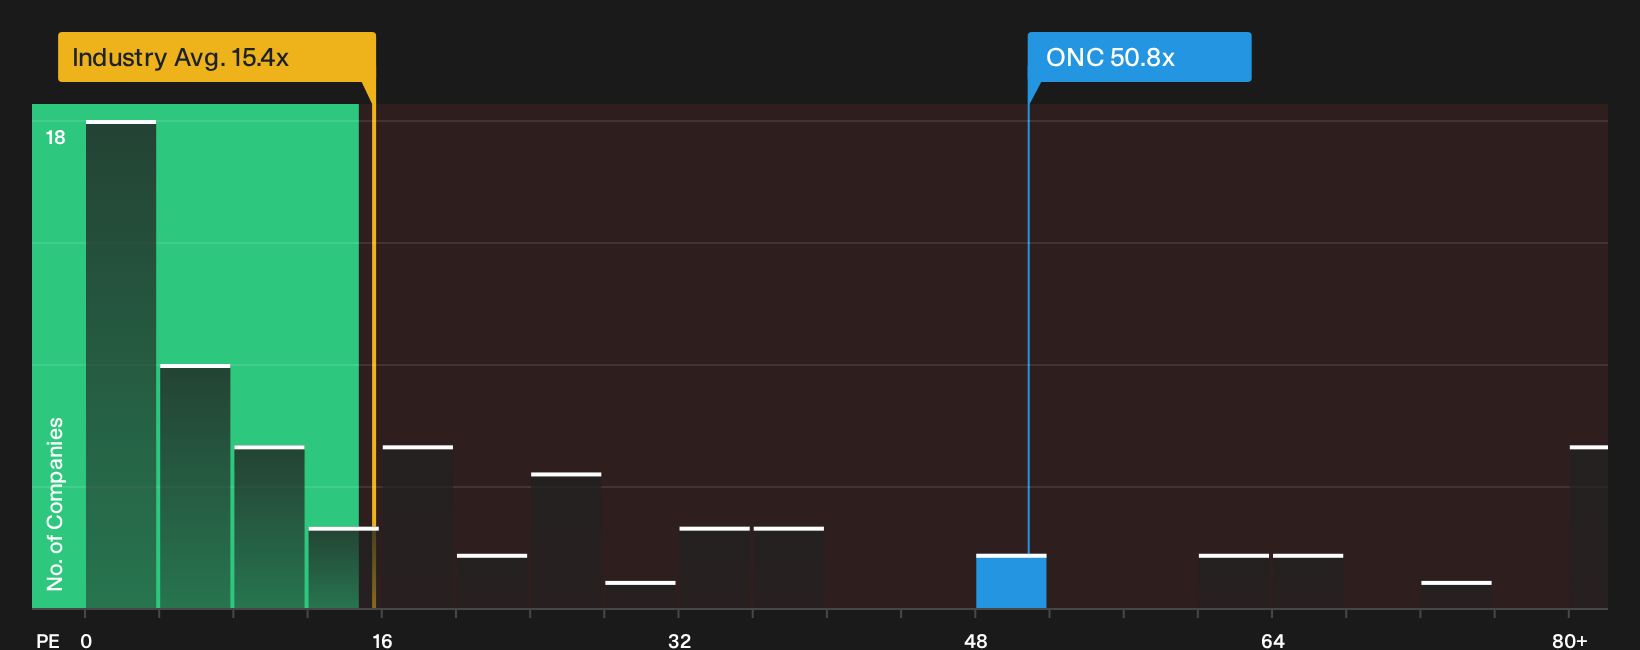
The P/E ratio is a useful anchor for BeOne Medicines because earnings are a key focus for investors in profitable biopharma groups. On this yardstick, the stock trades on about 50.8x earnings, which sits slightly above the 48.4x peer average and far higher than the wider Biotechs sector on roughly 15.4x. That points to a valuation that already embeds a richer earnings tag than many similar companies in the space.
The tailored fair P/E multiple implied by the valuation model, which factors in BeOne Medicines' growth profile, profitability, size and risk, comes in below the current 50.8x. Because the FDA Priority Review for the BRUKINSA and rituximab combination has already sharpened expectations, the premium P/E suggests the recent optimism is reflected in the price and leaves less room for disappointment. On this framework the stock appears overvalued on earnings, so any new position would require a strong conviction in the durability and quality of future profit streams to feel comfortable at this level. Explore the numbers behind BeOne Medicines's P/E valuation.
The BeOne Medicines Narrative: What Would Justify Today's Price?
For BeOne Medicines, Simply Wall St Narratives pick up where the P/E puzzle leaves off. They spell out what growth, margins and earnings path would need to hold for the shares to be worth materially more or less than today. Each narrative ties a fair value to a specific mix of potential catalysts and risks so you can track over time which version of BeOne Medicines' story is actually unfolding on the Community page.
Bullish and bearish voices on BeOne Medicines are reading the same oncology franchise very differently, with one side seeing upside and the other focusing on execution risk.
Bull case: 20% undervalued
"The emerging B cell franchise stack of BRUKINSA, newly approved BEQALZI in relapsed or refractory mantle cell lymphoma, and the BTK degrader tacabrutideg, which is targeting an accelerated approval filing and a head to head Phase 3 against pirtobrutinib, creates room for combined and sequential regimens that extend treatment lines and support higher aggregate revenue and gross profit per patient journey…"
Discover why this Narrative puts BeOne Medicines at 20% undervalued.
Bear case: 6% overvalued
"While BeOne Medicines highlights a shift from a hematology-centric profile to a wider oncology portfolio with several solid tumor assets moving quickly toward pivotal trials, the decision to sustain mid teens operating expense growth into 2027 to fund this build out risks outpacing any incremental contribution from new regimens and could hold back further margin expansion and free cash flow…"
Explore why this Narrative puts BeOne Medicines at 6% overvalued.
One more question for BeOne Medicines before you close the file
You have a picture of what BeOne Medicines costs today, but professional coverage also sketches out where revenue, margins and earnings could sit a few years from now. Explore where analysts expect BeOne Medicines to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com