


Ultra Clean Holdings (UCTT) has just swung from loss to profit, reporting third quarter 2026 earnings alongside fresh guidance for the next period that points to higher expected revenue and earnings per share.
Ultra Clean Holdings has had a volatile stretch, with the share price falling 40.03% over the past 30 days and 50.01% over 90 days. At the same time, the year-to-date share price return of 50.55% and 1-year total shareholder return of 57.83% suggest longer term momentum. Wednesday's 10.56% one-day share price jump is now attempting to rebuild that momentum around the earnings rebound and fresh guidance.
Scan beyond Ultra Clean Holdings and line up other semiconductor plays reacting to wafer equipment demand with our hand picked 53 AI infrastructure stocks in one place.
Bulls see Ultra Clean Holdings as a recovering wafer equipment supplier with fresh profit momentum, while bears point to the sharp recent share price slide. Which side does the valuation math lean toward now?
Most Popular Narrative: 64% Undervalued
Based on the most followed narrative, Ultra Clean Holdings is priced well below its fair value estimate of $112.83 compared with the last close at $41.13. This puts the focus firmly on whether the growth story can actually play out.
The main thing that has to go right is Ultra Clean Holdings successfully scaling its global manufacturing footprint and UCT 3.0 co-innovation model so that higher industry wafer fab equipment spending and new fab ramps translate into sustainable revenue and margin gains.
See why 23 investors see Ultra Clean Holdings as 64% undervalued.
Result: Fair Value of $112.83 (UNDERVALUED)
Still, the Ultra Clean Holdings story can break if wafer fab equipment spending forecasts reset lower or if ongoing capacity expansion strains cash flow for longer than expected.
Find out about the key risks to this Ultra Clean Holdings narrative.
Another View: What Ultra Clean Holdings Looks Like On Earnings
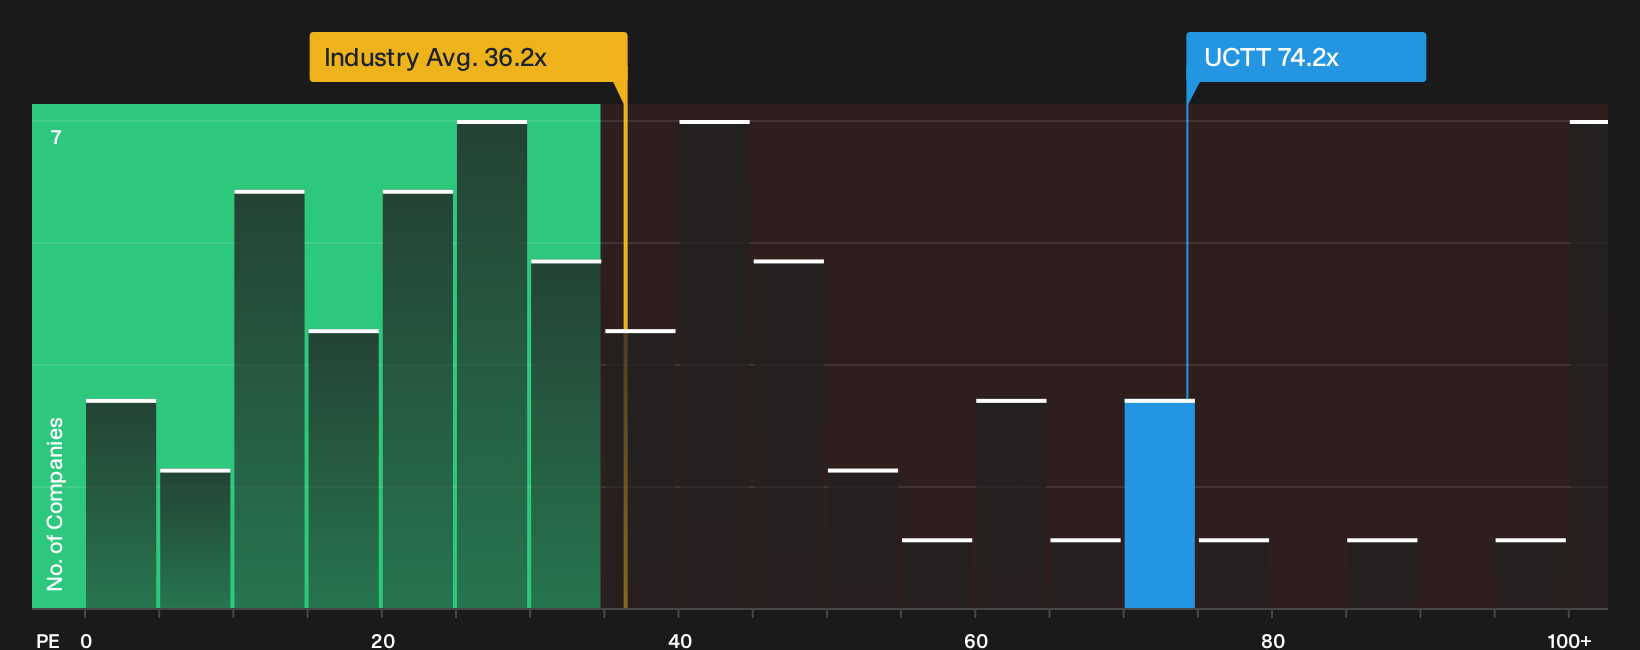
Zooming out from fair value estimates, the current earnings multiple paints a very different picture for Ultra Clean Holdings. The stock trades on a P/E of 74.2x, compared with a fair ratio of 44.5x, a peer average of 68.9x and a US Semiconductor sector level of 36.2x.
That gap suggests investors are already paying a premium for UCTT relative to both its own fair ratio and the wider industry. This raises a simple question: Is the recent earnings rebound strong enough to keep justifying that kind of premium if sentiment cools again?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Ultra Clean Holdings can make the story feel split, so move fast, review both sides of the data, then weigh the 2 key rewards and 2 important warning signs.
Looking for more Ultra Clean Holdings sized ideas?
If Ultra Clean Holdings has you thinking bigger about your portfolio, do not stop here. Powerful tools are a click away that can surface fresh stocks with very different risk and reward profiles, tailored to the kind of edge you want to build into your next move.
- Target value hunters and scan a curated pool of companies that look mispriced on quality and fundamentals through the 38 high quality undervalued stocks.
- Strengthen your core holdings by filtering for companies with robust finances and cleaner balance sheets using the list of solid balance sheet and fundamentals (25 results).
- Spot potential up and comers before the crowd focuses on them by working through the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com