


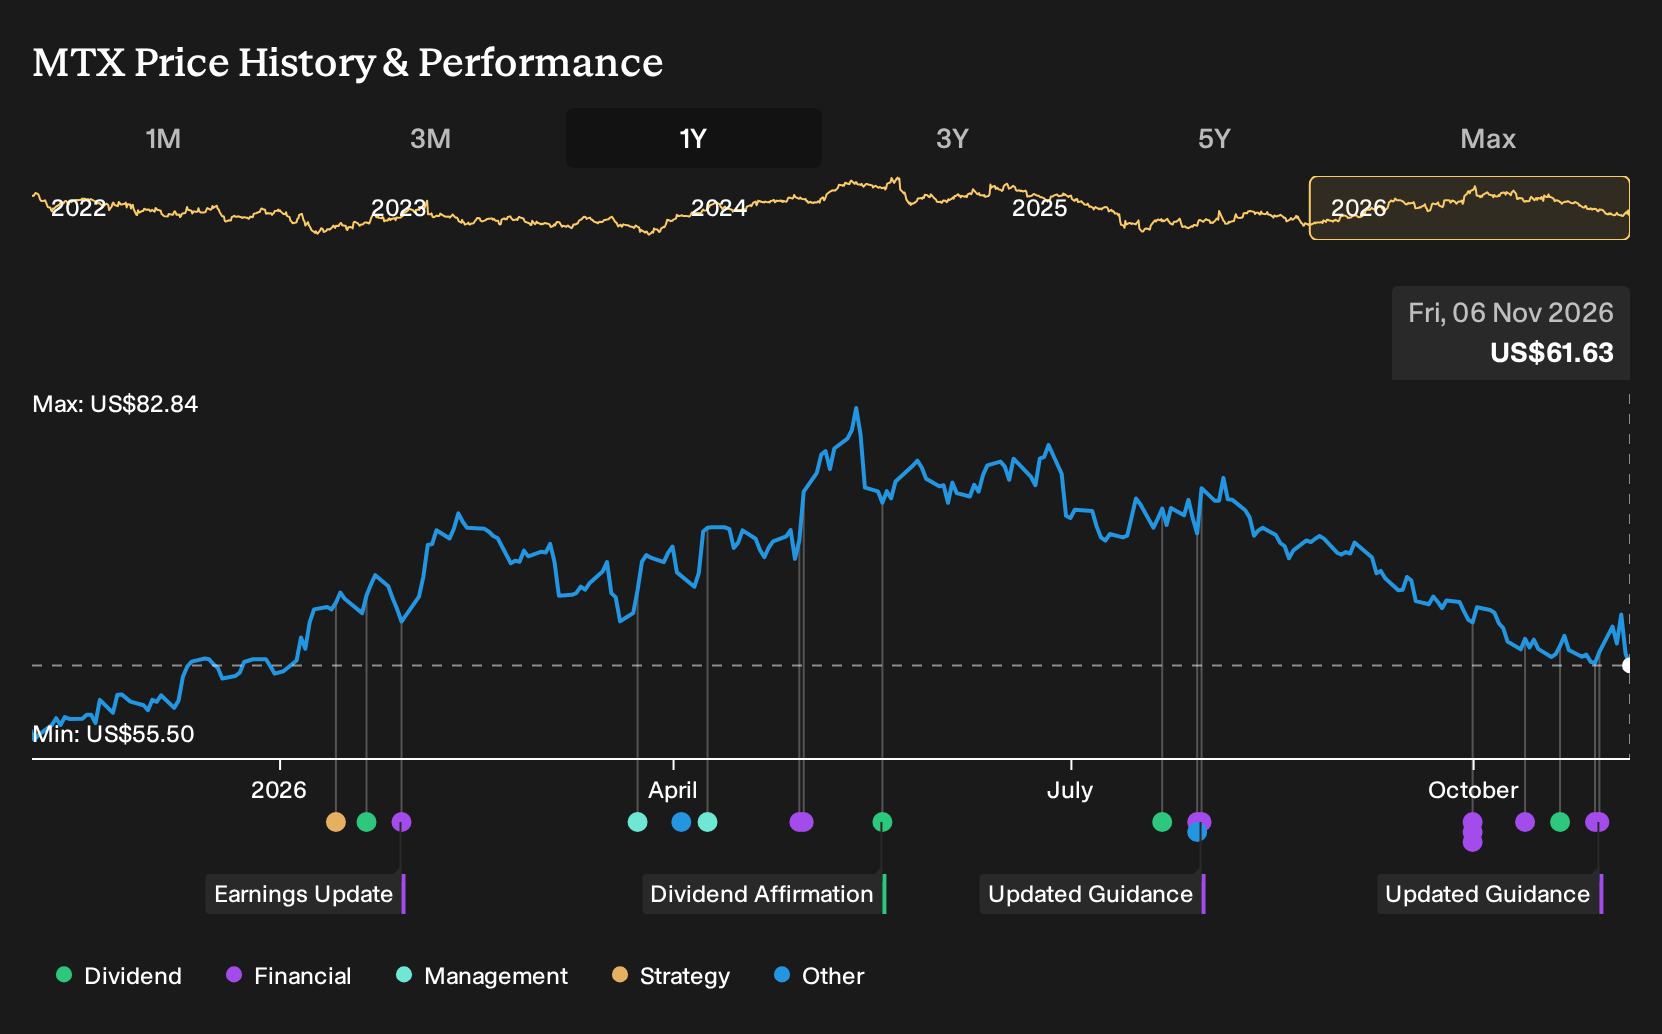
- Minerals Technologies reported third quarter 2026 results with sales of US$554.9 million and net income of US$42.7 million, and issued fourth quarter guidance calling for about US$525 million in sales, operating income of US$60 million to US$63 million, and EPS of US$1.15 to US$1.20.
- The nine month period showed higher sales of US$1,650.2 million but a loss of US$104.7 million, so investors now have to reconcile that earnings drag and the talc related charge backdrop with management’s relatively firm near term EPS outlook.
- We will now look at how Minerals Technologies' latest EPS guidance and mixed profit picture could influence its longer term investment narrative.
Scan how Minerals Technologies’ latest guidance compares with peers by reviewing a curated list of solid balance sheet and fundamentals (25 results) that may be handling earnings swings with different balance sheet profiles.
Minerals Technologies Investment Narrative Recap
To own Minerals Technologies, you need to believe the mineral based product portfolio can offset legal and energy cost headwinds and turn its project pipeline into steadier earnings. The recent quarter showed positive profit from continuing operations, while the nine month loss and talc related charge still hang over the story. The key short term catalyst is management proving that current pricing, cost control and volume mix can support the guided EPS range. The biggest near term risk remains further pressure from talc litigation or prolonged margin drag if input costs stay misaligned with contract resets.
The fresh fourth quarter 2026 guidance is the clearest operational milestone to watch. Management is calling for about US$525 million of sales, US$60 million to US$63 million of operating income, and EPS of US$1.15 to US$1.20. That outlook sits against a year to date loss of US$104.7 million, which keeps execution risk front and center. If Minerals Technologies hits its profit targets while dealing with freight, energy and legal burdens, confidence in catalysts such as specialty minerals, PFAS solutions and sustainability linked products could improve. If it falls short, concerns around earnings quality and cash generation likely stay elevated.
Minerals Technologies' narrative projects US$2.4b revenue and US$600.8 million earnings by 2029. This implies revenue growth of 4.3% per year and an earnings increase of about US$668 million from earnings today of a US$67.2 million loss.
Uncover why Minerals Technologies' fair value indicates a 48% potential upside to its current price, which could narrow quickly as sentiment catches up.
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community range from about US$60 to nearly US$155 per share, so views on Minerals Technologies are spread widely. That kind of gap reflects how differently people weigh talc litigation, energy costs, and the PFAS or sustainability product pipeline. Treat it as a prompt to test several contrasting viewpoints yourself.
Explore 3 other Minerals Technologies fair value estimates, including one that suggests potential upside of up to 151% from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Minerals Technologies research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Minerals Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Minerals Technologies' overall financial health at a glance.
Looking for more investment ideas beyond Minerals Technologies?
Once you have a view on Minerals Technologies, it can help to line it up against other opportunities that fit different risk and income profiles. The Simply Wall St Screener lets you quickly filter for stocks that match the type of balance sheet strength, value tilt, or dividend focus you want in your portfolio.
- If you want potential mispricing with quality to back it up, compare Minerals Technologies with a 38 high quality undervalued stocks that combine robust fundamentals with discounted share prices.
- For investors who care most about capital preservation, weigh it against a 31 resilient stocks with low risk scores that show resilient business profiles and lower risk scores.
- If your priority is ongoing income, set Minerals Technologies alongside a 7 dividend fortresses that offer higher yields while still passing fundamental checks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com