


Apogee Enterprises has delivered a solid share price run, and the question now is whether that move is fully supported by the earnings power of the business. With the stock changing hands at US$45.77, investors are weighing how much of its profit profile is already reflected in that tag.
- Apogee Enterprises has returned 36.7% over the past year, which puts more pressure on the current earnings multiple to justify the recent gains.
- The company’s focus on architectural glass and framing systems ties its earnings potential closely to project execution, contract quality, and how efficiently those projects convert into cash flow over time, which can matter a lot for what investors are willing to pay for each dollar of profit.
- There is a second opinion on Apogee Enterprises worth weighing. See what analysts think Apogee Enterprises's shares could be worth.
For investors, the debate is whether Apogee Enterprises’ current share price is well aligned with what its earnings can reasonably support.
While you consider whether Apogee Enterprises’ 36.7% one-year return is fully backed by its earnings, it may be helpful to compare it with a focused list of 38 high quality undervalued stocks.
Does Apogee Enterprises Look Undervalued on Earnings?
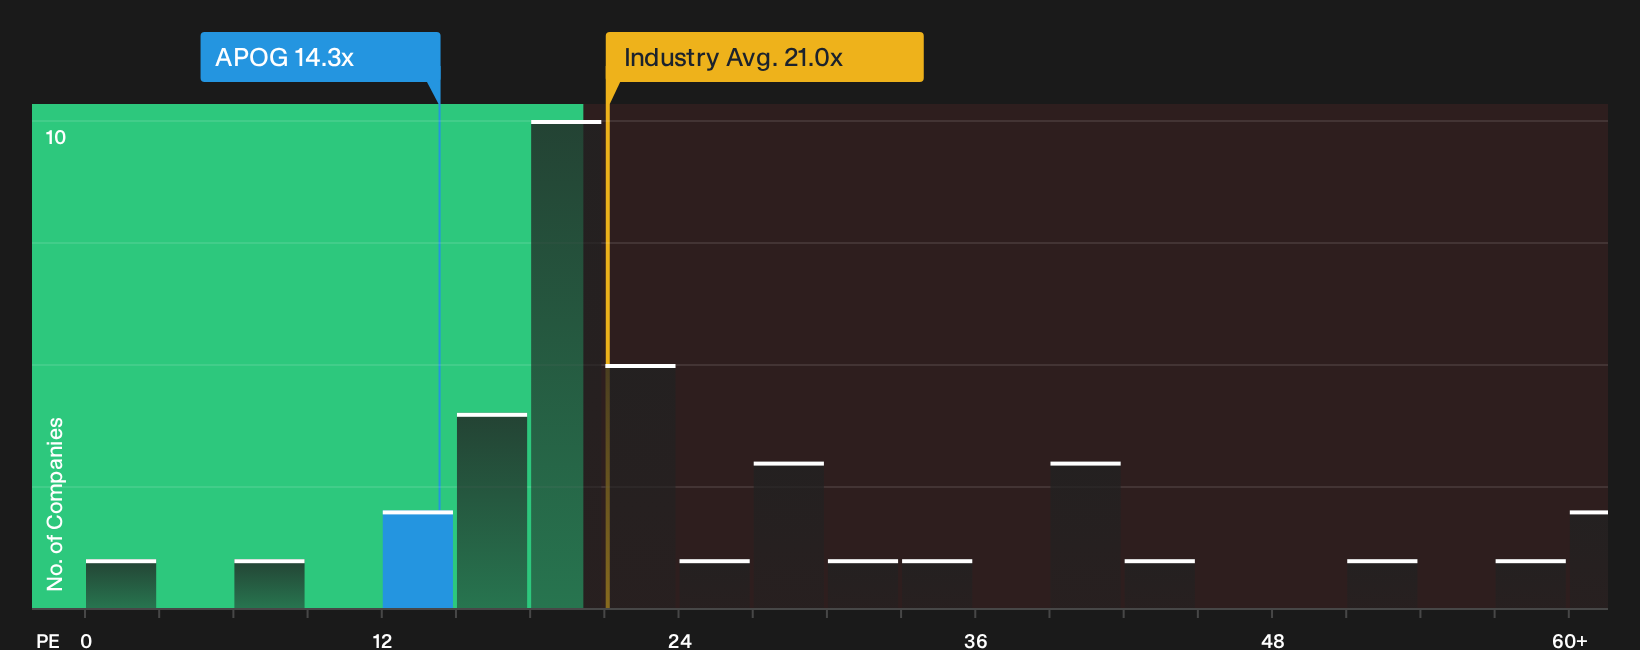
For Apogee Enterprises, the P/E ratio is a useful yardstick because earnings are a central driver of how investors frame this kind of project based business. At a current P/E of 14.3x, the stock trades at a discount to the broader Building industry, where the average is about 21.0x, and also sits below the peer group average of roughly 25.0x.
The fair P/E multiple implied by Apogee Enterprises’ own earnings quality, risk profile and size comes out higher than where the shares trade today. This points to the stock being undervalued on this metric. That gap suggests the market is assigning a lower price to each dollar of profit than this framework would imply, so any investor weighing the shares against other options may want to understand whether the business prospects, balance sheet and project pipeline explain the shortfall or leave room for a potential re rating. Explore the numbers behind Apogee Enterprises's P/E valuation.
The Apogee Enterprises Narrative: What Would Justify Today's Price?
Apogee Enterprises' current valuation puzzle sets up the role of Simply Wall St Narratives, which map out what kind of future for revenue, margins and earnings would need to occur for the stock to trade meaningfully higher or lower than it does today on the market. Each narrative turns that fair value view into a specific, trackable thesis about how the business develops over time. You can follow these narratives on Simply Wall St's Community page as new information arrives.
One of the top community narratives on Apogee Enterprises: 10% undervalued
"The main factor that has to go right is continued execution on productivity and cost reduction programs, such as the Apogee Management System and Project Fortify Phase 2…"
Discover why this Narrative puts Apogee Enterprises at 10% undervalued.
Apogee Enterprises: why the story is not just about the current share price
Price and earnings only tell part of what you need to know about Apogee Enterprises, since our checks have also flagged areas of concern that deserve your attention before you commit fresh capital. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com