


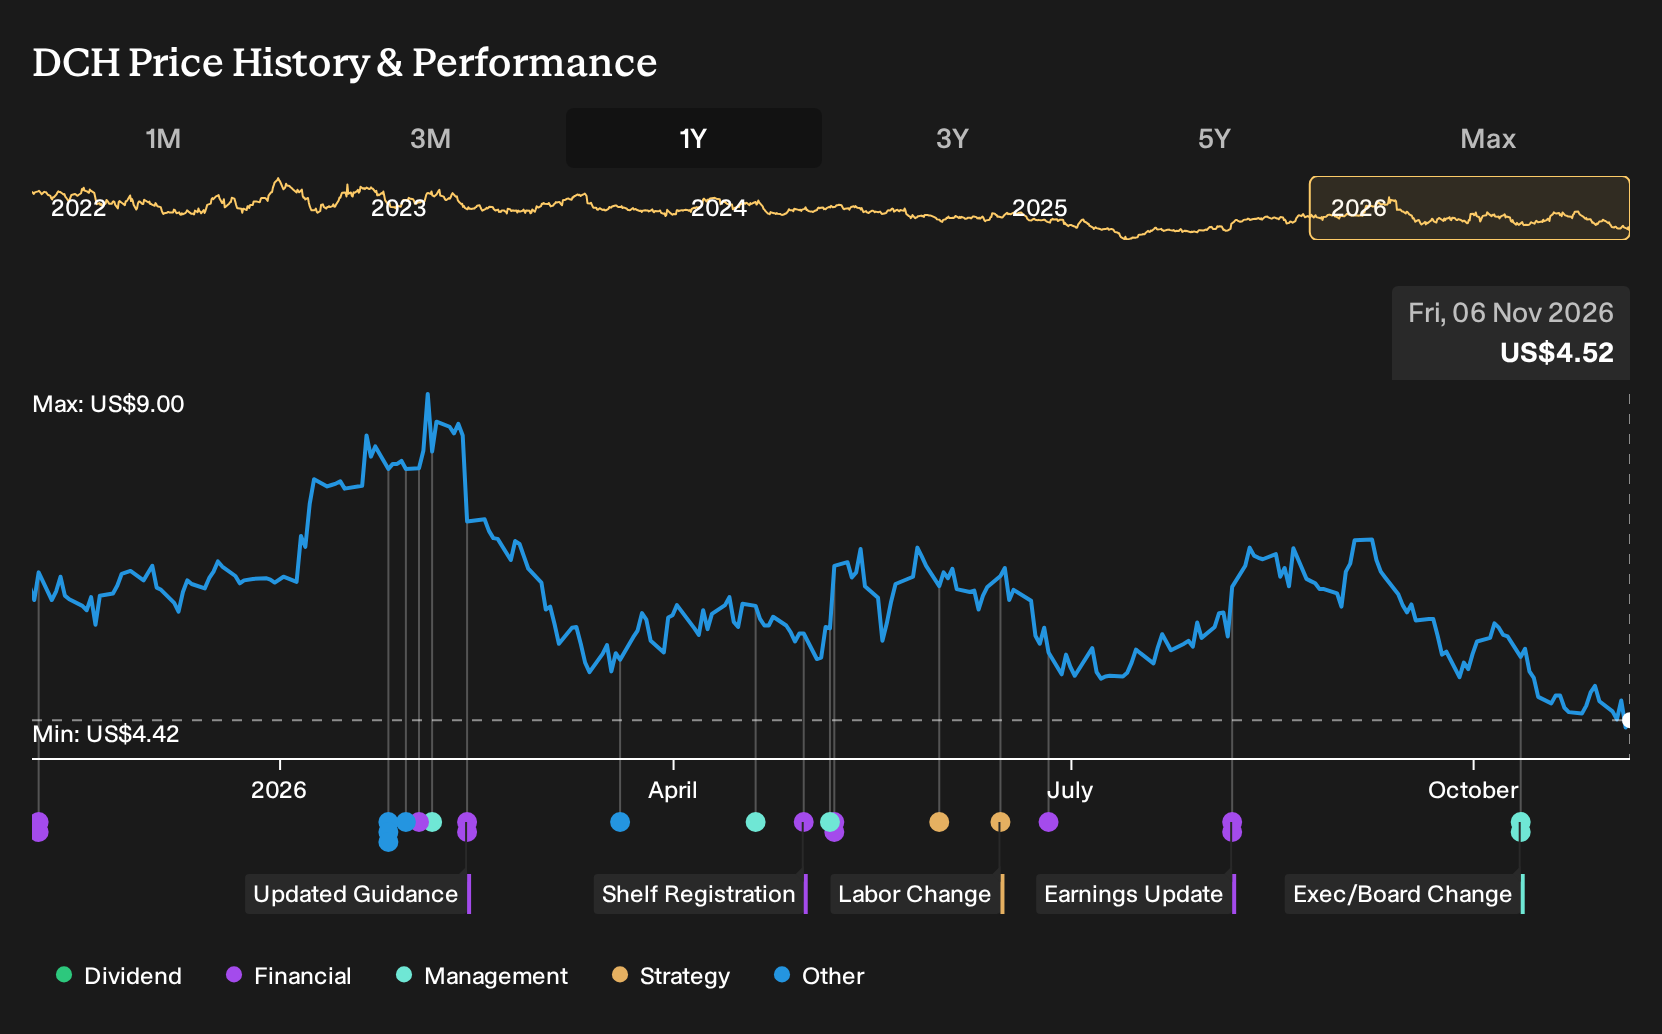
- Dauch Corporation reported Q3 2026 results that showed sales of US$2.91b compared with US$1.51b a year earlier, alongside a net loss of US$45.3 million and reduced full year EBITDA guidance tied to inflation and production challenges.
- The integration of Dowlais is now flowing through Dauch's income statement, with higher revenue, US$100 million of run rate synergies and fresh contract wins offset by cost pressure that is delaying the full benefit to profitability.
- We now examine how Dauch's lowered EBITDA outlook, together with Dowlais driven scale, could influence the existing investment narrative.
Compare how Dauch’s mix of higher sales and pressured profitability stacks up against other potential turnaround stories by scanning 19 high quality undiscovered gems with similarly strong fundamentals but less crowded attention.
Dauch Investment Narrative Recap
Dauch now asks you to believe that a much larger platform can eventually earn an acceptable return even while current results are loss making. Revenue of about US$2.91b in Q3 and US$8.24b for the first nine months reflects Dowlais scale, but the net loss of US$45.3 million in the quarter underlines how inflation and production volatility are still biting.
The near term swing factor is execution on the US$300 million synergy and productivity plan and whether cost control shows up in EBITDA rather than just in slide decks. The biggest operational risk is that inflation, supply chain noise and customer production changes keep absorbing those savings. That would leave Dauch carrying higher complexity without a clear payoff.
The Q3 2026 earnings release on 6 November is the most relevant marker right now. It confirms that sales nearly doubled year on year and that Dauch is already realizing US$100 million of run rate synergies. At the same time, full year EBITDA guidance is being lowered because inflation, supplier issues and production changes are squeezing profitability.
For you as an investor, that update sharpens the catalyst map. Progress on the wider US$300 million program, stability in customer schedules, and evidence that integration benefits can outpace rising labor, energy and logistics costs are the practical checkpoints. If those items stall, Dauch’s higher scale could remain tied to thin or negative earnings longer than the market is willing to tolerate.
Dauch's current analyst narrative points to revenue of US$12.2b and earnings of US$272.6 million by 2029. That path assumes revenue growth of 14.1% per year and an earnings swing of about US$436 million from current earnings of a US$163.5 million loss.
Uncover why Dauch's fair value indicates an 89% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate angle on Dauch focuses on the bullish catalyst of deleveraging. The most optimistic analysts were pencilling in revenue of about US$12.3b and earnings of US$289.2 million by 2029, tied to lower net leverage and synergy gains. After this earnings release, those assumptions may shift. Compare both stories carefully.
Explore another Dauch fair value estimate, including one that suggests as much as 223% potential upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Dauch research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Dauch. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Dauch's overall financial health at a glance.
Looking For More Ideas Beyond Dauch?
If Dauch has sharpened your thinking about turnarounds, capital allocation and balance sheet resilience, it can help to set it alongside other opportunities that share some of the same traits. The Simply Wall St Screener lets you filter the market quickly so you can focus on a shorter, higher conviction list that matches your own risk and income preferences.
- If downside protection matters most, start with companies that score well on resilience and financial risk by reviewing a curated 31 resilient stocks with low risk scores in a single view.
- If income is a priority, scan for businesses offering stronger cash returns to shareholders by checking a hand picked 7 dividend fortresses that meet a minimum 5% yield hurdle.
- If you prefer businesses with room to be re rated, compare Dauch with a focused 19 high quality undiscovered gems that pair solid fundamentals with relatively low market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com