


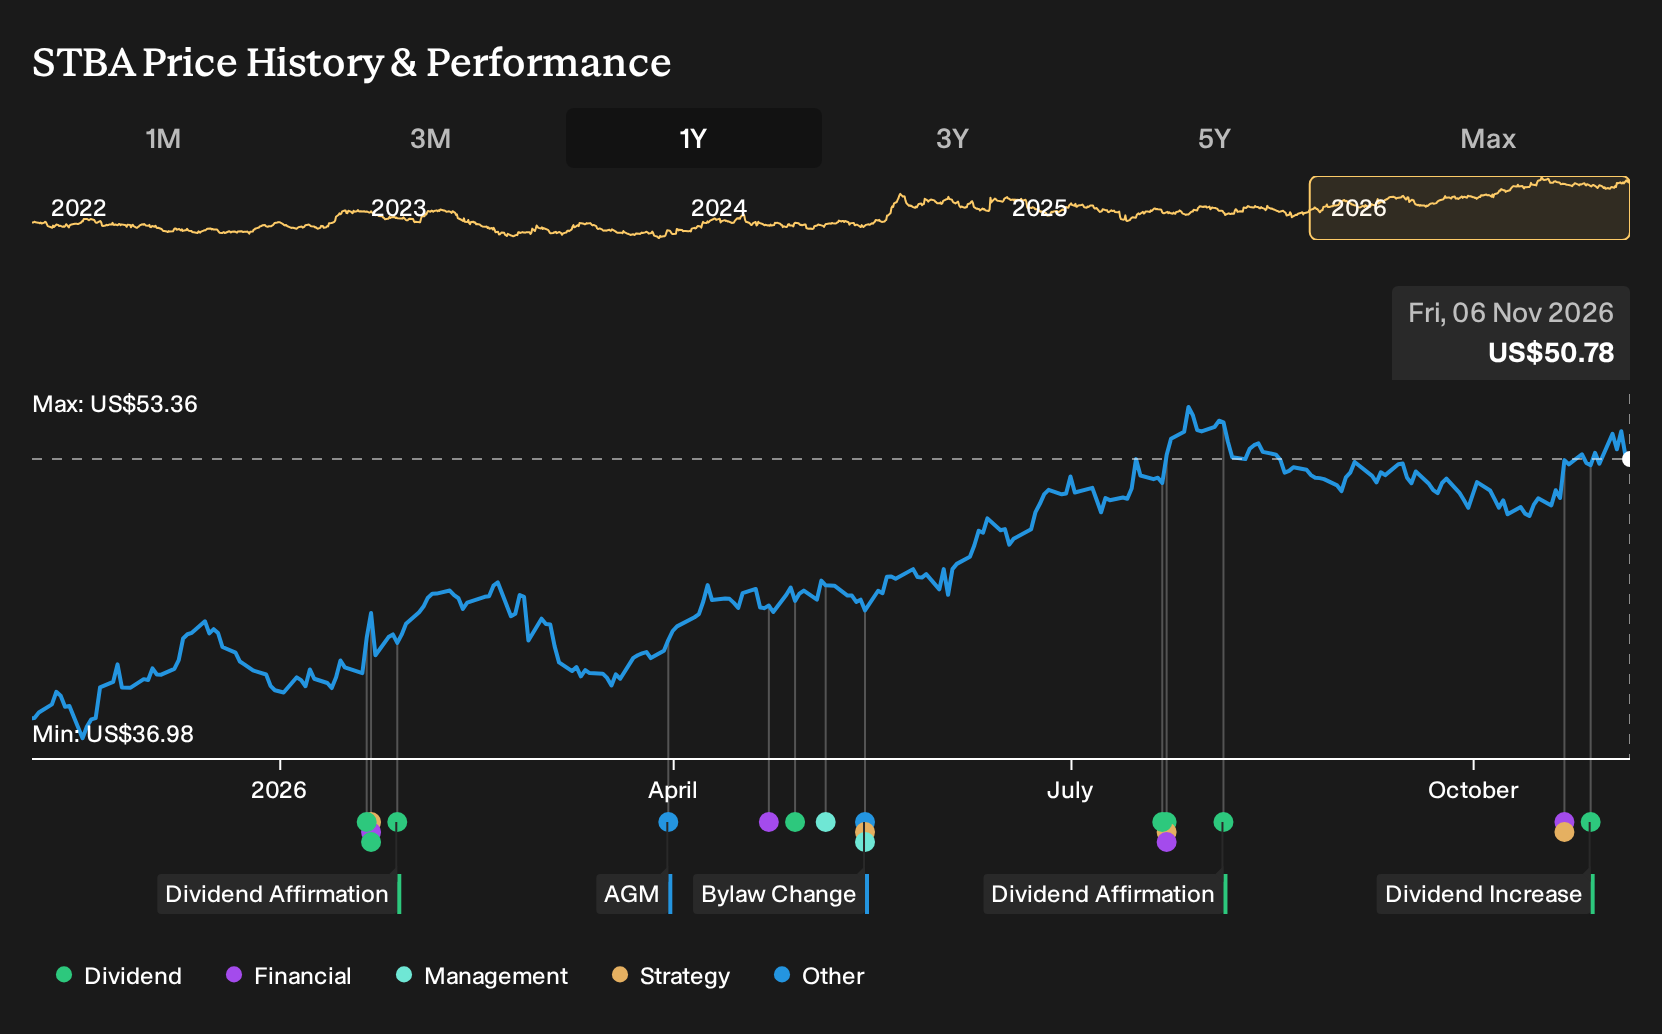
- S&T Bancorp's board approved a higher quarterly cash dividend of US$0.38 per share on 28 October 2026, up from US$0.37 in the prior quarter. This implies a 3.00% annualized yield based on the 27 October 2026 close, and is payable on 27 November 2026 to holders of record on 12 November 2026.
- The dividend increase, alongside an active capital return program that includes a multi-year share repurchase authorization, highlights S&T Bancorp's focus on returning cash to shareholders while managing funding costs, deposit mix and expense discipline.
- We will now look at how S&T Bancorp's investment narrative is affected by this higher quarterly dividend and emphasis on capital returns.
S&T Bancorp Investment Narrative Recap
S&T Bancorp investors essentially need to believe the bank can keep turning its relationship deposit base, commercial team expansion and tight cost control into consistent, if moderate, earnings progress. The higher US$0.38 dividend fits with that story but does not radically change it. The near term swing factor still looks tied to reigniting loan growth without hurting credit quality.
The bigger risk remains that muted net interest income trends and softer loan pipelines, including earlier commercial real estate headwinds, drag on earnings while Durbin related fee pressure builds toward 2028. If those themes reappear, the richer capital return profile, including this dividend lift, may not fully offset the earnings strain.
The dividend increase on 28 October 2026 is the most relevant recent announcement here, since it directly sets the 3.00% indicated yield that income focused holders are looking at today. A small step up from US$0.37 to US$0.38 per share builds on S&T Bancorp’s record of prior quarterly raises and keeps the payout ratio near the cited 40% range.
That cash return sits alongside the ongoing US$100m repurchase authorization that runs into 2027 and the roughly 8% share count reduction already completed. Together, the higher dividend and buyback program concentrate per share metrics, which can matter if loan growth re accelerates, but they also raise the stakes if net interest income and noninterest revenue face more pressure.
S&T Bancorp's current analyst narrative points to revenues of US$465.0 million and earnings of US$142.7 million by 2029, based on an assumed 4.7% yearly revenue growth rate and an earnings increase of about US$2.1 million from US$140.6 million today.
Uncover why S&T Bancorp's fair value indicates a 5% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly US$53 to US$77, so some private investors see S&T Bancorp as closer to fully priced while others model far more optimistic outcomes. Consider this in light of risks around muted net interest income trends and Durbin fee pressure, then explore these contrasting viewpoints before deciding how this dividend story fits your portfolio.
Explore another S&T Bancorp fair value estimate, including one that suggests a potential 51% upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that is truly your own.
- A great starting point for your S&T Bancorp research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for S&T Bancorp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate S&T Bancorp's overall financial health at a glance.
Looking for more investment ideas beyond S&T Bancorp?
If this S&T Bancorp dividend story has sharpened your focus on income and quality, use that same lens across the wider market with the Simply Wall St Screener and build a watchlist that truly fits your goals.
- For investors who want quality at a sensible price, scan a 38 high quality undervalued stocks that already combine solid fundamentals with a discount to their calculated worth.
- If capital preservation sits high on your list, filter for steadier profiles using a 31 resilient stocks with low risk scores that ranks companies on business strength and balance sheet resilience.
- When you want to stay ahead of the crowd, cast a wider net with a 19 high quality undiscovered gems that highlight under-followed businesses with strong underlying numbers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com