


Onshoring is no longer just a policy buzzword. It is reshaping how goods move across North America as FTZ rules, USMCA reviews, and tariff debates quietly influence where factories sit, where cargo flows, and which exporters keep more of each dollar of profit. Investors watching this shift risk missing it until it is already priced in. This article breaks down three U.S. industrial exporters exposed to these developments and explains why their fortunes could increasingly hinge on how this trade story unfolds.
The three exporters highlighted below are just a first pass. The full screen surfaced 33 more industrial and manufacturing companies with equally compelling trade and onshoring angles that are not covered here. To go straight to the source, analyze and identify your own highest conviction ideas with the U.S. industrial exporters benefiting from FTZ and USMCA-driven onshoring screener.
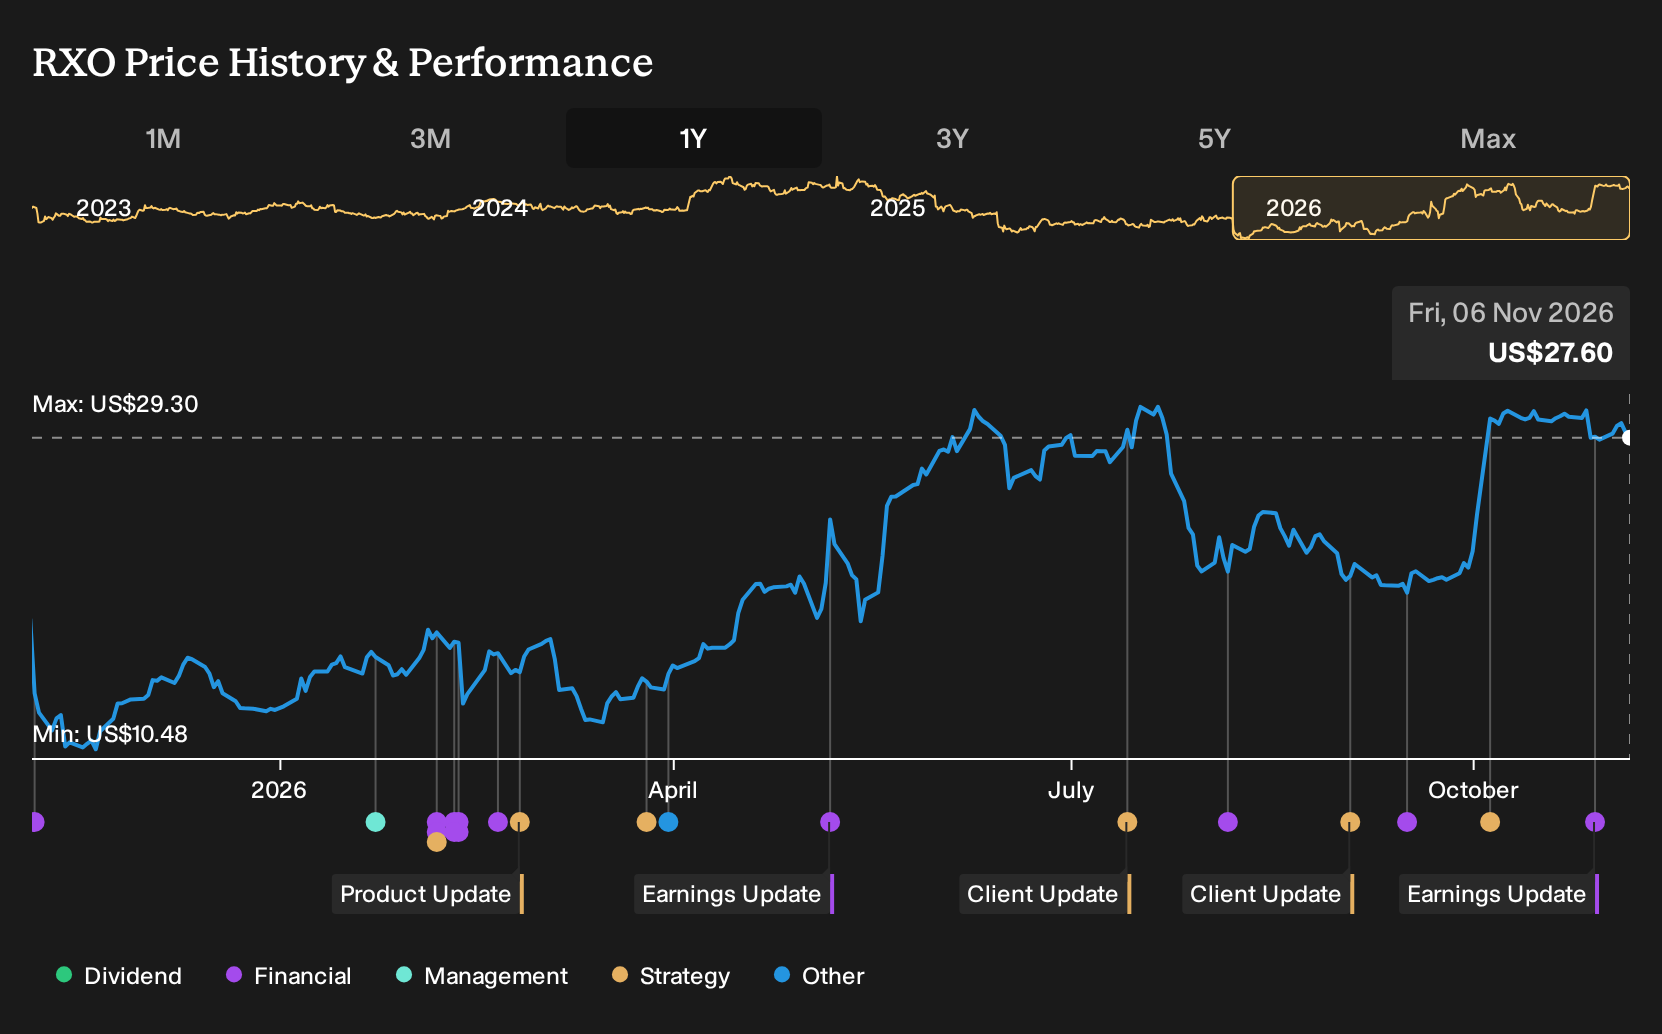
RXO (RXO)
Overview: RXO is an asset-light truck brokerage that connects shippers with carriers across the U.S., Canada, Mexico and key global trade lanes, positioning the business squarely in the cross-border onshoring story.
Operations: RXO generates about US$6.5b from Transportation - Trucking, with roughly US$6.0b coming from the U.S. and around US$500 million from international markets.
Market Cap: US$4.6b
RXO matters for this onshoring screen because it sits on the freight pipes that link U.S. factories, Mexican production hubs and FTZ-driven distribution into a single flow of truckloads.
Secular growth in e-commerce and in on-demand, tech-enabled supply chain solutions is expanding RXO's total addressable market. The company’s asset-light, tech-focused model may influence how it competes for new, higher-margin business.
What happens to RXO's earnings power if one key cross-border volume assumption shifts as FTZ and USMCA rules are reset?
If that cross-border math matters to you, read the full narrative for RXO to see how RXO's asset-light model could respond if trade flows accelerate or stall.
Avient (AVNT)
Overview: Avient formulates specialized polymer, color, additive and ink solutions used in packaging, medical, transportation and industrial products across North America, including U.S., Canada and Mexico.
Operations: Avient generates about US$2.1b from Color, Additives and Inks and roughly US$1.3b from Specialty Engineered Materials, with a small corporate loss.
Market Cap: US$4.2b
Avient matters in this onshoring screen because its materials are embedded in the packaging, medical and industrial products that U.S., Canadian and Mexican manufacturers ship across USMCA borders.
Growing use of Avient materials in semiconductor fabs, AI servers and data center cabling, in addition to the electronics and computing vector that is expected to generate more than US$40m of sales in 2026 within a roughly US$2b opportunity, creates headroom for additional product lines and specifications that can shift mix toward higher gross margin and support earnings.
What happens to Avient’s margin potential if one key piece of that high value mix story does not unfold as customers expect?
If that question is front of mind, read the full narrative for Avient to learn how Avient’s mix, pricing power and capital choices could be accelerating or quietly stalling.

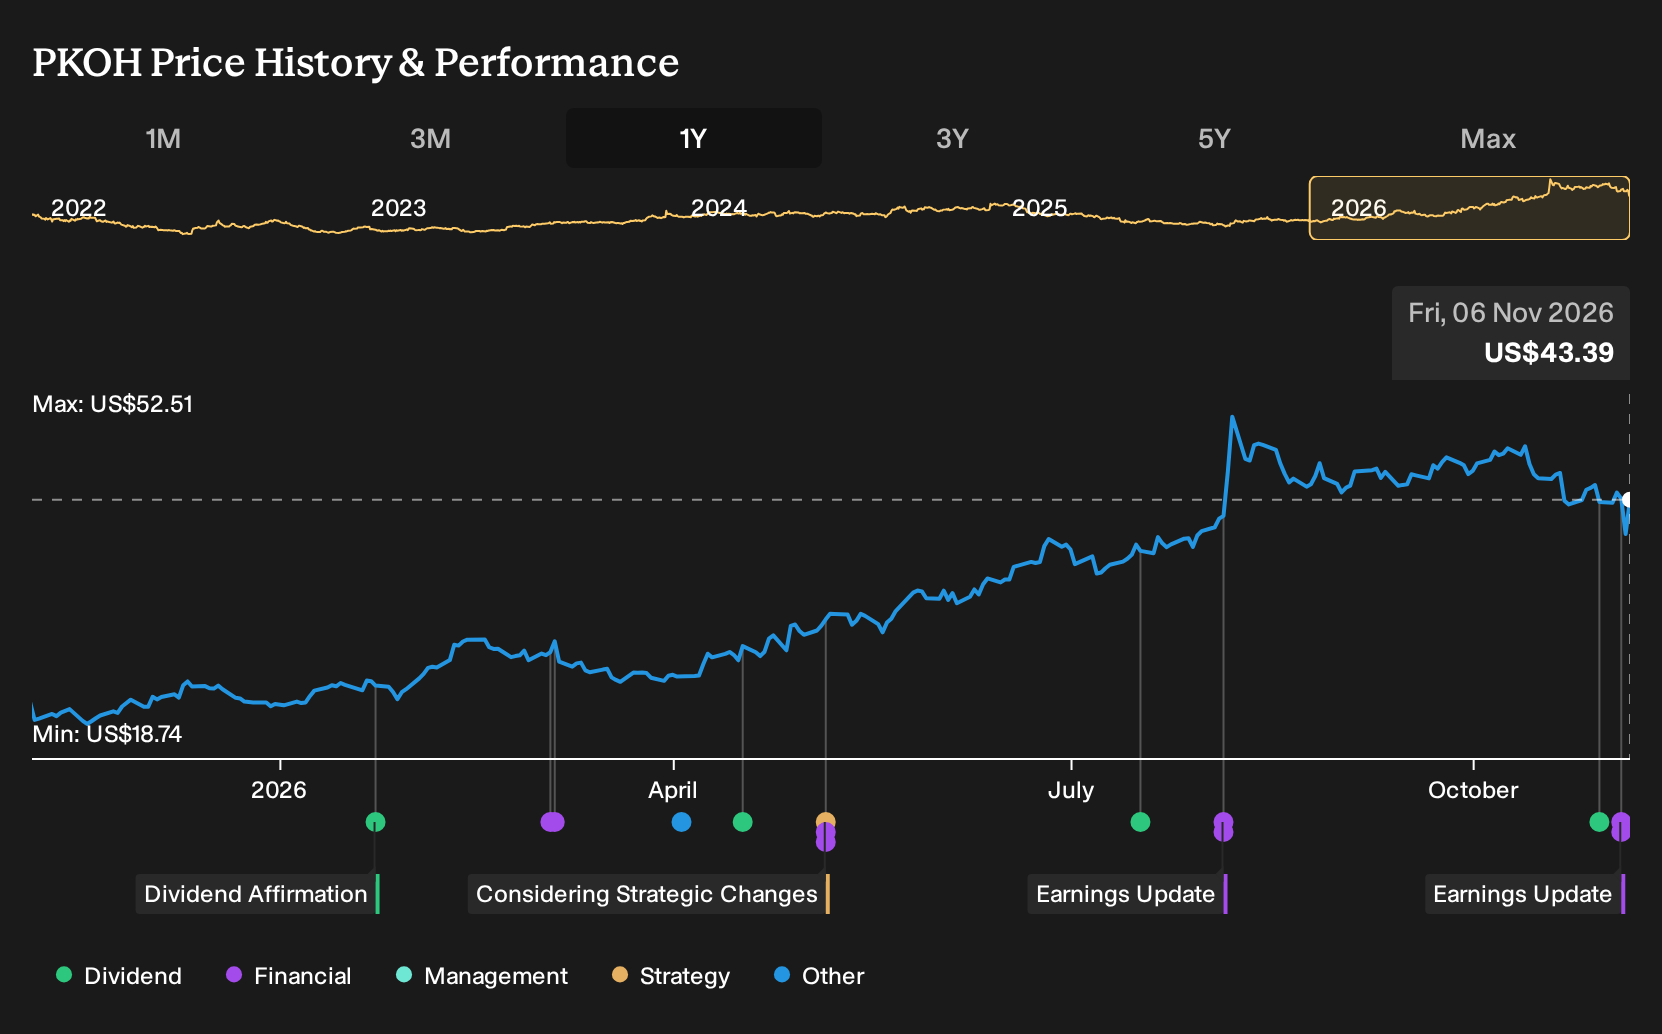
Park-Ohio Holdings (PKOH)
Overview: Park-Ohio Holdings runs a Cleveland based industrial group that supplies cross border manufacturers with engineered components, equipment and supply chain services across the U.S., Mexico and Canada.
Market Cap: US$605 million
Park-Ohio matters for this onshoring screen because its plants and service hubs sit along the same North American production routes that FTZ tweaks and USMCA tariff shifts are already nudging, especially for complex equipment and component programs that are hard to relocate quickly.
Growing exposure to electrical infrastructure, data center related electrical distribution, battery related applications and broader industrial electrification, supported by a global operational footprint that helps customers localize supply chains, points to sustained demand that can support higher segment revenue and potentially steadier EBITDA margins.
The real tension for Park-Ohio is how margins and cash generation respond if one unseen pressure on funding costs moves in the wrong direction.
If that risk worries you, read the full narrative for Park-Ohio Holdings to see whether Park-Ohio’s electrification exposure is quietly masking stronger cash generation potential.
Seeking Alternatives Before Momentum Flies
Fresh ideas rarely stay quiet for long. Breakout themes gain momentum, weaker stories get caught dropping, and under the radar for now rarely lasts. Consider reviewing potential ideas while conditions remain in flux.
- Evaluate resilient compounders by scanning a curated 31 resilient stocks with low risk scores that focuses on sturdier balance sheets and historically calmer drawdowns while conditions still feel uncertain.
- Find early AI momentum before headlines catch up and track current earnings characteristics with the hand picked 40 profitable AI stocks that aren't just burning cash set built around actual cash generation.
- Explore opportunities tied to potential grid upgrades with the focused 41 power grid technology and infrastructure stocks group, where core demand for transmission and infrastructure may be a key consideration alongside news flow.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com