


- Elbit Systems reported two sizeable wins: a roughly $170 million, 15 year Israel Ministry of Defense artillery training center contract and about $200 million in Asia Pacific airborne ISTAR and training deals.
- The mix of long duration Israel artillery training work and Asia Pacific airborne payload and HUD supply illustrates how Elbit Systems ties recurring services to high spec equipment programs.
- We will look at how Elbit Systems' investment narrative is influenced by this 15 year Israel artillery training center contract.
Elbit Systems Investment Narrative Recap
To own Elbit Systems, you need to be comfortable with a defense contractor built around a large, multi year backlog and complex, long running projects. The key near term swing factor is execution on these big programs while keeping margins resilient as mix shifts between Israel, Europe and the U.S. The new artillery training center adds contracted visibility but does not radically change that story.
The biggest immediate risk is that war driven demand or defense budgets normalize faster than expected in core regions, which could slow fresh orders into that ₪25.2b backlog. Any slip in delivery, cost control or AI heavy program roll out would then bite harder, because fewer new wins would be there to offset issues.
The Israel Ministry of Defense artillery training contract is the most relevant trigger here. It runs for 15 years and includes simulators, AI based training tools and recurring support services. This ties directly into Elbit Systems focus on higher content per platform and multi year service layers on top of hardware.
This single award does not remove the risk from a potential cool down in defense spending. It does, though, sit alongside airborne ISTAR and training work in Asia Pacific and gives more evidence that training, simulation and AI assisted systems are becoming a bigger operational pillar. That matters for margins, backlog quality and how durable catalysts look if new order momentum slows.
Elbit Systems' narrative projects US$11.8b revenue and US$1.1b earnings by 2029. This assumes 11.5% yearly revenue growth and an earnings increase of about US$464m from US$636.0m today.
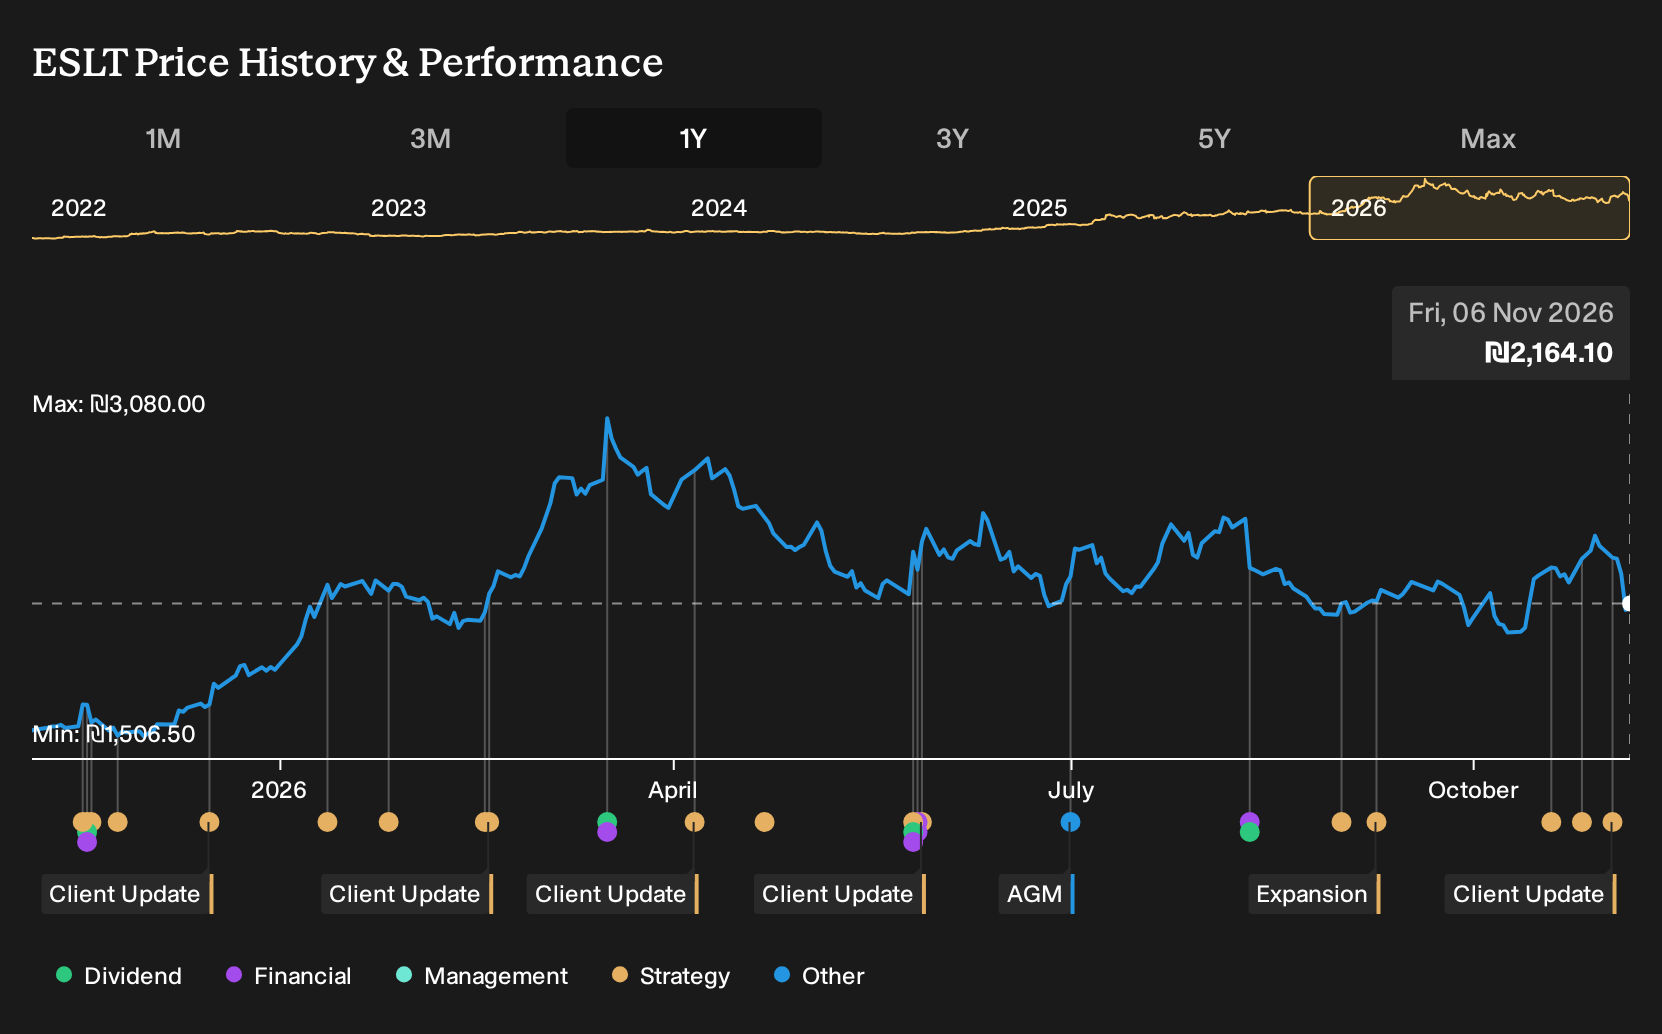
Uncover why Elbit Systems' fair value indicates a 37% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
The four fair value estimates from the Simply Wall St Community stretch from about US$1,031 to almost US$2,968 per share, so opinions on Elbit Systems are far apart. Those private forecasts do not yet reflect the new Israel and Asia Pacific training wins. These developments could reshape how you think about contract longevity, risk concentration and future cash generation.
Explore 3 other Elbit Systems fair value estimates, including one that suggests as much as 52% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Elbit Systems research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Elbit Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Elbit Systems' overall financial health at a glance.
Looking For More Investment Ideas Beyond Elbit Systems?
Once you have a handle on Elbit Systems, it can help to widen the lens and compare it with other opportunities that share similar qualities or offer something very different. The Simply Wall St Screener gives you a quick way to line up those candidates side by side and stress test your thesis against real numbers rather than headlines.
- Focus on quality at a discount by scanning a curated set of companies that combine strong fundamentals with attractive pricing using our 223 high quality undervalued stocks.
- If capital preservation matters most to you, compare a pool of stocks that score well on resilience and risk metrics through the 209 resilient stocks with low risk scores.
- For investors hunting for under-the-radar opportunities, surface lesser known businesses with solid financial profiles through the 581 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com