


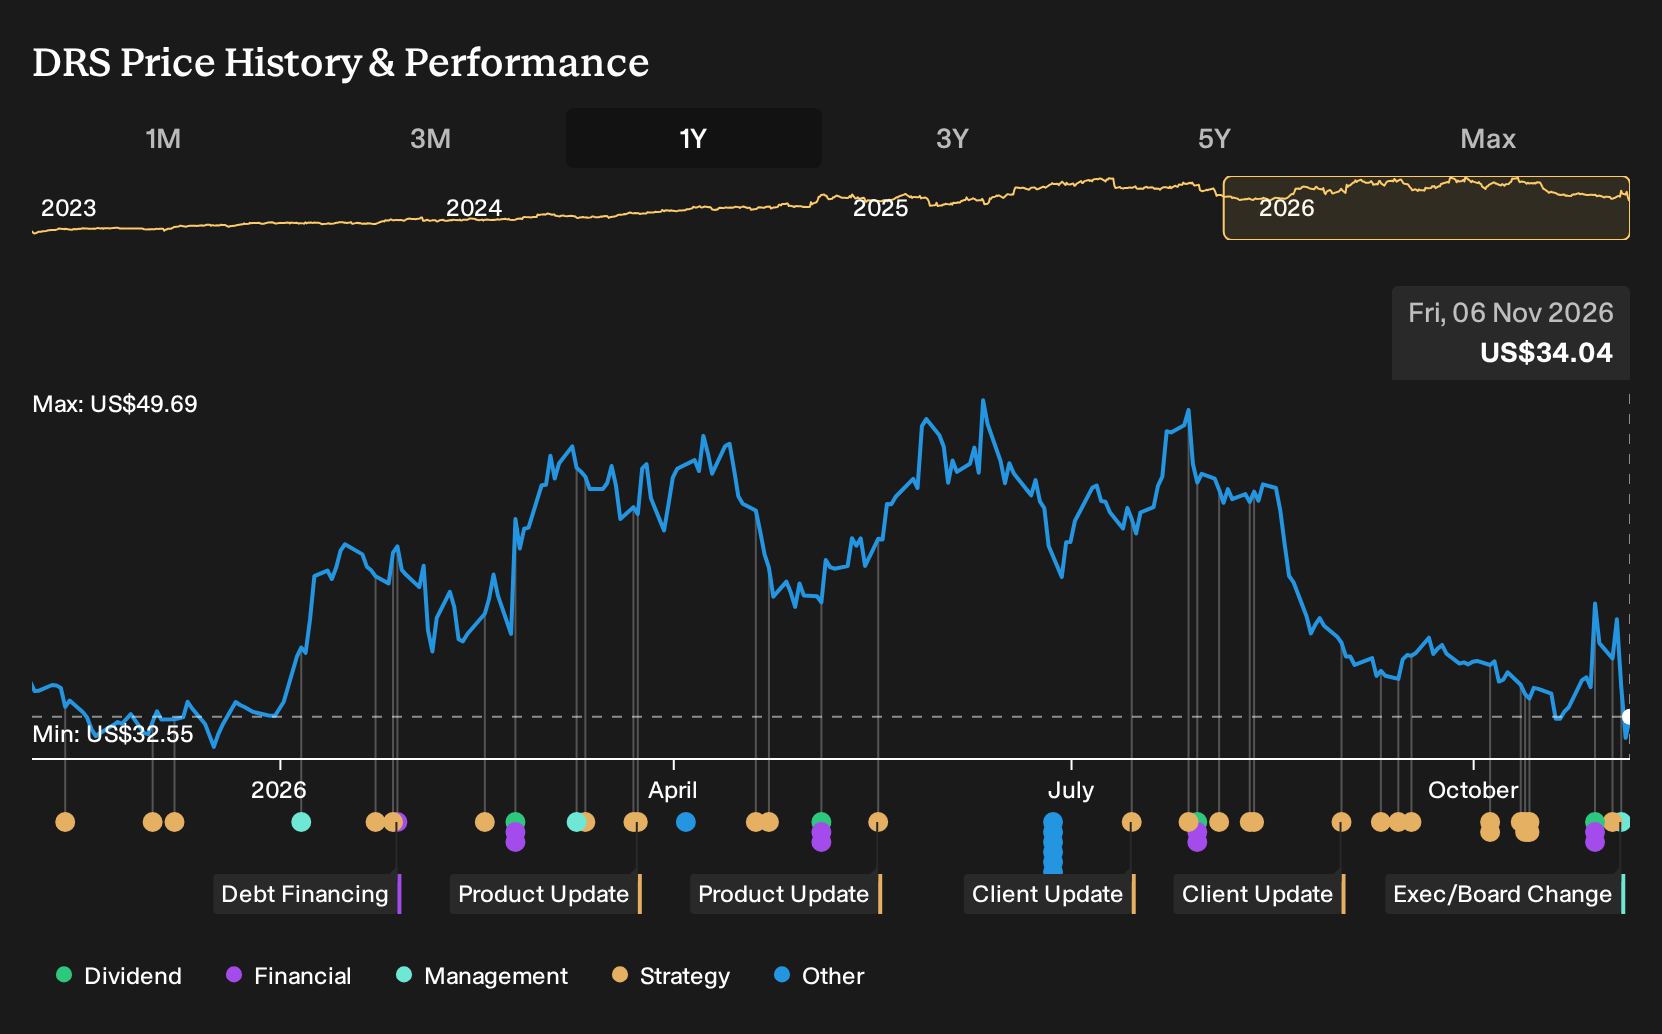
- Leonardo DRS reported third quarter 2026 sales of US$1,066 million and net income of US$115 million, then lifted full year 2026 revenue guidance to a range of US$3,950 million to US$3,985 million and affirmed a US$0.09 per share dividend.
- Fresh program wins and product recognition, including directed energy work on the U.S. Army’s Enduring High Energy Laser program and an award for the THOR tactical-edge computing chassis, point to expanding roles in power management, sensing and computing. These developments may shape how Leonardo DRS converts backlog into long term contracts.
- We will now explore how Leonardo DRS' higher full year revenue guidance could reshape its investment narrative and risk reward profile.
Look beyond Leonardo DRS and identify other defense and dual use companies that may be benefiting from similar contract momentum with our hand picked 53 AI infrastructure stocks list.
Leonardo DRS Investment Narrative Recap
To own Leonardo DRS, you need to believe the defense electronics platform can keep turning contract momentum in areas like sensing, computing and naval power into steady backlog conversion and disciplined earnings. The raised 2026 revenue guidance and affirmed dividend point to an operating plan focused on execution. The key short term catalyst remains contract awards moving cleanly into production and delivery.
The biggest near term risk is that higher R&D and capital spending, plus mixed sentiment on growth and backlog trends, do not translate into sustained orders across radar, infrared and propulsion programs. The latest earnings and contract news help the story, although they do not remove concerns that longer term backlog or returns could soften again.
The AeroVironment selection for the Enduring High Energy Laser production program looks most directly tied to the current narrative around Leonardo DRS. It reinforces the role in power management, thermal control and rugged integration for counter UAS missions, which are already a key focus in the broader contract set investors are watching.
For you, this contract sits right on the catalyst risk line. Successful execution could support future directed energy and counter drone opportunities, while delays, cost issues or weaker follow on work would feed into worries about whether increased internal investment in advanced sensing and computing is earning its keep on the income statement and cash flow.
Leonardo DRS' analyst narrative projects US$4.7b revenue and US$458.3 million earnings by 2029. This assumes 7.9% yearly revenue growth and an earnings increase of about US$136 million from US$322.0 million today.
Uncover why Leonardo DRS' fair value indicates a 54% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view puts leadership execution, including the new chief human resources officer, at the center of the Leonardo DRS debate. The most cautious analysts were working off roughly US$4.7b of 2029 revenue and about US$476.7 million of earnings. You can read that as a tighter, more skeptical story that may shift after this week’s news.
Explore 4 other Leonardo DRS fair value estimates, including one that suggests it could be worth just $43.55!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd. Trust your own analysis and judgment.
- A great starting point for your Leonardo DRS research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Leonardo DRS. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Leonardo DRS' overall financial health at a glance.
Looking for more investment ideas beyond Leonardo DRS?
If the Leonardo DRS story has sharpened your thinking around contract quality, balance sheet strength and payout potential, use that same lens across the wider market with the Simply Wall St Screener.
- For investors who care most about resilient finances, start with a list of solid balance sheet and fundamentals (25 results) that can handle tougher conditions without stretching the balance sheet.
- If stability and income matter more to you than rapid growth, focus on steady cash payers in our curated 7 dividend fortresses that could help anchor a portfolio.
- When you want quality at a sensible entry point, filter for mispriced opportunities using the 38 high quality undervalued stocks and see which companies match your return and risk preferences.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com