


Ormat Technologies (ORA) just packed several updates into its early November news, including third quarter results, a raised 2026 revenue outlook, a fresh dividend declaration, and a small asset impairment.
Recent price action reflects that mix of good news and lingering caution. Ormat Technologies shares trade at US$91.90, with a 30 day share price gain of 3.35% and a 7 day rise of 2.46%. However, the 90 day share price return has declined 17.73% and the year to date move is down 19.19%. Longer history still shows a 3 year total shareholder return of 53.79% and a 5 year total shareholder return of 15.46%, hinting that momentum has faded in the short run even as the longer record remains positive.
Spot under-pressure renewables like Ormat Technologies and compare them with hand picked peers using the 41 power grid technology and infrastructure stocks.Ormat Technologies has bounced a little, yet the share price still sits well below both analyst targets and one intrinsic estimate. Is this discount pointing to mispricing, or is it a fair reflection of the risk profile?
Most Popular Narrative: 37% Undervalued
On the prevailing narrative, Ormat Technologies screens as materially below its implied fair value of $145, compared with the recent $91.90 close. This puts the focus squarely on whether the long term project pipeline really supports that gap.
The Ormega100 standardized 100 plus MW unit, designed to compress above ground EGS plant costs to about US$1.5m per MW and shorten build times to under 18 months, gives Ormat Technologies a template to roll out larger geothermal and EGS projects using its existing manufacturing base. This could help lift EBITDA margins as more standardized capacity feeds into earnings.
See why 0 investors see Ormat Technologies as 37% undervalued.
Result: Fair Value of $145 (UNDERVALUED)
Still, the bullish Ormat Technologies story weakens if EGS projects stumble on cost or timing, or if funding tightens and compresses the high implied P/E.
Find out about the key risks to this Ormat Technologies narrative.
Another View: Ormat Technologies Through The P/E Lens
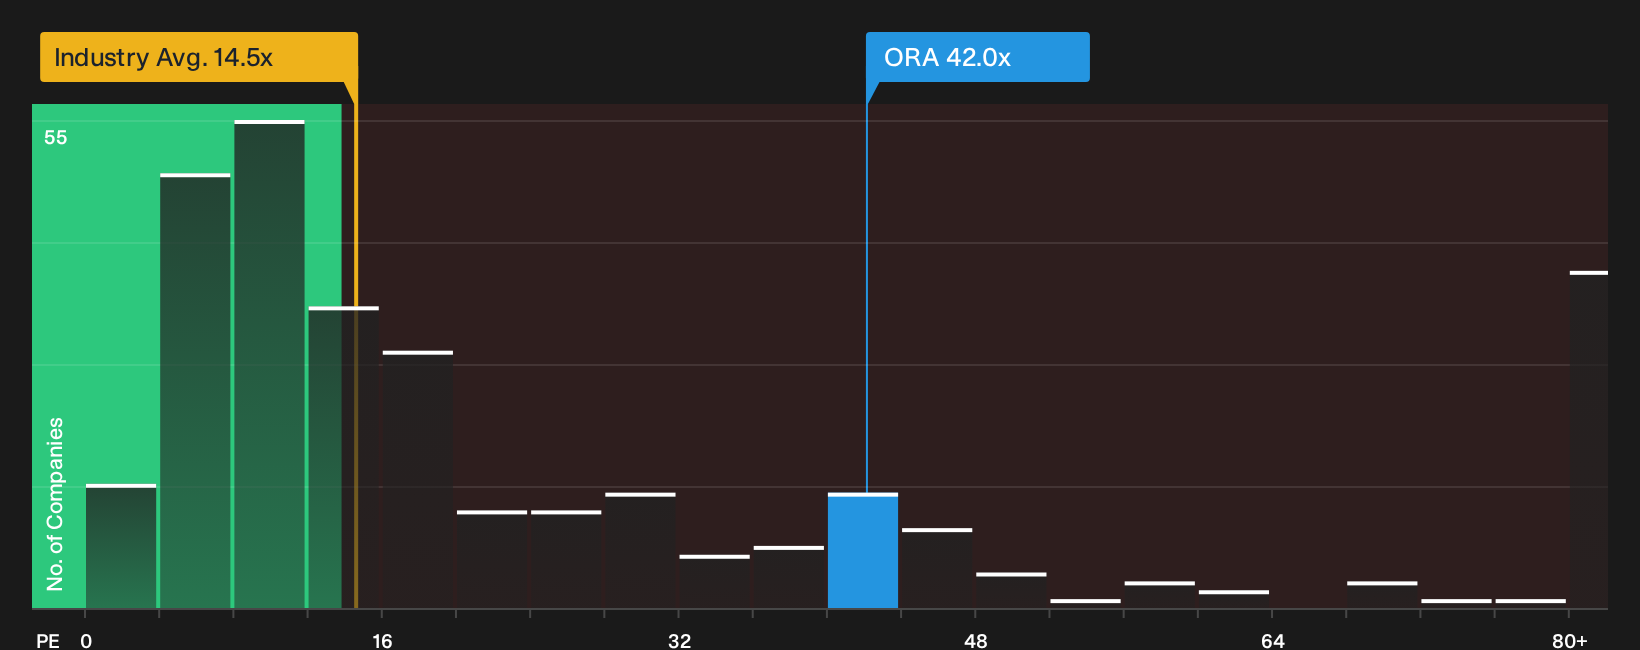
The story looks very different once the spotlight moves from that $145 fair value to today’s earnings multiple. Ormat Technologies trades on about 42x P/E, while the fair ratio sits at 23.9x, the peer average at 28.4x, and the broader global renewable energy group at 14.5x.
In plain terms, the stock carries a relatively high price tag compared with both its closest competitors and the fair ratio that the market could move toward over time. If sentiment cools or the bullish narrative softens, investors may want to consider how comfortable they are holding a valuation that relies significantly on future execution.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals in Ormat Technologies headlines can easily sway sentiment, so consider acting promptly, review the full picture and weigh its 3 key rewards and 2 important warning signs.
Looking for more Ormat Technologies style investment ideas?
Do not stop with Ormat Technologies. Fresh opportunities keep turning up, and missing the next one often comes down to not checking the right shortlists early.
- Target value driven opportunities by scanning the 38 high quality undervalued stocks that combine quality fundamentals with prices that may not fully reflect them yet.
- Prioritise resilience and sleep better at night by using the 31 resilient stocks with low risk scores that focuses on businesses with stronger risk profiles.
- Hunt for under the radar potential by reviewing the 19 high quality undiscovered gems before the broader market pays full attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com