


Astrana Health has had a bumpy few years in the market, yet the stock now trades near US$34.50 after a mix of setbacks and rebounds. With that backdrop and fresh earnings headlines, the live question is whether today's share price is adequately supported by the profits the business is generating.
- Over the past 5 years the share price declined 68.6%, which puts a lot of weight on whether Astrana Health's current earnings profile can justify any recovery investors are hoping for.
- Recent record results, alongside new payer and platform partnerships, may support expectations for stronger earnings and cash generation. This, in turn, influences how much investors are willing to pay for each dollar of Astrana Health's profit.
- The analysts covering Astrana Health have run their own numbers. See what analysts think Astrana Health's shares could be worth.
The issue now is whether Astrana Health's current earnings, when set against its Fair Ratio benchmark, are enough to make the present valuation look sensible.
If you want to test the same earnings based valuation question across a wider field of ideas, scan through the 38 high quality undervalued stocks.
Is Astrana Health Fairly Priced on Earnings?
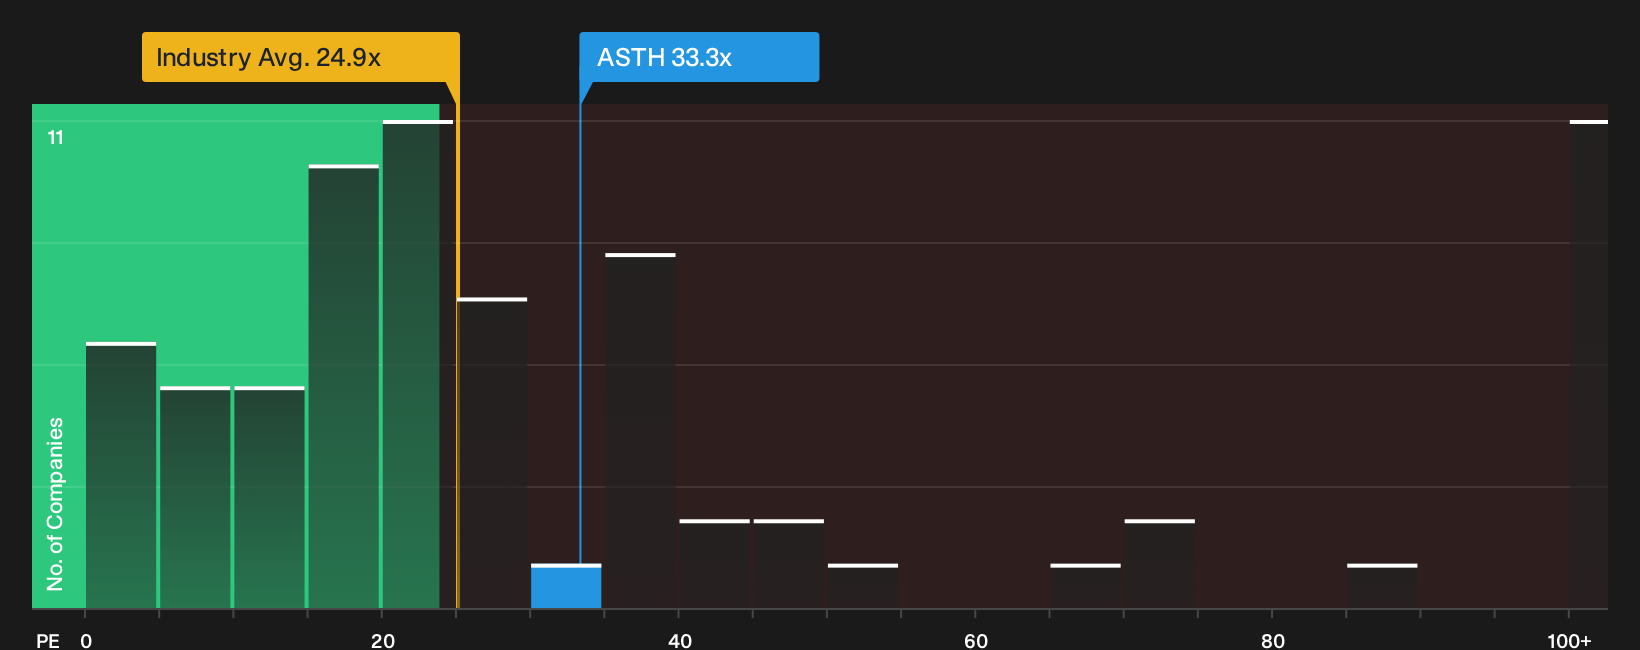
Astrana Health is profit making, so a P/E ratio gives a clean read on what investors are paying for each dollar of earnings. At roughly 33.3x, the stock trades above the wider healthcare sector average of about 24.9x, yet sits below both the peer group on roughly 39.7x and the tailored Fair Ratio benchmark that reflects Astrana Health's own growth profile and risk mix.
Because the recent record Q3 2026 results and expanded payer relationships are already public, this richer than sector multiple suggests that a fair amount of optimism around Astrana Health is now reflected in the price, but not so much that it screens as extreme against closer peers. That keeps the P/E signal finely balanced and places more emphasis on how you assess the durability of its current earnings power and cash generation outlook. Explore the numbers behind Astrana Health's P/E valuation.
The Astrana Health Narrative: What Would Justify Today's Price?
Narratives on Astrana Health pick up where the P/E puzzle leaves off. They spell out which paths for growth, margins and earnings would need to occur for the share price to look meaningfully higher or lower than it does today. Each one links its number to a clear view on how Astrana Health's prospects and risks might evolve, so you can revisit that logic as fresh information becomes available. These narratives are available on Simply Wall St's Community page.
One of the top community narratives on Astrana Health: 33% undervalued
"The main thing that has to go right is that Astrana Health continues to convert and manage more members in full-risk arrangements..."
Discover why this Narrative puts Astrana Health at 33% undervalued.
One more Astrana Health check that belongs beside the price tag
Astrana Health's valuation story only goes so far without weighing the separate set of caution flags that our broader review has picked up, and those details can materially shape how you frame the risk side of the thesis. Take a closer look at 2 warning signs (1 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com