


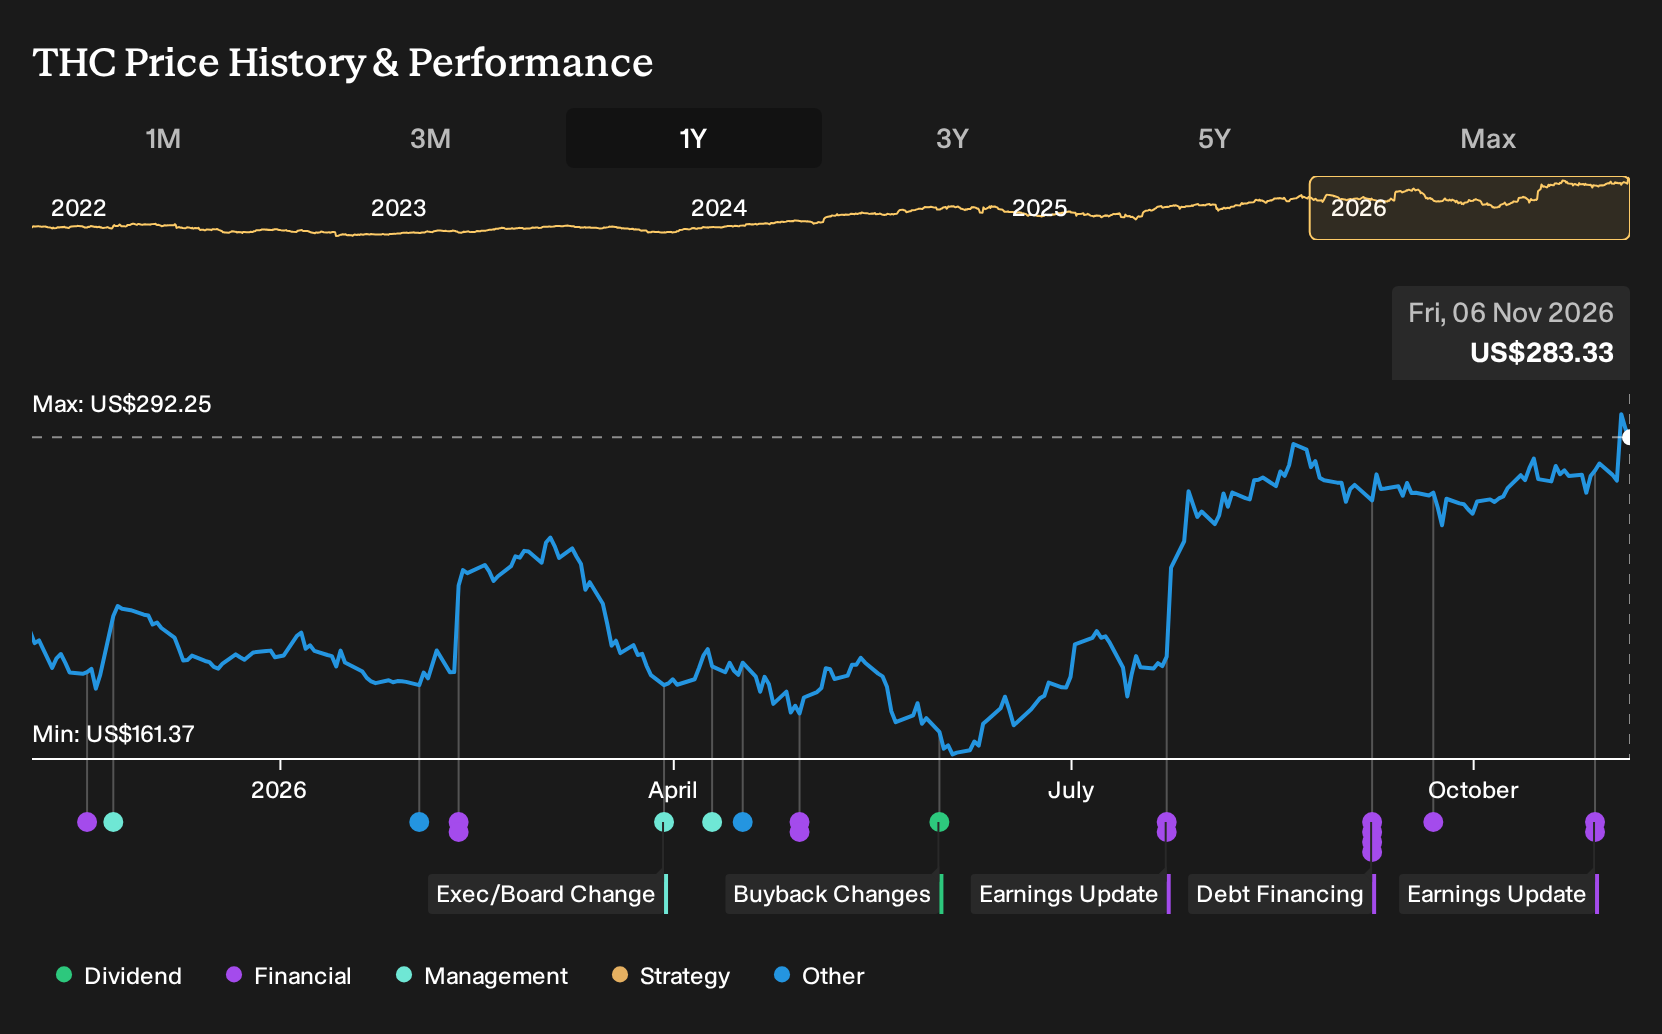
- Tenet Healthcare reported third quarter 2026 sales of US$5,631 million and net income of US$1,000 million, with higher basic and diluted earnings per share from continuing operations compared with the same period in 2025.
- The company raised its full year 2026 outlook, guiding to net operating revenues of US$22,050 million to US$22,450 million and diluted income per share of US$35.82 to US$37.08. This outlook leans heavily on high acuity outpatient and behavioral health performance.
- We will look at how Tenet Healthcare's investment narrative is reshaped by raised 2026 earnings guidance anchored in high acuity outpatient trends.
Tenet Healthcare Investment Narrative Recap
To own Tenet Healthcare, you need to believe the shift toward high acuity outpatient procedures and behavioral health can stay productive even as payer mix and reimbursement remain tricky. The fresh guidance upgrade leans into that view and signals management confidence in current demand patterns, cost controls and case intensity.
The biggest near term swing factor is whether high acuity outpatient and behavioral volumes stay strong enough to offset pressure from rising uninsured volumes and dependence on supplemental Medicaid programs. The key risk is execution and policy exposure colliding with a highly leveraged balance sheet and heavy capital deployment commitments.
The raised 2026 earnings outlook is the clearest operational signal from Tenet Healthcare right now. Management now expects net operating revenues of US$22.05b to US$22.45b and diluted income per share of US$35.82 to US$37.08, framed around outpatient acuity and behavioral performance as core drivers of the current run rate.
For you as a shareholder, that same guidance sharpens both the potential catalyst and the risk. If high acuity outpatient procedures and behavioral care keep supporting margins, it can help management fund USPI M&A, technology efficiencies and buybacks without stretching the balance sheet. If payer mix or Medicaid programs weaken, the guidance range becomes harder to defend.
Tenet Healthcare's current analyst narrative points to forecast revenues of US$24.3b and earnings of US$1.6b by 2029, based on an assumed 3.1% yearly rise in revenue and an earnings decline of US$1.3b from US$2.9b today.
Uncover why Tenet Healthcare's fair value indicates a 4% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One bullish twist on Tenet Healthcare focuses on technology savings as the main upside. The most optimistic analysts were already assuming roughly 4.2% annual revenue growth to about US$25.0b and earnings of US$1.5b by 2029. Those projections came before this guidance hike, so these narratives may now shift. Explore a few of them before deciding what you believe.
Explore 4 other Tenet Healthcare fair value estimates, including one that suggests upside of as much as 524% from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Tenet Healthcare research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Tenet Healthcare. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to review Tenet Healthcare's overall financial health at a glance.
Looking for more investment ideas beyond Tenet Healthcare?
If Tenet Healthcare has sharpened your thinking but you want a wider field to compare against, use this as a springboard to scan other businesses that fit your risk, income, or value preferences.
- For investors hunting for potentially mispriced opportunities with quality fundamentals, start by reviewing a curated set of 38 high quality undervalued stocks that may warrant a closer look.
- If reliable income is your priority, focus on companies with robust payouts by checking out a hand picked group of 7 dividend fortresses that might suit a yield focused approach.
- When capital preservation matters just as much as upside, concentrate on financially resilient businesses using a targeted collection of 31 resilient stocks with low risk scores tailored for lower risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com