


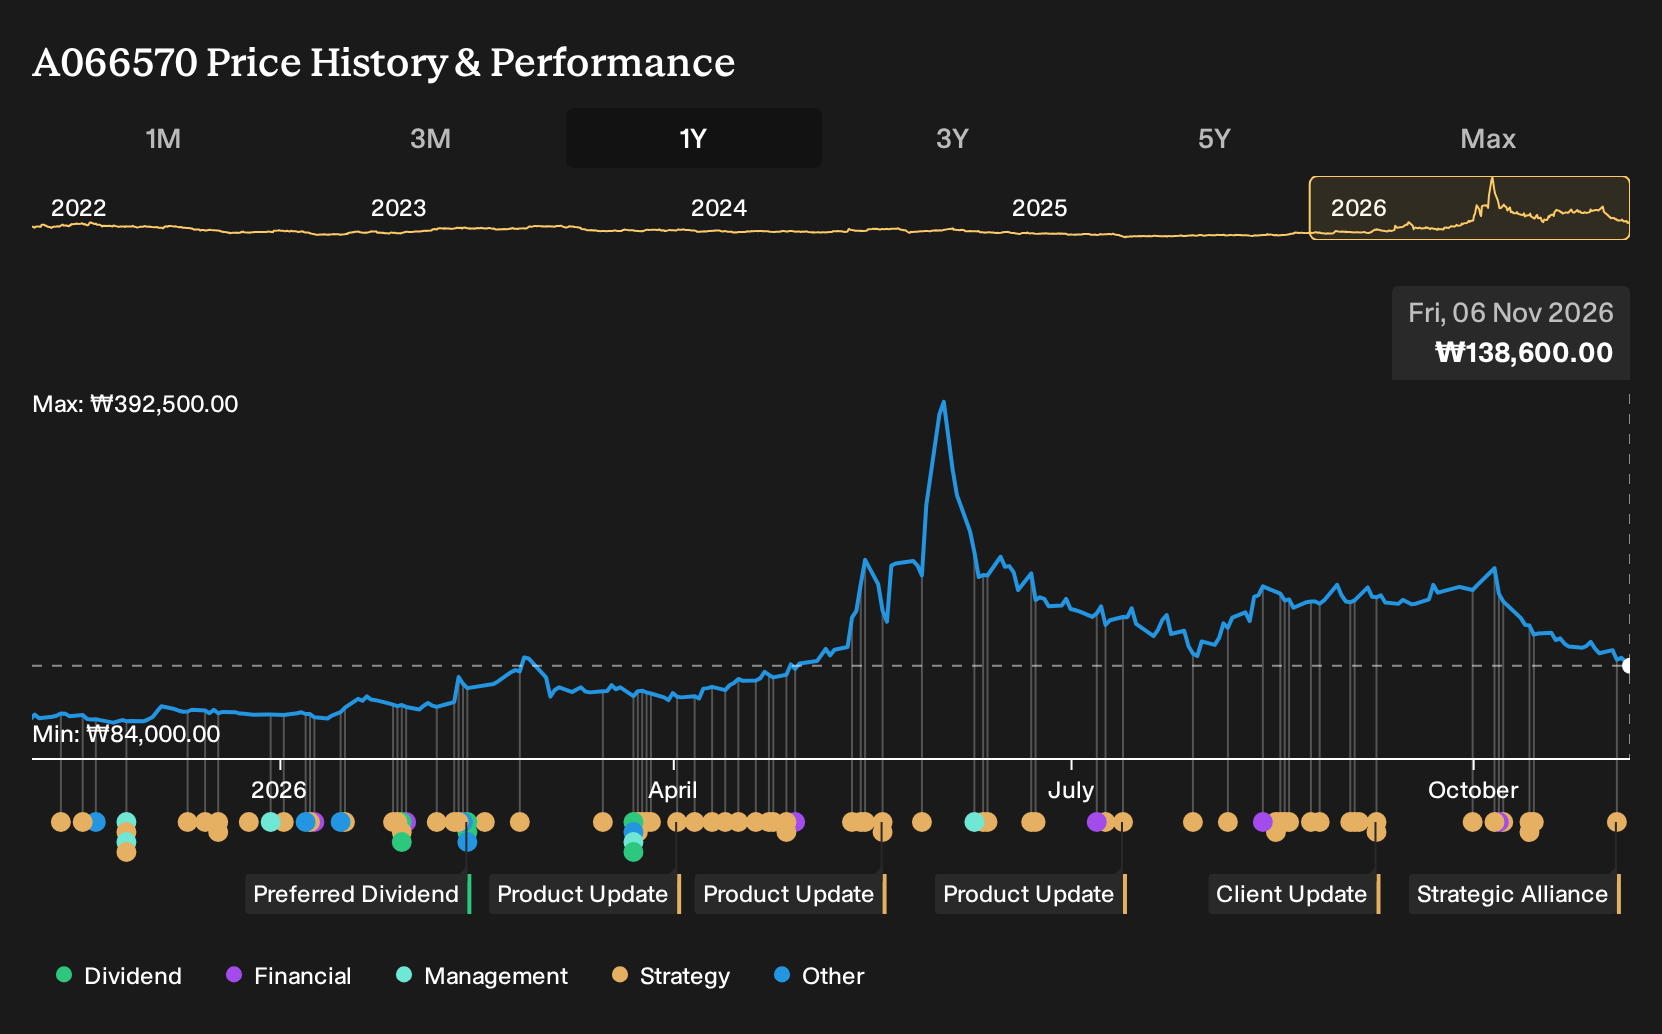
If you had bought LG Electronics on 6 November 2025, the past year now looks very different. Investors who held LG Electronics over the past year are up 58.6%, including dividends. That outcome sits against a backdrop where bullish analysts highlighted smart home IoT and HVAC expansion, while bears focused on tariffs and Chinese rivals. With new AI-powered appliances and fresh content partnerships emerging since then, the real question is what early buyers thought would matter most.
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
LG Electronics is not the only name tied to this theme. Zero in on 53 AI infrastructure stocks and compare how each one is priced.
What LG Electronics Investors Were Really Debating Back Then
The shares cost ₩92,050 at the start of the period, and anyone looking at LG Electronics then had to decide which story felt more believable.
The bullish narrative put fair value at ₩110,000. That view leaned on faster international scaling of B2B subscription services and webOS, plus stronger HVAC and smart home demand in emerging markets as key drivers for higher recurring income and margins.
The bearish narrative argued for a fair value of ₩77,500. That camp focused on rising US tariffs and tougher Chinese competition, which could push up costs, squeeze pricing power, and compress profitability over time.
What The Evidence Around LG Electronics Actually Tested
The launch of LG Electronics' AI powered 25 inch WashTower and the SoundHound partnership for commerce on LG Smart TVs both leaned toward the bullish story about smart home and subscription ecosystems. The Kuwait distribution deal also lined up with the emerging markets push. Reported numbers told a cooler story, with revenue at ₩23,826,468m and net margin slipping from 2.9% to 2.5%, so the evidence cut both ways.
The episode turned on whether higher tech content and wider reach would quickly lift profitability. For a different stock with a similar pitch, it may be useful to track new product launches or partnerships alongside net margin and the share of sales coming from recurring service or software style revenue.
What LG Electronics' Recent Run Now Prices In
LG Electronics trades at ₩138,600 today, with this selected Narrative arguing that its Fair Value sits above that level. The focus has shifted to how much of the AI, B2B and vehicle electronics story is already reflected in that one year gain.
The Narrative centers on LG Electronics leaning harder into subscription style income, platforms and higher value hardware. It argues today's price still does not fully credit successful AI data center cooling execution and monetization of robotics and webOS tied services.
"Bullish analysts expect LG Electronics to keep shifting its mix toward B2B, subscription and platform businesses, supported by automotive electronics, subscription services and webOS driven profitability. For this view to hold, LG Electronics needs to execute on AI data center cooling, robotics and Global South expansion while containing tariff, logistics and input cost pressures that are already affecting parts of the HVAC and electronics businesses."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
LG Electronics And Another Angle
You have watched LG Electronics lean harder into AI hardware and services. The next question is where similar subscription thinking appears elsewhere.
Active customers buying connected devices often care about premium gear and strong branding. That same mindset can carry into what they wear when they train.
One athletic business leans on premium pricing and its own stores. It wants customers to pay full price, not wait for discounts.
The aim is higher margin sales that feed off brand loyalty rather than markdowns. If that approach holds, your watchlist might gain a very different kind of AI era beneficiary.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 69% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com