


BancFirst earnings outlook shift sparks investor interest
An upgraded earnings outlook for BancFirst (BANF), highlighted by a Zacks Rank of #2 and a higher consensus earnings estimate this quarter, has drawn fresh attention from investors tracking the regional banking space.
BancFirst’s recent momentum has been building, with a 7-day share price return of 4.43% and a 30-day share price gain of 8.49% helping lift the stock to about $115, while in the longer term the total shareholder return over five years sits at 86.19%.
Scan other regional banks showing similar earnings momentum and price action using our curated list of solid balance sheet and fundamentals (25 results) as a comparison set to BancFirst right now.
BancFirst looks like a solid regional lender with rising earnings estimates and a strong recent run in the share price. The bigger question now is whether that quality is already fully reflected in today’s valuation.
Most Popular Narrative: 7% Undervalued
BancFirst is currently trading at $115.20, while the most followed narrative pegs fair value closer to $124.33, which aligns with analysts’ long term earnings and revenue assumptions for the bank.
Continued consolidation in the Tulsa market through the completed American Bank of Oklahoma integration and the planned Spirit BankCorp acquisition increases BancFirst’s branch footprint, loans and deposits in a key metropolitan area. This may support higher revenue and earnings if those assets are deployed efficiently.
See why 2 investors see BancFirst as 7% undervalued.
Result: Fair Value of $124.33 (UNDERVALUED)
Still, the narrative can break if BancFirst struggles to integrate its Tulsa acquisitions, or if slower revenue growth makes the current premium P/E look stretched.
Find out about the key risks to this BancFirst narrative.
Another view on BancFirst valuation
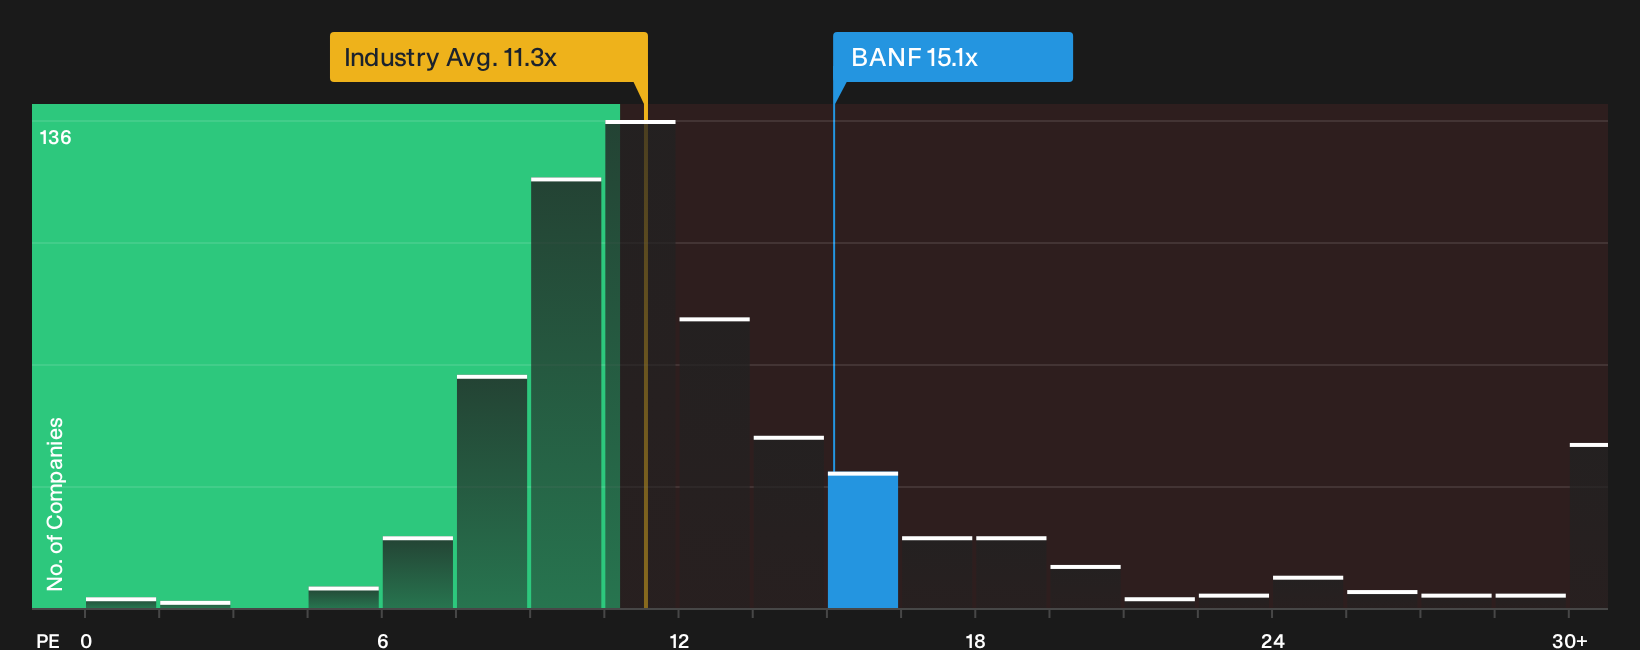
The narrative pegs BancFirst as undervalued, yet the P/E ratio of 15.1x tells a tougher story. It is above the US Banks industry on 11.3x and above peers on 11.8x, while the fair ratio sits at 11.6x. That gap points to valuation risk if sentiment cools.
For a closer look at what the current P/E gap might imply over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on BancFirst valuation can feel uncomfortable. Move quickly, review the data for yourself, and pressure test the story against the 4 key rewards and 1 important warning sign.
Looking for more BancFirst investment ideas?
If BancFirst has caught your attention, do not stop here. Use the Simply Wall Street Screener to spot other opportunities before they move without you.
- Target stronger value setups by zeroing in on companies flagged in the 38 high quality undervalued stocks that combine quality fundamentals with cheaper earnings multiples.
- Boost potential portfolio resilience by reviewing the 31 resilient stocks with low risk scores that highlights businesses with sturdier balance sheets and lower overall risk profiles.
- Hunt for earlier-stage opportunities by scanning the 9 elite penny stocks with strong financials that already show solid financial traits rather than just speculative momentum.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com