


Loar Holdings (LOAR) has put fresh numbers on the table, lifting its 2026 and 2027 guidance after a quarter of record adjusted EBITDA and strong organic sales growth.
That guidance upgrade has landed alongside a sharp swing in sentiment. Loar Holdings has logged a 21.3% 30 day share price return and a 7.2% year to date share price gain, yet the 1 year total shareholder return of 1.0% shows that the longer term payoff has been far more modest.
Spot fresh momentum in Loar Holdings, and then compare it with other aerospace and defense players screened for strong fundamentals through our curated list of solid balance sheet and fundamentals (25 results).Loar Holdings now sits at the point where fresh guidance, record adjusted EBITDA and index-driven inflows collide. Is the latest surge more about the business or about sentiment setting a richer price tag?
Most Popular Narrative: 13% Undervalued
Loar Holdings closed at $75.30, while the most followed narrative pegs fair value at $86.20. As a result, sentiment is now rubbing up against a higher fundamental anchor based on that framework.
Loar's focus on proprietary content, with management now citing about 89% of more than 25,000 SKUs as proprietary and no single part contributing more than 3% of revenue, provides a foundation for value based pricing that can support adjusted EBITDA margins around 40.5% and contribute to future profitability and cash generation.
See why 6 investors see Loar Holdings as 13% undervalued.
Result: Fair Value of $86.20 (UNDERVALUED)
Still, two weak spots could puncture the Loar Holdings story: slower conversion of the US$700 million to US$750 million pipeline, and stickier acquisition integration costs.
Find out about the key risks to this Loar Holdings narrative.
Another View: What Loar Holdings’ P/E Says
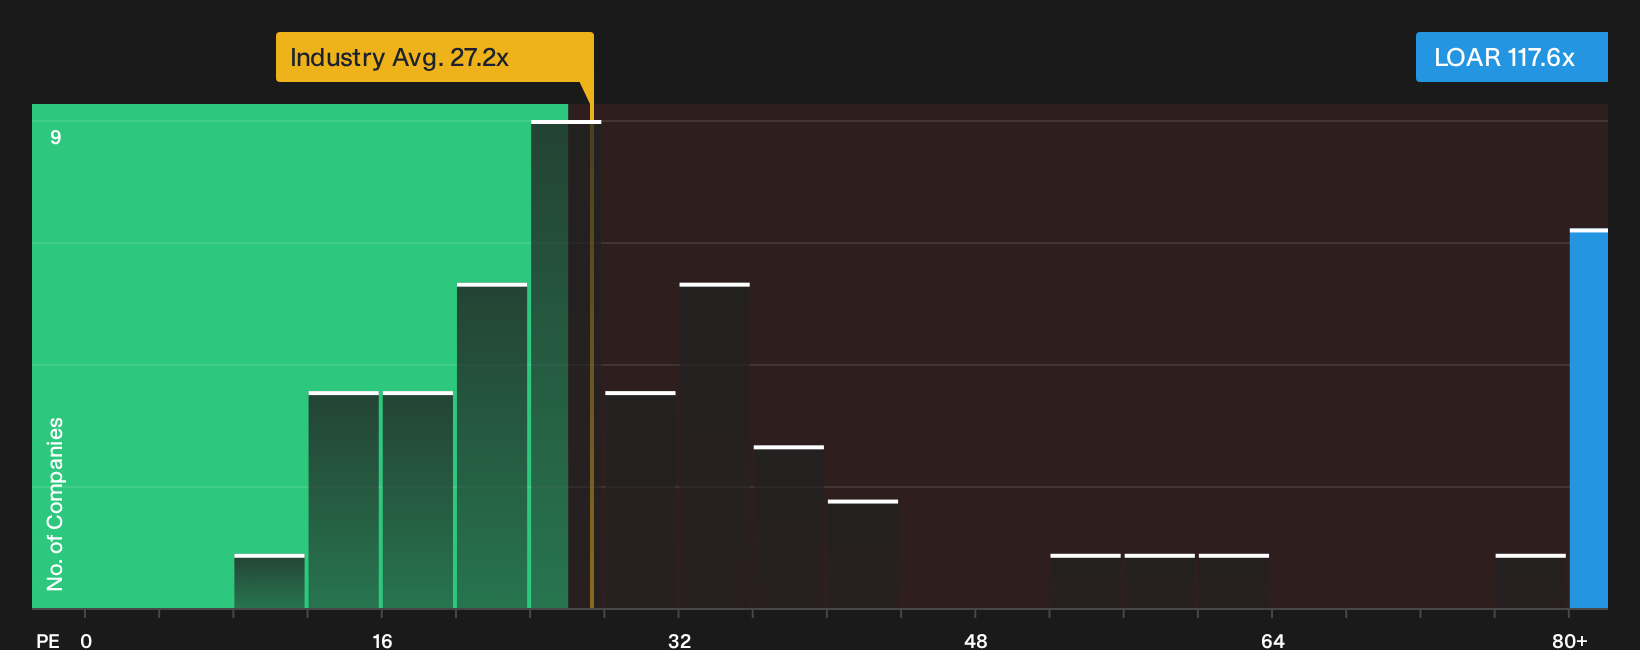
The story looks different when the focus shifts from fair value estimates to the simple P/E yardstick. Loar Holdings trades on roughly 117.6x earnings, compared with 27.2x for the US Aerospace & Defense industry and 55.9x for peers, while the fair ratio sits at 40.8x. That gap points to a rich valuation that leaves less room for error if the growth narrative softens.
For a clearer feel of how this price tag stacks up against earnings power, walk through the valuation breakdown in our P/E based view. Then sense check it against your own expectations for Loar Holdings and how much valuation risk you are willing to carry. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
That tug of war between upbeat narratives and a rich P/E invites you to move fast, stress test the numbers yourself, and decide where you land on Loar Holdings. To weigh both sides of the story, start by grounding your view in the 1 key reward and 1 important warning sign.
Looking for more investment ideas beyond Loar Holdings?
If Loar Holdings has your attention, do not stop there. Broaden your watchlist with other opportunities filtered for quality, resilience and income potential.
- Target potential upside by scanning a curated pool of companies that combine quality fundamentals with discounted valuations through the 38 high quality undervalued stocks.
- Strengthen portfolio resilience by focusing on businesses filtered for sturdier financial footing using the 31 resilient stocks with low risk scores.
- Boost your income options by zeroing in on companies with higher yields and durable payout profiles via the 7 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com