


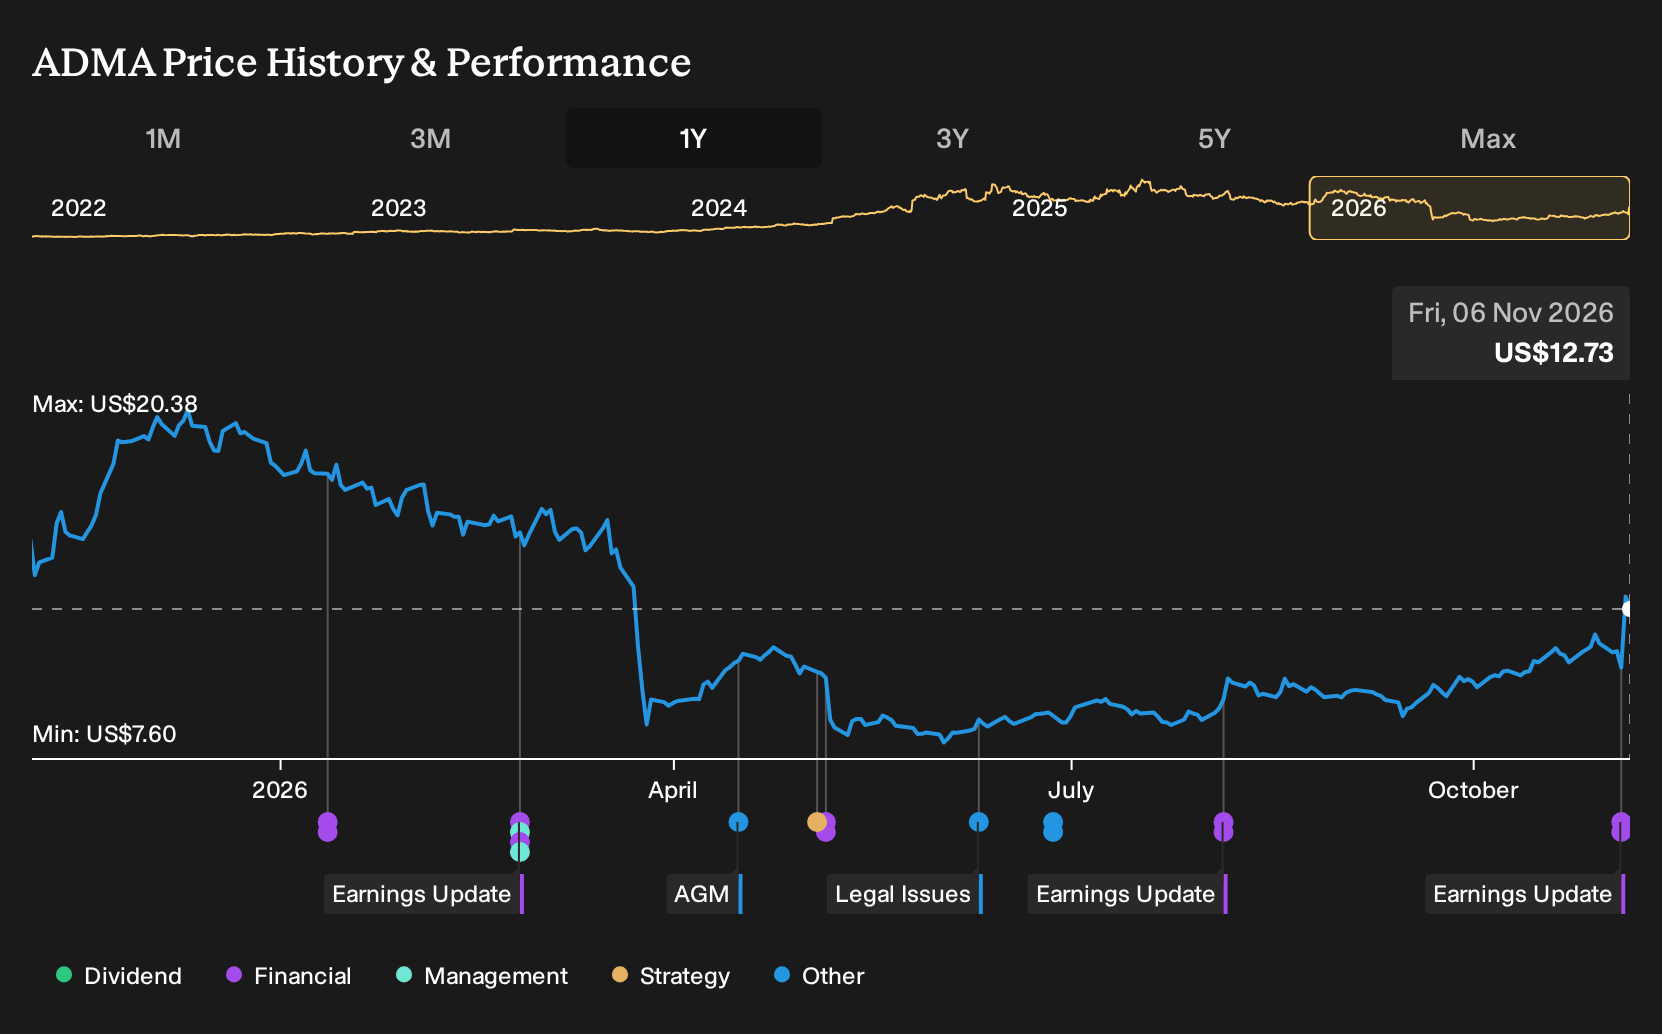
- ADMA Biologics reported third quarter 2026 sales of US$141.1 million and net income of US$49.88 million, with earnings per share from continuing operations at US$0.22 basic and diluted, and reaffirmed at least US$530 million in full year 2026 revenue guidance.
- The earnings detail shows ADMA Biologics delivering higher net income and per share earnings over both the quarter and first nine months, while keeping its revenue outlook intact despite competitive and legal pressures around its immunoglobulin portfolio.
- We will look at how ADMA Biologics' reaffirmed full year revenue guidance affects the investment narrative built around ASCENIV driven margins.
Scan beyond ADMA Biologics and compare its earnings story with a curated list of healthcare peers using the 35 healthcare AI stocks for your next round of ideas.
ADMA Biologics Investment Narrative Recap
To own ADMA Biologics, you need to be comfortable with a focused plasma derived portfolio in which ASCENIV margins and volumes do a lot of the heavy lifting. The third quarter print, with higher net income and earnings per share versus last year, supports that margin story. Reaffirmed full year revenue of at least US$530 million suggests management still sees the current product mix as workable in the near term.
The most important short term swing factor remains how ASCENIV uptake and pricing offset pressure in standard immunoglobulin products such as BIVIGAM. The biggest risk is that competitive discounting or legal outcomes around ASCENIV distribution force changes in contracting or shipping practices. Based on the latest information, the earnings release does not materially change that balance of catalyst versus risk.
The most relevant announcement for this update is ADMA Biologics reaffirming at least US$530 million in 2026 revenue. That signal matters because investors are already watching how yield enhancement in manufacturing and the tilt toward higher margin ASCENIV support profitability. With nine month sales at US$379.99 million, the reiterated goal frames how much execution is still required into year end.
For catalysts, the confirmed outlook keeps attention on a few levers. First, gross margin durability now that the FDA approved yield process is embedded in production. Second, continued ASCENIV adoption following the May 2026 label expansion and real world data. Against those, readers should weigh the concentrated product set, pressure in the broader immunoglobulin market, and the ongoing securities and ASCENIV distribution lawsuits.
ADMA Biologics' current analyst narrative points to US$783.1 million in revenue and US$317.5 million in earnings by 2029, built on 15.2% yearly revenue growth and an earnings increase of about US$148.5 million from US$169.0 million today.
Uncover why ADMA Biologics' fair value indicates a 34% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One bullish twist on ADMA Biologics focuses on the ASCENIV catalyst. The most optimistic analysts were modeling revenue of about US$899.5 million and earnings of roughly US$365.3 million by 2029 before this quarter landed. Those forecasts assume ASCENIV keeps gaining share. This fresh guidance and Q3 detail may push those views in either direction.
Explore 6 other ADMA Biologics fair value estimates, including one that suggests as much as 186% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your ADMA Biologics research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for ADMA Biologics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ADMA Biologics' overall financial health at a glance.
Looking For More Investment Ideas Beyond ADMA Biologics?
If the ADMA Biologics story has sharpened your view on risk, quality and balance sheet strength, it can be useful to line that thinking up against other opportunities using the Simply Wall St Screener.
- For investors who want potential mispricings with quality fundamentals, consider a curated 38 high quality undervalued stocks that match tighter criteria on cash flows and financial strength.
- If capital protection sits high on your list, filter for steadier profiles through a 31 resilient stocks with low risk scores that screens for more resilient balance sheets and risk factors.
- When you want sturdier financial footing as a starting point, use a list of solid balance sheet and fundamentals (25 results) that highlights companies with cleaner leverage and healthier fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com